OTR Tire Market (2026 - 2035)

OTR Tire Market Research Report By Tire Construction (Radial, Bias, Solid / Press-On), By Rim Size (Below 29 inch, 29–39 inch, 39–49 inch, Above 49 inch (Ultra-Class)), By Application (Mining, Construction, Agriculture, Material Handling & Ports), By Sales Channel (OEM Fitment, Replacement / Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/AT/25555-HCR 100 Pages Shubham Munde, Swapnil Palwe Last Updated: September 17, 2026
OTR Tire Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.1%
2025 Market SizeUSD 8.42 Billion
2035 Market SizeUSD 13.84 Billion
Key Players
Bridgestone
Michelin
Goodyear
Titan International
Balkrishna Industries
Yokohama
Opportunities
  • Ultra-Class Capacity as a Scarcity Asset
  • Casing Intelligence and Data Monetisation
  • African and South American Mining Frontiers

OTR Tire Market Summary

The OTR Tire Market closed 2025 at USD 8.42 billion, and the forecast opens in 2026 at USD 8.85 billion before reaching USD 13.84 billion by 2035 — a compound annual growth rate of 5.1% across the 2026–2035 window. Two catalysts anchor that trajectory. Global mining capital expenditure rebuilt to roughly USD 130 billion in 2024 as copper, lithium and iron ore projects moved out of feasibility and into execution [1][12], and the United States Infrastructure Investment and Jobs Act continued to release its USD 110 billion roads-and-bridges tranche into active earthmoving contracts through 2025 [18].

Underneath the headline number sits a quiet engineering shift. Bias-ply casings, which still dominate small-rim agricultural and industrial fleets across South Asia and Africa, are steadily giving way to radial OTR tire construction, which delivers 20–30% longer service life and measurably lower rolling resistance on long haul-road cycles [4][8]. Michelin and Bridgestone together committed more than USD 1.6 billion in capacity and compound-technology investment between 2023 and 2025, much of it aimed at ultra-class 57-inch and 63-inch product lines [4][5]. Sensor-equipped casings that stream pressure and temperature into fleet-management dashboards are moving from pilot to standard fitment on autonomous haulage fleets.

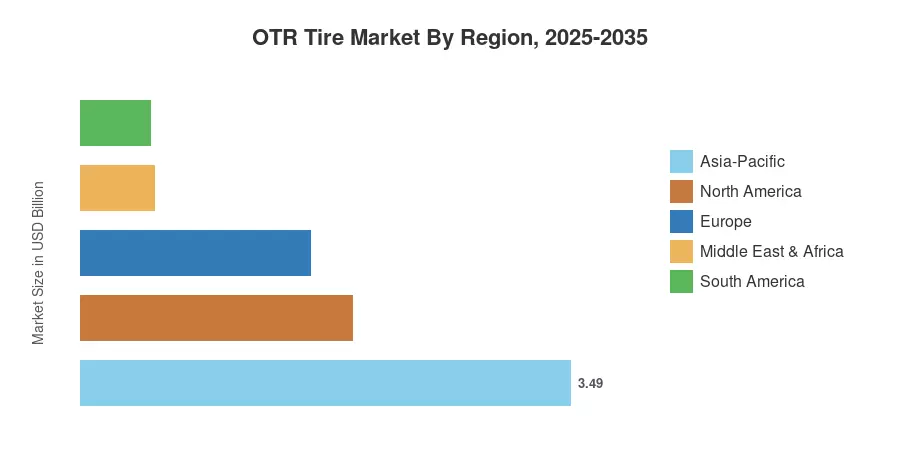
Regionally, Asia-Pacific holds a commanding 41.5% share of the OTR Tire Market, powered by Chinese and Indian construction equipment output plus Australian iron ore and coal haulage. Middle East & Africa grows fastest at a 6.3% CAGR as copper-belt and bauxite projects scale. North America ranks second, sustained by replacement demand from an aging quarry and aggregate fleet. The decade ahead will reward suppliers who can pair ultra-large casing capacity with credible circularity credentials.


Key Report Takeaways

• By Tire Construction

  • Radial casings account for 61.4% of global OTR Tire Market revenue in 2025, reflecting fleet-level total-cost-of-ownership decisions rather than sticker price.
  • Bias-ply volumes are still expanding at a modest 2.4% CAGR in price-sensitive agricultural and light-industrial fleets.

• By Application

  • Mining generates USD 3.61 billion of 2025 revenue, the single largest end-use pool in the OTR Tire Market.
  • Construction and infrastructure applications post a 5.4% CAGR through 2035.
  • Material handling and port equipment hold an 11.8% share, concentrated in automated terminal operators.

• By Region

  • Asia-Pacific commands 41.5% of global revenue.
  • Middle East & Africa records the fastest regional growth at 6.3% CAGR.
  • North America contributes USD 1.94 billion in 2025.


Market Size and Forecast (2021–2035)

=
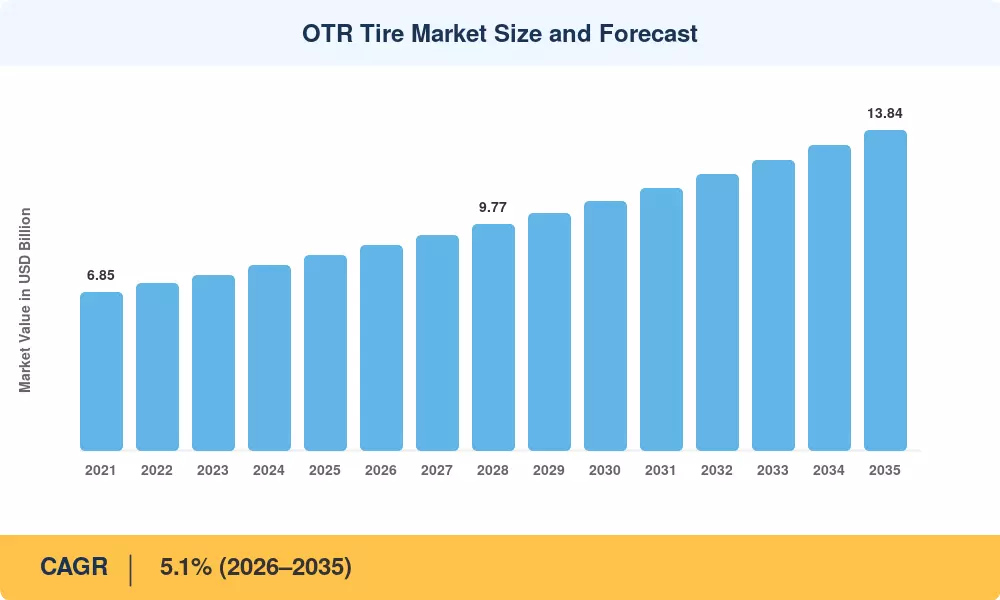
OTR Tire Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Mining capex and critical-minerals demand ~1.1 Global Long-term (≥4 yr)
Infrastructure and construction spending ~0.9 North America, Asia-Pacific Medium-term (2–4 yr)
Radialization of emerging-market fleets ~0.7 India, Brazil, Africa Medium-term (2–4 yr)
Replacement-cycle density in aging fleets ~0.6 Global Short-term (≤2 yr)
Autonomous and electrified haulage adoption ~0.5 Australia, Chile, Canada Long-term (≥4 yr)
Port and terminal automation ~0.4 Europe, North America Medium-term (2–4 yr)
Agricultural mechanization ~0.4 India, Brazil, Southeast Asia Long-term (≥4 yr)


Critical-Minerals Capex Is the Structural Engine

Copper is the pivot. The International Energy Agency [2] said that satisfying clean-energy goals will require copper supply to increase by almost 30% from 2024 levels by 2035 and that more than 40 significant projects have already been sanctioned. With each sanctioned project comes a transport fleet in tow, and a 240-tonne truck uses six ultra-class casings that need replacing around every 6,000 to 9,000 operational hours. Chile’s Cochilco records committed mining investment of USD 83 billion through 2033, a pipeline that flows directly into recurrent tire spend rather than one-off equipment orders [14].


Infrastructure Programs Sustain the Construction Pool

Public works are what keep earthmovers active. By the end of 2025, the US Department of Transportation had committed more than USD 300 billion in IIJA formula and discretionary funding, keeping grader, loader, and articulated-hauler use far above the 2019 baseline [18]. India’s National Infrastructure Pipeline sends a similar signal, with funding for roads and highways rising to almost INR 2.87 trillion in the FY2026 budget [17]. The aftermarket revenue lift is disproportionately large since construction fleets turn over tyres faster than mining fleets on a per-machine basis.


Radialization Rewrites the Replacement Economics

Fleet managers are buying on a cost per hour instead of price per tyre. Independent field tests suggest 20-30% higher radial service life than comparable bias casings on long-cycle haul routes, with 2-4% fuel savings with lower rolling resistance [8][21]. Balkrishna Industries is increasing radial mix to over 60% of OTR volume by FY2024 and is adding carbon-black-backed capacity to meet this [8]. The adjustment will improve average selling price and expand the OTR Tire Market even with flat unit volumes.


Restraints Impact Analysis


Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Natural rubber price volatility ~-0.8 Global Short-term (≤2 yr)
Commodity downcycles and mine deferrals ~-0.7 Australia, Africa, South America Medium-term (2–4 yr)
Retreading and casing life-extension ~-0.6 North America, Europe Long-term (≥4 yr)
Ultra-class capacity and lead-time constraints ~-0.5 Global Medium-term (2–4 yr)
Traceability and circularity compliance cost ~-0.4 Europe Long-term (≥4 yr)


Rubber Price Volatility Compresses Margin Windows

The raw material swings are hitting hard. According to ANRPC data, benchmark natural rubber prices are expected to swing more than 40% between early 2024 and mid-2025, reflecting weather disruption in Thailand and Indonesia, and tighter EU import regulations [11][19]. The gap is absorbed by producers with three-to-six-month contract repricing clauses; those selling into tendered mining supply agreements generally cannot. Margin compression has occasionally put off announced capacity expansions.


Life-Extension Services Cannibalise New-Unit Demand

Retreading is a real option at the ultra-class level. A well-managed 57-inch casing can last for one or two retread cycles at 35–50% of the cost of new tyres, and large mining companies are now including casing management KPIs in contractor agreements [21]. Members of the Tyre Industry Project are witnessing increasing volumes being processed via approved retread routes rather than scrap. Value moves away from product and toward service, which is neutral for suppliers with service arms and negative for pure product manufacturers.


Commodity Cycles Still Set the Ceiling

Deferrals follow prices. Australia's Resources and Energy Quarterly flagged softening metallurgical coal and nickel outlooks into 2026, with several projects pushed beyond original sanction dates [12]. Fleet hours fall before fleet sizes do, and tyre replacement intervals stretch accordingly.


OTR Tire Market Opportunities

Ultra-Class Capacity as a Scarcity Asset

Global 63-inch capacity remains concentrated across fewer than a dozen plants worldwide, and lead times stretched past nine months during the 2024 copper ramp [4]. Suppliers adding qualified ultra-class lines can lock multi-year mine-site supply agreements at premium pricing, insulating themselves from the aftermarket price competition that characterises smaller rim bands.

Casing Intelligence and Data Monetisation

Embedded pressure, temperature and tread-depth sensors turn a consumable into a subscription. Michelin and Bridgestone both operate fleet-analytics platforms that price on a per-hour or per-tonne basis rather than per-unit, converting one-time revenue into recurring streams [4][5]. Mine operators gain haul-road optimisation data worth more than the tyre itself; suppliers gain switching costs.

African and South American Mining Frontiers

Copper-belt expansion in Zambia and the Democratic Republic of Congo, alongside Guinean bauxite, creates greenfield demand where no incumbent distribution network exists [13]. Early distributor and service-hub investment in these corridors buys durable share.

Circularity and Recovered Materials

The EU's end-of-life tyre framework and rising recovered-carbon-black availability let manufacturers market verified circular content to ESG-reporting mining customers [19][22]. Buyers increasingly score bids on Scope 3 disclosure quality, not price alone.

Electrified Haulage Load Profiles

Battery-electric haul trucks carry 8–15% more gross vehicle weight and deliver instantaneous torque, both of which change casing stress profiles [2][20]. Purpose-engineered compounds for electric fleets represent an unclaimed premium niche in the OTR Tire Market.


OTR Tire Market Future Outlook

Autonomous Operations Reshape Wear Modelling

Machine consistency changes everything about tyre life prediction. Autonomous haul trucks follow identical racing lines with sub-metre repeatability, which concentrates haul-road wear and shifts failure modes from sidewall impact toward tread-centre heat build-up [20]. Suppliers that recalibrate compound design for this profile will win qualification on the fleets growing fastest.

Service Economics Overtake Product Economics

Selling hours beats selling rubber. Tyre-management contracts that bundle fitment, monitoring, retread and disposal already cover a meaningful share of large mining accounts, and the model's spread into mid-tier contractors is the most probable margin story of the next decade [5][21].

The Electrification Supercycle

Mineral demand does the work here. The International Energy Agency estimates that clean-energy technologies will require mineral inputs several multiples above 2024 volumes by 2040, which anchors mining fleet hours regardless of individual commodity cycles [2]. Haulage electrification then compounds the effect through heavier axle loads.

Disclosure Becomes a Purchasing Criterion

Reporting standards are tightening across the buyer base. ICMM member companies and CSRD-scoped European operators now request supplier-level Scope 3 and circular-content data as a condition of tender participation [22][19]. The OTR Tire Market will bifurcate between suppliers who can document material provenance and those competing purely on landed cost.


Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America USD 1.94 Billion Aggregate quarrying, IIJA earthmoving, retread services
Europe 19.5% share Port automation, circularity compliance, agricultural radialization
Asia-Pacific 41.5% share Iron ore haulage, construction OEM output, capacity localisation
South America 5.9% CAGR Copper and lithium expansion, contractor fleet growth
Middle East & Africa 6.3% CAGR Copper belt, bauxite, phosphate, Gulf megaprojects
Total USD 8.42 Billion —

Regional performance within the OTR Tire Market tracks two variables closely: installed mining equipment population and the pace of infrastructure disbursement. The table below discloses a single headline metric per region.


North America

Country Metric Key Driver
United States 76.0% of region IIJA-funded highway and aggregate demand [18]
Canada USD 0.32 Billion Oil sands and potash haulage fleets [12]
Mexico 5.8% CAGR Nearshoring-linked industrial construction [16]


Aftermarket depth defines this region. Roughly 70% of North American OTR Tire Market revenue flows through replacement channels, reflecting an equipment population that averages over nine years in age across quarry and aggregate segments [6]. Titan International and Goodyear both expanded distributor service coverage during 2024–2025 to capture on-site fitment revenue [6][7].

Europe

Country Metric Key Driver
Germany 22.4% of region Construction equipment OEM fitment [10]
France USD 0.21 Billion Agricultural fleet radialization [4]
United Kingdom 4.4% CAGR Quarrying and demolition recovery
Rest of Europe 39.8% of region Nordic mining, Iberian port automation [15]


Regulation shapes purchasing here more than anywhere else. The EU Deforestation Regulation forces natural-rubber traceability documentation through the entire supply chain, and compliance readiness has become a tender scoring criterion for public infrastructure contractors [19]. European buyers also lead in specifying retread-ready casings.

Asia-Pacific

Country Metric Key Driver
China 38.5% of region Domestic construction equipment output [16]
India 6.8% CAGR Coal expansion and highway construction [17]
Australia USD 0.62 Billion Iron ore and autonomous haulage fleets [20]
Japan 7.1% of region OEM technology development and export
Rest of Asia-Pacific 11.9% of region Indonesian nickel, Vietnamese infrastructure


Scale and cost advantage converge across this region. Chinese manufacturers including Aeolus and Techking have pushed export share upward by pricing 20–35% below premium Western brands, compressing mid-tier margins globally [16]. Australia meanwhile runs the world's densest autonomous haulage deployment, with more than 1,000 driverless trucks operational across Pilbara operations by 2025 [20].

South America

Country Metric Key Driver
Brazil 44.2% of region Iron ore haulage and agricultural fleets [17]
Chile USD 0.18 Billion Copper expansion capex [14]
Peru 6.1% CAGR Copper and zinc mine development
Rest of South America 17.5% of region Argentine lithium, Colombian coal


Copper economics dominate the narrative. Cochilco's committed investment portfolio and Codelco's structural mine conversions sustain a decade-long haul fleet expansion, while Brazilian agricultural mechanisation adds a second, weather-correlated demand stream [14][17].

Middle East & Africa

Country Metric Key Driver
South Africa 31.0% of region Platinum and coal mining fleets [13]
Saudi Arabia USD 0.09 Billion Giga-project earthmoving programs
Zambia & DRC 7.4% CAGR Copper-belt production expansion [13]
Rest of Middle East & Africa 26.5% of region Guinean bauxite, Moroccan phosphate


Distribution gaps define the opportunity. Zambia has publicly targeted three million tonnes of annual copper output by 2031 against roughly 800,000 tonnes today, a step-change that no existing tyre service network can currently support [13].


OTR Tire Market By Region, 2025-2035

OTR Tire Market Segmentation

By Tire Construction


Segment Metric (2025) Primary Demand Driver
Radial 61.4% share Lower cost-per-hour on long-haul cycles
Bias 2.4% CAGR Price sensitivity in agriculture and light industry
Solid / Press-On USD 0.71 Billion Puncture-free duty in warehouse and port fleets


Radial dominance is a total-cost outcome. Mining and large construction fleets model cost per operating hour, and radial casings win that calculation decisively despite carrying a 30–45% price premium at purchase [8][21]. Bias-ply persists because acquisition budgets in smallholder agriculture and light industrial handling remain capital-constrained; volume there grows slowly but does not disappear. The solid press-on OTR forklift tire segment sits apart from both, driven by zero-downtime requirements in automated distribution facilities rather than by haul economics [15].

By Rim Size


Segment Metric (2025) Primary Demand Driver
Below 29 inch 27.6% share Agricultural tractors and compact loaders
29–39 inch USD 2.10 Billion Articulated haulers and wheel loaders
39–49 inch 5.6% CAGR Mid-size mining and quarry trucks
Above 49 inch (Ultra-Class) 6.9% CAGR Ultra-class haul trucks at large open-pit mines


Ultra-class is where economics get interesting. Fewer than a dozen plants globally hold qualification for 57-inch and 63-inch production, which turns capacity into a scarcity asset and sustains premium pricing through downcycles [4]. The 29–39 inch band, by contrast, faces intense competition from Asian mid-tier producers and carries structurally thinner margins.

By Application


Segment Metric (2025) Primary Demand Driver
Mining USD 3.61 Billion Critical-minerals capex and haul tonnage [2]
Construction 5.4% CAGR Public infrastructure disbursement [18]
Agriculture 21.3% share Mechanisation in India and Brazil [17]
Material Handling & Ports 11.8% share Terminal automation programs [15]


Mining sets the tone for the whole category. Haul tonne-kilometres, not equipment unit sales, drive replacement demand, which is why tyre revenue holds up better than machinery revenue during capex pauses [12]. Construction runs on a different rhythm — shorter equipment lives, faster rotation, heavier aftermarket dependence — and reacts to fiscal policy within two to three quarters.

By Sales Channel


Segment Metric (2025) Primary Demand Driver
OEM Fitment 32.7% share New equipment production volumes
Replacement / Aftermarket 5.5% CAGR Fleet utilisation hours and retread cycles


Aftermarket carries the margin. Replacement channels deliver roughly double the gross margin of OEM fitment because OEM contracts are tendered on price against multi-year volume commitments [6][7]. Manufacturers therefore treat OEM placement as a share-of-fleet investment that pays out over the subsequent replacement cycle.


Competitive Benchmarking

Concentration in the OTR Tire Market is moderate and asymmetric by rim band. Estimated HHI sits near 1,150 on a global revenue basis — technically unconcentrated — but the ultra-class segment behaves like an oligopoly, with the top three producers holding an estimated 70–80% of qualified 57-inch and 63-inch capacity. The top five suppliers together account for roughly 48–54% of global revenue, leaving a long fragmented tail of regional and value-tier producers competing largely on landed cost.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Bridgestone ~15–19% Ultra-class mining radials, VRPS, iTrack monitoring Capacity leader with integrated fleet analytics
Michelin ~13–17% X-Tra Load, MEMS Evolution, Camso solid range Premium technology plus services bundling
Goodyear ~7–10% RM-4B, RL-5K earthmover lines North American aftermarket depth
Titan International ~5–8% Goodyear-branded farm and OTR wheel assemblies Wheel-and-tyre package specialist
Balkrishna Industries (BKT) ~4–7% Earthmax radial series Value-premium challenger, rapid radial expansion
Yokohama (ATG) ~4–6% RB, RL series; Alliance off-highway Off-highway consolidation via acquisition
Continental ~3–5% ContiEarth, RDT-Master Engineering-led entrant with sensor integration
Trelleborg / Mitas ~2–4% Industrial and agricultural OTR Niche precision and material handling focus
Aeolus (Double Coin) ~3–5% Value-tier mining and construction radials Cost-competitive export scaling
Techking ~2–3% Application-specific mining tyres Fast-follower with mine-site engineering support


Recent News & Developments

Selected developments illustrate where capital and strategy are moving within the OTR Tire Market.


  • Michelin (June 2024): Extended its mining fleet-management platform with predictive casing-failure alerts, moving pricing toward per-tonne-hauled contracts [5].
  • Balkrishna Industries (September 2024): Commissioned expanded carbon black capacity in Bhuj to secure raw material supply for radial OTR growth [8].
  • European Union (October 2024): Confirmed phased application of the Deforestation Regulation, extending natural-rubber traceability obligations across tyre supply chains [19].
  • Titan International (February 2024): Completed integration of its Carlstar acquisition, broadening wheel-and-tyre assembly coverage in North American distribution [6].
  • Yokohama Rubber (May 2024): Reported off-highway segment growth outpacing consumer tyre performance, reinforcing ATG-led portfolio rebalancing [9].


  • Goodyear (November 2023): Expanded on-site OTR service coverage across US aggregate and quarry accounts to capture retread and fitment revenue [7].


OTR Tire Market Report Scope

Parameter Detail
Market Scope Global off-the-road tyres across mining, construction, agriculture and material handling applications, covering radial, bias and solid constructions through OEM and replacement channels
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.1% (2026–2035)
Market Size Checkpoints USD 8.42 Billion (2025); USD 8.85 Billion (2026); USD 13.84 Billion (2035)
Fastest Growing Segments Above 49-inch ultra-class rim band; Middle East & Africa region
Companies Profiled Bridgestone, Michelin, Goodyear, Titan International, Balkrishna Industries, Yokohama (ATG), Continental, Trelleborg, Aeolus, Techking
Valuation Currency USD, constant 2025 basis

FAQs

How should procurement teams structure a tender in the OTR Tire Market to avoid lowest-price traps?
Score bids on documented cost-per-operating-hour with casing-return guarantees, not unit price. Require bidders to warrant retread eligibility and supply monitoring data access as contract conditions [21].
What lead times should buyers plan for on ultra-class casings?
Budget six to nine months for 57-inch and 63-inch orders during copper upcycles, with allocation clauses common. Placing rolling forecasts rather than spot orders secures priority [4].
Does the OTR Tire Market carry meaningful counterfeit or grey-import risk?
Yes, particularly in African and Southeast Asian corridors where uncertified imports enter through informal distribution. Verify DOT or E-mark serials and buy through manufacturer-authorised service hubs [13].
How do tyre-monitoring systems change insurance and warranty terms?
Documented pressure and temperature histories increasingly support warranty claims that would otherwise be denied as operator abuse. Several suppliers now offer extended coverage conditional on telemetry participation [5].
What integration barriers slow sensor adoption at mine sites?
Legacy fleet-management platforms often lack open APIs, forcing parallel dashboards that operators ignore. Successful deployments negotiate data interoperability before fitment, not after [20].
Which certifications matter most for suppliers entering the European OTR Tire Market?
Deforestation Regulation traceability documentation for natural rubber is now effectively mandatory for public-sector tenders. ISO 14001 and verified recycled-content claims strengthen scoring further [19].
How does the OTR Tire Market respond during a commodity downturn?
Revenue softens far less than equipment sales because replacement demand follows machine operating hours, which decline gradually. Retread volumes typically rise as operators defer new purchases [12].    
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, trade association reports, and authoritative transportation and industrial organizations. Key sources included the US Department of Transportation (DOT), National Highway Traffic Safety Administration (NHTSA), Tire Industry Association (TIA), Rubber Manufacturers Association (RMA), European Tyre and Rubber Manufacturers' Association (ETRMA), Japan Automobile Tyre Manufacturers Association (JATMA), Association of Natural Rubber Producing Countries (ANRPC), International Rubber Study Group (IRSG), US Geological Survey (USGS) for mining equipment data, US Department of Agriculture (USDA) for agricultural machinery statistics, Eurostat Construction Statistics, International Labour Organization (ILO) for mining sector data, World Bank Infrastructure Development Indicators, Organisation Internationale des Constructeurs d'Automobiles (OICA), and national mining & construction ministry reports from key markets including China, India, Brazil, and Australia. These sources were used to collect equipment sales data, regulatory compliance standards, raw material pricing trends, import/export statistics, and market landscape analysis for radial and bias OTR tires across construction, mining, agriculture, and industrial applications.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Manufacturing, R&D directors, and commercial directors from OEMs, rubber compound suppliers, and OTR tire manufacturers were examples of supply-side sources. Fleet managers from mining enterprises, construction equipment rental firms, agricultural cooperatives, procurement leads from heavy machinery dealers, and maintenance directors from industrial operations were examples of demand-side sources. In addition to gathering information on tire replacement cycles, pricing tactics, and bulk procurement dynamics, primary research verified production capacity expansion timetables and validated market segmentation.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (29%), Asia-Pacific (33%), Rest of World (6%)


Market Size Estimation

Global market valuation was derived through revenue mapping and equipment fleet analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across radial, bias, and solid OTR tire categories by size segments (20-29 inches, 30-39 inches, 40-49 inches, 50-59 inches, 60 inches & above)

Analysis of reported and modeled annual revenues specific to OTR tire portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (equipment fleet size × replacement rates × ASP by country) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for construction, mining, agriculture, and industrial end-use applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.