Tire Pressure Monitoring System Market (2026 - 2035)

Tire Pressure Monitoring System Market Research Report By System Type (Direct, Indirect, Indirect-to-Direct Hybrid), By Sensor Technology (MEMS Capacitive, Piezoelectric, Surface Acoustic Wave, Energy-Harvesting and Other), By Fitting Method (Valve-Stem Mounted, Band or Strap Mounted, Embedded Tire Module), By Frequency Band (433 MHz, 315 MHz, 2.4 GHz and UWB), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, Two-Wheelers), By Sales Channel (OEM Factory-Fit, Aftermarket Retrofit) - Forecast to 2035
ID: MRFR/AT/3215-CR 188 Pages Triveni Bhoyar, Swapnil Palwe Last Updated: September 15, 2026
Tire Pressure Monitoring System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.54%
2025 Market SizeUSD 10.04 Billion
2035 Market SizeUSD 22.76 Billion
Key Players
Continental AG
Sensata Technologies
Pacific Industrial
Huf Group
DENSO Corporation
ZF Friedrichshafen
Opportunities
  • Battery-Less Energy-Harvesting Sensor Nodes
  • Embedded Intelligent Tire Modules and Data Monetization
  • Two-Wheeler Fitment Across India and ASEAN

Tire Pressure Monitoring System Market Summary

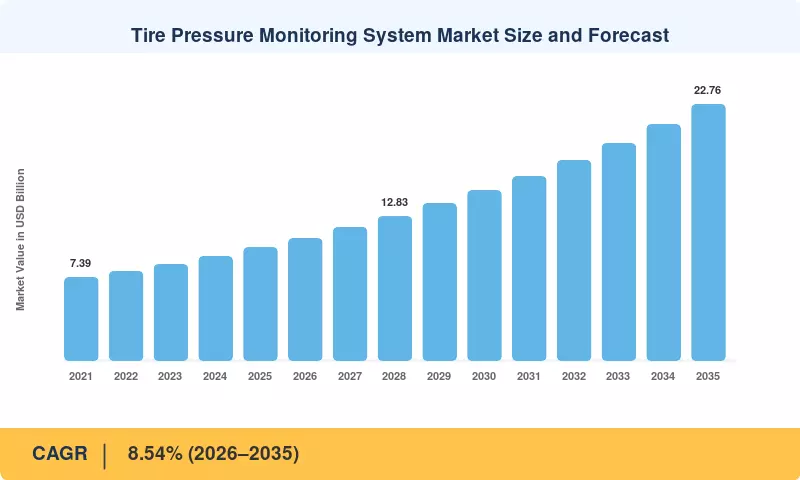
The Tire Pressure Monitoring System Market closed 2025 at USD 10.04 billion and enters the forecast window at USD 10.89 billion in 2026, climbing to USD 22.76 billion by 2035 at an 8.54% CAGR. Two catalysts anchor that trajectory. UNECE Regulation No. 141, now referenced by more than 55 contracting parties, extended mandatory pressure monitoring to categories that were previously exempt, while the European Union's General Safety Regulation 2019/2144 tied type approval renewals to a broader safety package that treats tire telemetry as baseline equipment rather than an option [1][2].

Architecture is changing underneath the volume story. Battery-powered valve-stem transmitters that report a single pressure value are giving way to multi-parameter nodes that stream pressure, temperature, acceleration and load estimates into the vehicle's domain controller. Automakers committed roughly USD 1.2 trillion to electrification and software-defined vehicle programs between 2022 and 2030, and tire telemetry has been folded into that budget because underinflation of 20% can cut battery-electric range by 3–5% [3][7]. That energy penalty converts a compliance component into an efficiency instrument.

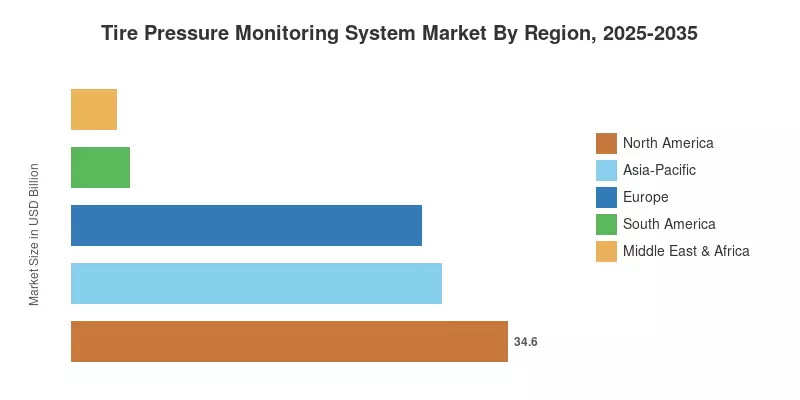
Regionally, North America held 34.6% of the Tire Pressure Monitoring System Market in 2025 on the strength of FMVSS 138 and a large replacement parc. Asia-Pacific compounds fastest at 8.89% through 2035, driven by Chinese GB 26149 enforcement and Indian two-wheeler pilots. Europe ranks second at 27.8%, where premium clamp-in valve fitment and cybersecurity type approval sustain higher unit pricing. The next decade rewards suppliers who sell data pipelines, not just sensors.


Key Report Takeaways

• By System Type

  • Direct architectures captured 59.4% of the Tire Pressure Monitoring System Market in 2025, retaining leadership through the forecast period.


• By Sensor Technology

  • MEMS capacitive sensing elements accounted for 55.0% of installed technology share in 2025


• By Frequency Band

  • The 2.4 GHz and ultra-wideband frequency class is advancing at an 8.87% CAGR to 2035

• By Vehicle Type

  • Passenger cars represented 67.5% of the Tire Pressure Monitoring System Market in 2025
  • Two-wheeler fitment is the fastest-expanding vehicle category at an 8.72% CAGR through 2035


• By Sales Channel

  • Aftermarket retrofit channels are compounding at an 8.85% CAGR, outpacing factory-fit volumes.

• By Region

  • North America commanded 34.6% of the Tire Pressure Monitoring System Market in 2025
  • Asia-Pacific is growing at an 8.89% CAGR through 2035, the fastest of any region.
  • Europe generated USD 2.79 billion in 2025, supported by type approval renewal cycles.


Market Size and Forecast (2021–2035)

Historical values were reconstructed from vehicle production volumes reported by OICA, sensor shipment disclosures in supplier annual reports, and replacement-cycle modelling built on regional vehicle parc age curves [4][11][14]. Forecast years apply a bottom-up build combining new-vehicle fitment rates by regulation status, aftermarket replacement intervals of 6–8 years, and average selling price erosion of roughly 2% annually on commodity valve-stem units, partially offset by content growth in premium multi-parameter nodes.
Tire Pressure Monitoring System Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory mandates widening to new vehicle categories +1.9 Europe, Asia-Pacific, South America Short-term (≤2 yr)
Electrification and range-efficiency pressure +1.6 Global Medium-term (2–4 yr)
Commercial fleet operating-cost programs +1.3 North America, Europe Medium-term (2–4 yr)
MEMS and ASIC cost deflation enabling low-price fitment +1.1 Asia-Pacific Long-term (≥4 yr)
Connected-vehicle and OTA-capable sensor architectures +0.9 North America, Europe Long-term (≥4 yr)
Aftermarket retrofit demand in high-parc economies +0.7 Asia-Pacific, Middle East & Africa Short-term (≤2 yr)
Insurance telematics and usage-based premium linkage +0.6 North America, Europe Long-term (≥4 yr)


Regulatory Mandates Widening to New Vehicle Categories

Regulation remains the single largest volume lever in the Tire Pressure Monitoring System Market. UNECE Regulation No. 141 extended pressure monitoring obligations beyond M1 passenger cars into N1 light commercial vehicles, and the European Union's General Safety Regulation 2019/2144 made compliance a condition of continued type approval for all new registrations from July 2024 [1][2]. India's Central Motor Vehicles Rules amendments and Brazil's CONTRAN Resolution 972 follow the same template, adding roughly 14 million annually addressable units by 2028 [13][16].

Electrification and Range-Efficiency Pressure

The economic benefit of precise tire-pressure monitoring is increasing with electric vehicles. Pressure variations have a greater impact on energy consumption and tire wear since battery packs add bulk to the vehicle and reduce rolling resistance, which is essential for maintaining driving range. In order to identify underinflation before it significantly impacts range, manufacturers are increasingly combining TPMS data with energy-management and driver-information systems as EV penetration grows across passenger cars and commercial fleets. In order to accommodate higher-value sensor architectures across new electric vehicle platforms, the increasing proportion of EVs causes TPMS to change from a fundamental safety feature to a range-efficiency and predictive-maintenance input.


Commercial Fleet Operating-Cost Programs

Here, fleet economics are exceptionally tidy. Correct inflation is linked to around 1.4% fuel savings and a quantifiable decrease in roadside tire incidents, which average USD 500–700 per incident for Class 8 tractors, according to U.S. Department of Energy SuperTruck projects and FMCSA maintenance data [6][8]. Nowadays, big logistics companies combine pressure telemetry with predictive-maintenance dashboards, turning a component purchase into a monthly subscription per asset that suppliers can more easily defend on price.


MEMS and ASIC Cost Deflation

Unit economics decide whether low-price vehicle segments get fitted at all. Average sensor bill-of-materials fell roughly 30% between 2019 and 2025 as MEMS pressure dies shrank and transmitter functions consolidated into single-package ASICs [11]. That deflation is what makes two-wheeler and entry-hatchback fitment viable in India and ASEAN, where a USD 4 delta per wheel position historically decided the specification.

Connected-Vehicle and OTA-Capable Sensor Architectures

Software-defined vehicle programs changed what buyers expect from a sensor node. UNECE Regulation No. 155 requires certified cybersecurity management across the vehicle lifecycle, and suppliers that can authenticate sensor payloads and push signed firmware updates over the air command a 12–18% price premium over commodity transmitters [5]. Continental's 2024 telematics agreement with Samsara illustrated the shift from one-time hardware margin toward recurring analytics revenue [15].

Aftermarket Retrofit Demand in High-Parc Economies

Replacement volume grows even where new-vehicle mandates do not apply. Vehicle parcs across Asia-Pacific and the Middle East contain an estimated 210 million units built before local monitoring rules took effect, and retrofit kits priced between USD 45 and USD 90 have found steady uptake through independent workshops and e-commerce channels [13]. Growth here is price-elastic and channel-driven rather than regulation-driven.

Insurance Telematics and Usage-Based Premium Linkage

Insurers began experimenting with tire condition as an underwriting input in 2024. Several European motor insurers now offer premium reductions of 3–6% for fleets that demonstrate documented pressure compliance through telematics feeds, a mechanism that transfers part of the sensor's cost onto the risk-pricing side of the ledger [19]. Adoption is early, but it establishes a second buyer for the same data stream.


Restraints Impact Analysis

Restraint weightings are directional estimates of drag on growth momentum rather than deductions from the headline CAGR. Each restraint interacts with the drivers above, and several are expected to weaken as component design and service infrastructure mature across the Tire Pressure Monitoring System Market.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Finite sensor battery life and end-of-life friction -1.1 Global Medium-term (2–4 yr)
Protocol fragmentation and service-bay complexity -0.9 North America, Europe Short-term (≤2 yr)
Price sensitivity in entry-level and two-wheeler segments -0.8 Asia-Pacific, South America Long-term (≥4 yr)
Counterfeit and non-homologated replacement parts -0.6 Middle East & Africa, Asia-Pacific Short-term (≤2 yr)
Cybersecurity certification cost burden -0.5 Europe Medium-term (2–4 yr)


Finite Sensor Battery Life and End-of-Life Friction

Valve-stem transmitters' sealed lithium cells usually survive six to ten years before the entire device is thrown away. Owners must pay between USD 60 and USD 120 per wheel to replace the TPMS sensor batteries on the majority of designs, which discourages legitimate replacement volume and pushes customers into warning-lamp suppression [9]. Although they address this, energy-harvesting prototypes still account for less than 3% of shipments.


Protocol Fragmentation and Service-Bay Complexity

The expense of a dispersed installation base is borne by independent workshops. More than 300 different sensor protocols are listed by aftermarket data sources spanning model years, and depending on the vehicle, TPMS sensor relearn programming may call for an OBD interface, a stationary drive cycle, or a tool particular to the brand [10]. Smaller stores are deterred from supplying the category by this variability, which adds 20 to 40 minutes of labor to every task.


Price Sensitivity in Entry-Level and Two-Wheeler Segments

Cost still gates adoption at the bottom of the market. In India and Indonesia, where a large share of two-wheelers retail below USD 1,300, a four-position monitoring system representing 1.5–2.5% of vehicle price is difficult to justify without a mandate [13]. Manufacturers therefore deploy single-channel or indirect approximations that generate materially lower revenue per vehicle.

Counterfeit and Non-Homologated Replacement Parts

Uncertified replacement sensors circulate widely through informal channels. Customs seizures and supplier test programmes have identified counterfeit units failing radio conformity and sealing standards, with reported field failure rates several times higher than homologated equivalents [18]. Beyond the direct revenue leakage, warranty disputes and reputational damage discourage OEM-branded parts pricing in affected regions.

Cybersecurity Certification Cost Burden

Compliance overhead compresses margin for smaller suppliers. Meeting UNECE Regulation No. 155 alongside ISO/SAE 21434 requires documented threat analysis, secure development processes and audited update pipelines, work that industry estimates place at USD 1.5–4 million per product family [5]. Tier-2 sensor specialists without existing automotive cybersecurity infrastructure face a genuine barrier to European type approval.


Tire Pressure Monitoring System Market Opportunities

Battery-Less Energy-Harvesting Sensor Nodes

The most common service complaint in the market is eliminated when the cell is removed. From laboratory demonstrators to supplier validation fleets, piezoelectric and electromagnetic harvesters that scavenge rotational energy may be able to achieve lifetime warranty status that charges a 20–25% price premium by doing away with regular replacement. First-commercializing suppliers will decrease the payback period for fleet customers while immediately attacking the cited constraint.


Embedded Intelligent Tire Modules and Data Monetization

In order to measure tread depth, load, and road friction in addition to pressure, tire makers are moving the sensor from the valve to the inner liner. In order to transform a component sale into a recurring data relationship, Bridgestone and Michelin have connected embedded modules to tire-as-a-service contracts billed per kilometer [17][20]. Vendors of independent sensors are under pressure to demonstrate value beyond simple pressure measurements as a result of this change in business model.


Two-Wheeler Fitment Across India and ASEAN

Emerging markets hold the largest unpenetrated unit pool in the Tire Pressure Monitoring System Market. India registered over 17 million two-wheelers in FY2025, a category with fitment rates below 6%, and regulatory consultations on powered two-wheeler safety equipment are active [13][16]. Even partial mandates would add tens of millions of low-ASP units annually, favouring suppliers with local manufacturing and aggressive cost engineering.

Ultra-Wideband Convergence with Digital Key Radio Stacks

Vehicles already carrying ultra-wideband anchors for phone-as-key and child-presence detection can reuse that radio infrastructure for tire telemetry. Sharing the stack removes a dedicated 433 MHz receiver from the bill of materials and improves localisation accuracy, which eliminates auto-location relearn steps entirely. Semiconductor vendors positioning combined anchor silicon stand to capture disproportionate value as this architecture scales after 2029.

Fleet Predictive-Maintenance Subscription Platforms

Analytics margins exceed hardware margins by a wide multiple. Bundling continuous pressure and temperature streams into predictive-maintenance dashboards allows suppliers in the Tire Pressure Monitoring System Market to charge USD 2–5 per asset per month, revenue that persists long after the sensor sale amortises. Continental's telematics partnership and Sensata's fleet-facing software portfolio both target this pool, and adoption is strongest among operators running more than 500 tractors [15][21].


Tire Pressure Monitoring System Market Future Outlook

Sensor Fusion and Autonomous Vehicle Readiness

Autonomy raises the stakes on tire state estimation because a driverless vehicle cannot feel a developing problem through the steering wheel. Path-planning stacks increasingly ingest pressure, temperature and inferred friction data to modulate speed on degraded surfaces, and the Tire Pressure Monitoring System Market will supply that input as a safety-rated signal rather than a dashboard warning. Expect ASIL-rated sensor nodes with redundant transmission paths to become standard on Level 3 and above platforms from 2029 onward [5].

Platform Economics and Recurring Revenue

Hardware margin compression is arriving faster than volume growth in commodity segments. Suppliers are responding by attaching analytics layers that price per asset per month, a model that already generates a meaningful share of fleet-facing revenue at the largest tier-1 players [15][21]. The competitive question by 2030 is not who builds the cheapest transmitter but who owns the data contract with the fleet operator, and that shift favours vendors with existing telematics installed bases.

Electrification Supercycle and Energy Accounting

The International Energy Agency projects electric vehicles could represent a substantial majority of new car sales in leading markets by 2035 under announced-pledge scenarios [3]. Every one of those vehicles converts tire pressure from a safety metric into an energy metric, since rolling resistance directly consumes battery capacity that regulators certify and consumers monitor daily. Automakers will therefore specify higher-accuracy sensing with tighter measurement tolerances, lifting average content value even where unit volumes plateau.

Circularity and Sustainability Reporting

End-of-life handling is becoming a procurement criterion. Embedded lithium cells complicate tire recycling streams, and European extended producer responsibility frameworks are pushing manufacturers to document material recovery for electronic components fitted inside tires [22]. Suppliers offering harvester-powered or cell-free designs gain a measurable sustainability-reporting advantage with fleet buyers who publish Scope 3 disclosures, adding a non-price dimension to competitive selection through the 2030s.


Regional Market Share Analysis

Region Market Share, 2025 (%) Primary Investment Themes
North America 34.6 Fleet telematics integration, replacement parc depth, FMVSS compliance
Europe 27.8 Cybersecurity type approval, premium clamp-in valves, commercial vehicle extension
Asia-Pacific 29.4 Two-wheeler fitment, local sensor manufacturing, cost engineering
South America 4.6 CONTRAN phase-in, aftermarket retrofit distribution
Middle East & Africa 3.6 High-temperature durability, counterfeit control, fleet mining and logistics
Total 100.0 —

Regional performance in the Tire Pressure Monitoring System Market tracks two variables: how early a mandate took effect and how large the addressable vehicle parc has become. Mature mandate regions monetise through replacement cycles and content upgrades, while late-mandate regions still capture first-fitment volume growth.


North America

Country Metric Key Driver
US 71.5% of regional share FMVSS 138 replacement cycle and fleet telematics adoption
Canada USD 0.55 Billion (2025) Severe winter pressure variance driving service demand
Mexico 8.91% CAGR (2026–2035) Light-truck assembly expansion and export platform alignment

North America anchors the Tire Pressure Monitoring System Market on regulatory maturity rather than growth rate. FMVSS 138 has required direct or equivalent monitoring on light vehicles since 2007, producing a fully penetrated parc where revenue now comes from replacement, content upgrades and fleet analytics rather than first fitment [8]. Canadian and Mexican demand follows the same North American platform architectures, though Mexico's younger parc and expanding light-truck assembly base give it the region's steepest growth curve.


Europe

Country Metric Key Driver
Germany 26.5% of regional share Premium OEM specification and supplier headquarters density
UK USD 0.46 Billion (2025) Independent aftermarket network depth
France 8.42% CAGR (2026–2035) Commercial vehicle fleet electrification programmes
Italy USD 0.31 Billion (2025) Tire manufacturing base and embedded module pilots
Spain 7.9% of regional share Light vehicle assembly for export platforms
Nordic Countries USD 0.17 Billion (2025) Seasonal tire changeover doubling service touchpoints
Russia 5.7% of regional share Domestic assembly substitution and retrofit demand
Rest of Europe 8.05% CAGR (2026–2035) Type approval harmonisation across accession states

European demand is unusually value-dense because premium marques specify lightweight clamp-in aluminium valves and multi-parameter nodes as standard. The General Safety Regulation tied continued type approval to a broad advanced-safety package from July 2024, and UNECE Regulation No. 155 layered cybersecurity certification on top, raising both compliance cost and average selling price [2][5]. Germany dominates through OEM headquarters concentration, while the United Kingdom and France contribute large independent aftermarket networks that sustain replacement volume.


Asia-Pacific

Country Metric Key Driver
China 40.0% of regional share GB 26149 enforcement and domestic sensor cost leadership
India 9.62% CAGR (2026–2035) Two-wheeler and entry-hatchback fitment expansion
Japan USD 0.55 Billion (2025) Mini-vehicle fitment leadership and supplier base
South Korea 10.5% of regional share Premium platform content and connected-car rollout
ASEAN 9.14% CAGR (2026–2035) Assembly localisation and rising safety regulations
Rest of Asia-Pacific USD 0.20 Billion (2025) Aftermarket retrofit through e-commerce channels

Asia-Pacific delivers the fastest expansion in the Tire Pressure Monitoring System Market at 8.89% through 2035. China enforces GB 26149 across passenger and, progressively, commercial categories, and domestic sensor makers have compressed prices enough to make fitment standard on sub-USD 15,000 vehicles [12]. India represents the region's largest structural upside because two-wheeler penetration remains minimal against annual registrations exceeding 17 million units, while Japan and South Korea contribute high-specification content through mini-vehicle and premium platforms respectively [16].


South America

Country Metric Key Driver
Brazil 56.5% of regional share CONTRAN phase-in and export platform standardisation
Argentina USD 0.09 Billion (2025) Aftermarket replacement in an ageing vehicle parc
Rest of South America 7.68% CAGR (2026–2035) Workshop-channel retrofit kit distribution

South America is transitioning from a retrofit-led to a mandate-led market. Brazil's CONTRAN Resolution 972 progressively extended electronic safety requirements across new vehicle categories, and local assembly plants operated by global automakers have aligned specifications with export platforms rather than maintaining regional variants [16]. Argentina's demand remains dominated by aftermarket replacement given currency-constrained new vehicle sales, while Andean and Southern Cone markets grow primarily through workshop-channel retrofit kits.


Middle East & Africa

Country Metric Key Driver
Saudi Arabia 30.6% of regional share SASO conformity requirements and fleet renewal spending
UAE USD 0.08 Billion (2025) Logistics fleet modernisation and high-temperature durability specs
South Africa 7.95% CAGR (2026–2035) Mining and long-haul trucking safety programmes
Egypt USD 0.04 Billion (2025) Local assembly growth and import standard tightening
Rest of MEA 16.7% of regional share Aftermarket retrofit in ageing commercial parcs

Ambient temperature defines the engineering brief across this region. Gulf operating conditions regularly exceed 50°C, accelerating pressure variance and elevating blowout risk, which makes monitoring a practical necessity rather than a compliance formality in commercial and mining fleets [18]. Saudi Arabian standards authority requirements and UAE fleet modernisation programmes drive specification, while South Africa contributes mining and long-haul logistics demand. Counterfeit replacement parts remain the region's most persistent commercial obstacle.


Tire Pressure Monitoring System Market By Region, 2025-2035

Tire Pressure Monitoring System Market Segmentation

By System Type

Segment Metric Primary Demand Driver
Direct 59.4% share (2025) Regulatory acceptance and per-wheel measurement accuracy
Indirect USD 2.70 Billion (2025) Zero-hardware cost on ABS-equipped entry vehicles
Indirect-to-Direct Hybrid 8.70% CAGR (2026–2035) Redundancy for autonomous and electric platforms


Direct architectures dominate the Tire Pressure Monitoring System Market because most regulators require an absolute pressure reading per wheel position, which wheel-speed inference cannot reliably provide when all four tires deflate together. Indirect systems survive in cost-driven European and Asian segments where ABS hardware is already present. Hybrid configurations grow fastest as automakers pair a direct node with wheel-speed cross-checking to satisfy functional safety redundancy requirements on higher-automation platforms.

By Sensor Technology

Segment Metric Primary Demand Driver
MEMS Capacitive 55.0% share (2025) Low power draw and mature high-volume supply base
Piezoelectric 8.76% CAGR (2026–2035) Energy-harvesting compatibility and shock tolerance
Surface Acoustic Wave USD 1.25 Billion (2025) Passive operation without an onboard power cell
Energy-Harvesting and Other USD 0.78 Billion (2025) Elimination of scheduled replacement events


MEMS capacitive dies hold the majority position through cost and power efficiency, with foundry capacity supporting shipments at automotive quality levels. Piezoelectric elements grow faster because they double as vibration harvesters, aligning with the battery-free roadmap described in. Surface acoustic wave devices occupy a durable niche in high-temperature commercial applications where passive operation removes the failure mode that most frustrates fleet maintenance teams.

By Fitting Method

Segment Metric Primary Demand Driver
Valve-Stem Mounted 63.2% share (2025) Established service tooling and universal aftermarket support
Band or Strap Mounted USD 2.22 Billion (2025) Commercial vehicle and heavy-duty wheel compatibility
Embedded Tire Module 8.79% CAGR (2026–2035) Multi-parameter sensing and tire-as-a-service contracts


Valve-stem mounting remains the default because every tire shop in the world already owns the tooling, and replacement economics depend on that ubiquity. Band-mounted units persist in truck and bus applications where wheel geometry and rim materials preclude valve integration. Embedded modules expand fastest as tire makers bond sensors to the inner liner, unlocking tread and load estimation that a valve-mounted device physically cannot measure.

By Frequency Band

Segment Metric Primary Demand Driver
433 MHz 56.5% share (2025) European and Asian spectrum allocation and range performance
315 MHz USD 3.03 Billion (2025) North American and Japanese legacy platform installed base
2.4 GHz and UWB 8.87% CAGR (2026–2035) Shared radio stack with digital key and interior sensing


The 433 MHz class leads on installed base because European and Asian regulators allocated that band to short-range devices decades ago, and platform inertia is powerful in automotive radio design. The 315 MHz band remains entrenched in North American and Japanese architectures. Ultra-wideband grows fastest by consolidating hardware, since anchors already deployed for phone-as-key can localise tire nodes without a dedicated receiver.

By Vehicle Type

Segment Metric Primary Demand Driver
Passenger Cars 67.5% share (2025) Universal mandate coverage across major markets
Light Commercial Vehicles USD 1.64 Billion (2025) Last-mile delivery fleet expansion and duty-cycle intensity
Medium and Heavy Commercial Vehicles USD 1.14 Billion (2025) Multi-axle configurations requiring six or more sensors
Two-Wheelers 8.72% CAGR (2026–2035) Emerging-market safety regulation and cost deflation


Passenger cars dominate on volume, with mandate coverage across North America, Europe, China, Japan and Korea leaving little unpenetrated ground. Commercial vehicles punch above their unit count because a tractor-trailer combination can carry eighteen or more monitored positions. Two-wheelers grow fastest from a low base, contingent on regulatory action in India and ASEAN where affordability rather than technology has been the binding constraint.

By Sales Channel

Segment Metric Primary Demand Driver
OEM Factory-Fit 63.9% share (2025) Type approval requirements at point of manufacture
Aftermarket Retrofit 8.85% CAGR (2026–2035) Sensor end-of-life replacement and older parc upgrades


Factory fitment supplies the majority of revenue because mandates attach at registration, and OEM contracts lock multi-year volumes at negotiated prices. The aftermarket grows faster for a structural reason: every sensor sold at the factory becomes a replacement opportunity six to ten years later, and the 2016–2020 fitment wave now enters its replacement window. Margins run materially higher in the aftermarket, which is why tier-1 suppliers defend branded replacement programmes aggressively.


Competitive Benchmarking

Concentration in the Tire Pressure Monitoring System Market sits in the moderate band, with an estimated Herfindahl-Hirschman Index between 900 and 1,150 and a top-five combined share of roughly 52–58%. That structure reflects genuine barriers built from homologation scope rather than capital intensity: a supplier must maintain radio conformity approvals, functional safety documentation and cybersecurity certification across dozens of jurisdictions before an automaker will consider a sourcing award. Semiconductor vendors and tire manufacturers are entering from adjacent positions, which should erode the incumbent hierarchy modestly by 2030 without producing outright fragmentation.

Company Est. Revenue Share Range Key Offerings for Tire Pressure Monitoring System Market Strategic Positioning
Continental AG ~15–18% Direct sensor modules, receiver ECUs, fleet telematics analytics Broadest OEM pipeline; pivoting toward subscription data services [15]
Sensata Technologies ~13–16% Sensor ASICs, Schrader-branded replacement programme, fleet software Aftermarket brand leadership plus electrification-focused R&D [21]
Pacific Industrial ~8–11% Valve-stem transmitters, mini-vehicle optimised units Dominant in Japanese kei and compact fitment
Huf Group ~7–10% Lightweight clamp-in valves, IntelliSens universal sensors Premium German OEM specification and programmable aftermarket range
DENSO Corporation ~6–9% Integrated receiver modules, body-domain controller integration Deep Toyota-group alignment and systems integration depth
ZF Friedrichshafen ~4–6% Commercial vehicle monitoring, trailer telematics Heavy-duty and trailer segment focus through braking portfolio
NXP Semiconductors ~3–5% Tire sensor ASICs, UWB anchor silicon Silicon-level position enabling radio stack consolidation
Infineon Technologies ~3–5% Pressure sensor dies, secured microcontrollers Hardware security module integration for UNECE R155 compliance
Bridgestone Corporation ~2–4% Embedded intelligent tire modules, fleet service contracts Tire-as-a-service data bundling from the tire side [17]
Michelin Group ~2–4% Inner-liner sensing, connected tire service platforms Usage-based tire contracts for commercial fleets [20]
Alps Alpine ~2–3% Compact transmitter modules, two-wheeler solutions Cost-engineered designs for Asian volume platforms


Recent News & Developments

  • Continental (July 2024): Signed a telematics data agreement with Samsara, integrating tire pressure and temperature streams into commercial fleet dashboards and signalling a shift from hardware margin toward recurring analytics revenue [15]
  • European Commission (July 2024): Completed the General Safety Regulation 2019/2144 phase-in, making advanced safety equipment including tire pressure monitoring a condition of registration for all new vehicles sold in the bloc [2]
  • Sensata Technologies (March 2024): Outlined an expanded R&D programme targeting next-generation sensor silicon for electrified platforms, emphasising lower quiescent current and extended service life [21]
  • UNECE WP.29 (January 2024): Advanced supplementary provisions under Regulation No. 141, tightening measurement tolerance and malfunction indication requirements for newly type-approved vehicle categories [1]
  • Bridgestone (September 2024): Expanded its embedded intelligent tire module programme with commercial fleet pilots linking tread and pressure telemetry to per-kilometre service contracts [17]
  • NXP Semiconductors (May 2025): Introduced automotive ultra-wideband anchor silicon supporting combined digital key, interior sensing and tire node localisation on a shared radio stack [11]
  • Ministry of Road Transport and Highways, India (November 2024): Opened technical consultation on extending electronic safety equipment requirements to additional vehicle categories, including powered two-wheelers [16]
  • Michelin (February 2025): Broadened its connected tire service platform for long-haul fleets, bundling pressure compliance reporting with usage-based contract pricing [20]


Tire Pressure Monitoring System Market Report Scope

Parameter Detail
Market Scope Global direct, indirect and hybrid tire pressure monitoring systems across passenger, commercial and two-wheeler applications, covering OEM factory-fit and aftermarket retrofit channels
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.54% (2026–2035)
Market Size Checkpoints USD 10.04 Billion (2025); USD 10.89 Billion (2026); USD 15.11 Billion (2030); USD 22.76 Billion (2035)
Fastest Growing Segments 2.4 GHz and UWB frequency band; embedded tire modules; two-wheelers; aftermarket retrofit channel
Companies Profiled Continental, Sensata Technologies, Pacific Industrial, Huf Group, DENSO, ZF Friedrichshafen, NXP Semiconductors, Infineon Technologies, Bridgestone, Michelin, Alps Alpine
Valuation Currency USD Billion, constant 2025 prices

FAQs

What procurement criteria matter most when a fleet buyer selects a supplier in the Tire Pressure Monitoring System Market?
Prioritise protocol coverage across your mixed parc, documented radio homologation for every country you operate in, and API access to raw telemetry. Locked data formats are the most common source of buyer regret [21].
For a mixed commercial fleet, does direct or indirect monitoring deliver better total cost of ownership?
Direct systems win on multi-axle trailers because indirect inference degrades badly with heavy load variance. The hardware premium typically pays back within 18 months through avoided roadside tire events [6].
How much homologation risk should a new entrant expect in the Tire Pressure Monitoring System Market?
Expect 18–30 months and seven-figure spending to assemble radio conformity, functional safety and cybersecurity dossiers before a first sourcing award. Certification scope, not manufacturing capital, is the real barrier [5].
Who carries liability when a monitoring sensor fails on a leased commercial vehicle?
Liability usually follows the maintenance contract rather than the lease itself. Negotiate explicit sensor coverage terms upfront, because ambiguity here generates most fleet disputes after warranty expiry [9].
What integration challenges most often delay deployments in the Tire Pressure Monitoring System Market?
Auto-location conflicts on vehicles with rotating tire positions cause the majority of commissioning delays. Receiver placement on composite-bodied trailers is the second most frequent issue [10].
Can existing sensors estimate tread wear or vehicle load?
Valve-stem units cannot measure tread directly, though temperature and pressure trends allow rough load inference. Only inner-liner embedded modules provide genuine wear and friction estimation [17].
How do semiconductor sourcing and tariff shifts affect supplier margins?
Sensor ASICs represent roughly 35–45% of unit cost, so foundry pricing moves margins quickly. Suppliers with dual-region wafer sourcing absorbed recent trade disruptions far better than single-source competitors [11].    
Author
Author Author Profile Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, automotive technical standards, peer-reviewed engineering journals, industry publications, and authoritative transportation safety organizations. Key sources included the National Highway Traffic Safety Administration (NHTSA) and U.S. Department of Transportation (DOT) databases for TREAD Act compliance data and FMVSS No. 138 standards; European Commission (EC) and United Nations Economic Commission for Europe (UNECE R64/R141) regulations for vehicle type-approval requirements; International Organization for Standardization (ISO) and SAE International technical standards for TPMS performance specifications; International Organization of Motor Vehicle Manufacturers (OICA) for global vehicle production statistics; European Automobile Manufacturers' Association (ACEA), Japan Automobile Manufacturers Association (JAMA), and China Association of Automobile Manufacturers (CAAM) for regional automotive manufacturing data; Insurance Institute for Highway Safety (IIHS) and Euro NCAP for safety impact assessments; National Transportation Safety Board (NTSB) accident investigation reports; International Trade Administration (ITA) automotive trade statistics; World Road Association (PIARC) tire safety studies; and ministry of transport publications from Germany (KBA), UK (DVSA), Japan (MLIT), South Korea (MOLIT), and China (MIIT). These sources were used to collect vehicle production statistics, regulatory mandate timelines, technical performance standards, recall data, aftermarket sales trends, and regional adoption patterns for direct TPMS, indirect TPMS, and hybrid monitoring systems.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. CEOs, CTOs, VPs of automotive electronics, heads of ADAS divisions, and directors of original equipment manufacturer sales from tire pressure monitoring system makers, sensor technology providers, and Tier-1 automotive suppliers were among the supply-side sources. Automotive dealership parts directors, aftermarket diagnostic equipment distributors, commercial managers of tire retailers, chief engineers and purchasing directors of passenger car and commercial vehicle OEMs (including EV manufacturers), and fleet management procurement leads were all part of the demand-side sources. We confirmed product development timelines for next-generation battery-less sensors and IoT-enabled TPMS, validated market segmentation across sensor technologies (direct valve-mounted vs. strap-mounted vs. indirect/ABS-based), and gathered insights on challenges with OEM integration, pricing dynamics between OE-fitment and replacement sensors, and regional regulatory compliance variations. Primary research also confirmed the dates for next-generation battery-less sensors.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others — including Senior Engineers, Fleet Managers, Category Managers (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World — including Latin America, Middle East & Africa (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and vehicle fitment volume analysis. The methodology included:

Identification of 55+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America, encompassing dedicated TPMS manufacturers (Schrader, Pacific Industrial, Huf Group), diversified automotive electronics suppliers (Continental, Bosch, Denso), and aftermarket sensor providers

Product mapping across direct TPMS (valve stem-mounted, strap-mounted, snap-in), indirect TPMS (software-based utilizing ABS wheel speed sensors), and hybrid monitoring systems

Analysis of reported and modeled annual revenues specific to TPMS portfolios, including OEM fitment contracts and aftermarket replacement sensor sales

Coverage of manufacturers representing 75-80% of global TPMS market share in 2024

Extrapolation using bottom-up (global vehicle production volumes by region × TPMS penetration rates × average selling price by channel [OEM vs. Aftermarket]) and top-down (manufacturer revenue validation and tire sensor shipment data cross-verification) approaches to derive segment-specific valuations across passenger cars, light commercial vehicles, and heavy-duty commercial vehicle categories

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















