Organ on chip Market (2026 - 2035)

Organ-on-a-chip Market Research Report: Size, Share, Trend Analysis By Organ Type (Lung-on-Chip, Heart-on-Chip, Liver-on-Chip, Intestine-on-Chip, Kidney-on-Chip, Human-on-Chip), By Applications (Drug Discovery, Toxicology Research, Others) and By End-User (Pharmaceutical Companies, Research Organizations, Others) – Forecast to 2035

Forecast Period
2026-2035
CAGR
28.1%
2025 Market Size
USD 0.37 Billion
2035 Market Size
USD 4.46 Billion
Healthcare ● Updated August 24, 2026 Report ID: MRFR/HC/7026-HCR | Pages: 120 | Author: Nidhi Mandole, Rahul Gotadki

Organ on chip Market Summary

The Organ-on-a-chip Market closed 2025 at roughly USD 0.37 billion and enters its forecast window at USD 0.48 billion in 2026, expanding to USD 4.46 billion by 2035 at a 28.1% CAGR. Two catalysts explain the steepness of that curve. The FDA Modernization Act 2.0 stripped the statutory requirement for animal testing before human trials, and in April 2025 the U.S. Food and Drug Administration published a roadmap to phase out animal studies for monoclonal antibodies in favour of validated non-animal methods [1][2].

Pharmaceutical toxicology has run on rodent studies and static 2D cell culture for six decades, and both are being displaced. Perfused microfluidic devices seeded with primary human cells now reproduce hepatic clearance, cardiac contractility, and alveolar barrier function with far better human translation. The U.S. National Institutes of Health committed to prioritising human-based research platforms across its extramural portfolio in 2025, redirecting a share of a research budget exceeding USD 47 billion [3].

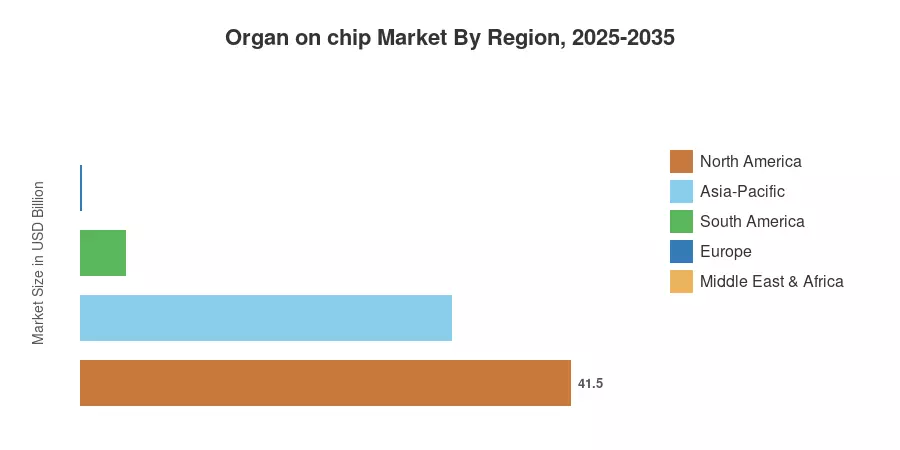
North America holds close to 41.5% of the Organ-on-a-chip Market, anchored by Boston, San Diego, and Research Triangle Park clusters. Asia-Pacific compounds fastest at approximately 31.4%, propelled by Chinese NMPA reform and Japanese AMED funding. Europe ranks second, worth about USD 0.10 billion in 2025, where the European Parliament's 2021 resolution on phasing out animal experimentation continues to shape procurement. The Organ-on-a-chip Market will be defined this decade less by device novelty than by regulatory qualification.


Key Report Takeaways

• By Organ Type

  • Liver chips lead the Organ-on-a-chip Market with an estimated 29.8% revenue share in 2025, reflecting hepatotoxicity's role as the top cause of drug attrition.
  • Multi-organ and body-on-chip configurations post the fastest trajectory at roughly 33.6% CAGR through 2035

• By Application

  • Drug discovery and lead identification accounted for approximately USD 0.14 billion in 2025
  • Toxicology and safety assessment expands at close to 30.2% CAGR as regulators formalise acceptance criteria.
  • Disease modelling holds roughly 18.4% share, driven by rare-disease and oncology programmes.

• By End User

  • Pharmaceutical and biotechnology companies represent about 56.2% of demand
  • Contract research organisations grow at an estimated 32.1% CAGR as sponsors outsource assay execution

• By Region

  • North America dominates the Organ-on-a-chip Market at 41.5% share in 2025
  • Asia-Pacific delivers the steepest regional CAGR at roughly 31.4%
  • Europe contributed close to USD 0.10 billion in 2025


Market Size and Forecast (2021–2035)

Figures below blend bottom-up instrument and consumable revenue from more than 40 platform vendors with top-down validation against pharmaceutical R&D budget disclosures, public grant awards, and customs data on microfabricated polymer devices. Historical years reflect audited or reported revenue; forecast years apply the calibrated growth rate for the Organ-on-a-chip Market.
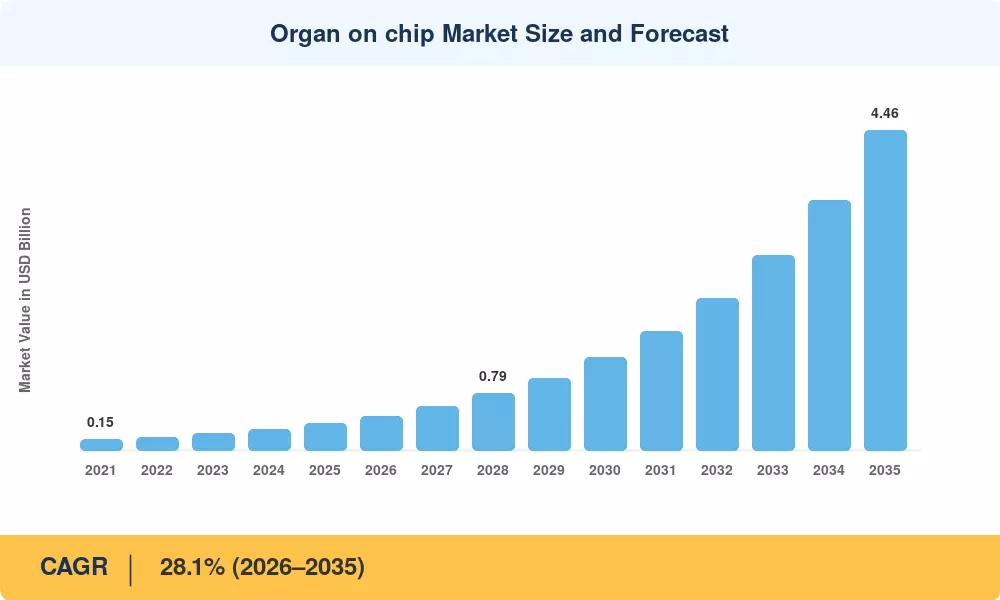
Organ on chip Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory phase-out of mandatory animal testing 7.4 North America, Europe Short-term (≤2 yr)
Clinical trial attrition costs 6.1 Global Medium-term (2–4 yr)
Public research funding for human-based models 4.8 North America, Europe, Japan Short-term (≤2 yr)
Rare disease and oncology precision programmes 3.9 North America, Europe Long-term (≥4 yr)
Cost pressure on preclinical budgets 3.3 Global Medium-term (2–4 yr)
iPSC supply chain maturation 2.7 Asia-Pacific, North America Long-term (≥4 yr)
Cosmetics and chemical testing bans 2.1 Europe, Asia-Pacific Medium-term (2–4 yr)


Regulatory Reform Converts Optional Science into Budgeted Line Items

Nothing moves a procurement committee like a statute. The FDA Modernization Act 2.0 removed the animal-testing mandate in December 2022, and the agency's April 2025 roadmap set a phased timeline beginning with monoclonal antibodies [1][2]. Sponsors that treated chip data as supplementary now file it as primary evidence. Market Research Future estimates this single shift accounts for roughly a quarter of near-term demand growth across the Organ-on-a-chip Market, with the largest response among the twenty pharmaceutical companies that together spend over USD 145 billion annually on R&D [7].

Attrition Economics Make the Business Case

Roughly nine in ten drug candidates entering human trials fail, and hepatotoxicity plus cardiotoxicity remain leading causes [7][11]. A Phase I failure costs a sponsor tens of millions; a liver chip screen costs a fraction of that. Wyss Institute researchers reported that a liver-chip panel correctly flagged the majority of drugs known to cause clinical liver injury that had passed conventional animal screening [11]. That predictive delta is the argument that closes deals.

Public Funding Builds the Validation Infrastructure

NCATS has funded tissue chip consortia continuously since 2012, and the 2024–2025 expansion added disease-specific programmes and a translational validation centre [6]. Europe's Horizon Europe cluster allocated substantial support to non-animal methods under its health pillar [12]. Public money here buys something private capital will not: comparative reference datasets that let regulators judge whether a device performs.

Cell Sourcing Stops Being the Bottleneck

Chips are only as good as the cells inside them. Commercial iPSC-derived hepatocyte, cardiomyocyte, and endothelial supply has broadened materially, with Japanese and Korean suppliers scaling GMP-grade lines [9]. Lot-to-lot variability has narrowed, which directly improves assay reproducibility — historically the loudest objection from toxicology directors.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Absence of harmonised validation standards 5.6 Global Medium-term (2–4 yr)
High cost per data point versus 2D culture 4.2 Asia-Pacific, South America Short-term (≤2 yr)
Low throughput relative to screening cascades 3.5 Global Medium-term (2–4 yr)
Shortage of trained microfluidics operators 2.8 Global Long-term (≥4 yr)
Vendor lock-in on proprietary consumables 2.0 North America, Europe Long-term (≥4 yr)


Validation Standards Remain Unfinished

Regulators will accept what they can reproduce. No binding OECD test guideline yet covers perfused organ chips, though a working programme on new approach methodologies is advancing [13][10]. Sponsors consequently run chip assays alongside legacy studies rather than instead of them, doubling cost. Until qualification criteria are published, a meaningful share of Organ-on-a-chip Market demand stays in the exploratory budget rather than the regulatory-submission budget.

Unit Economics Still Favour Legacy Assays

A single perfused device containing primary human cells, medium and operator time can be two orders of magnitude more expensive per data point than a 96-well plate [14]. If you’re doing hit-to-lead screening on thousands of compounds, that’s a deal breaker. Thus adoption targets the lead-optimisation and candidate-selection phases where compound quantities are low, and decision value is high.


Talent Scarcity Slows Deployment

Operating these platforms takes a combination of cell biology and fluidics engineering that few labs natively staff. The adopters surveyed say it takes many months before they can generate decision-grade data [15]. That latency drives mid-sized biotechs away from capital purchases and toward service models.


Organ on chip Market Opportunities

Regulatory Qualification as a Commercial Moat

The first vendor to obtain a formal qualification of a given chip-based context of use will turn a scientific claim into a procurement need. Sponsors don’t buy prospective approaches; they buy proven methods. Companies investing now in comparative reference datasets will be positioned to take a disproportionate share of the Organ-on-a-chip Market when acceptance criteria are published.


Emerging Market Capacity Build-Out

India and China are building preclinical CRO capability for Western sponsors, and both countries are under fire to deliver client-side non-animal expectations. In 2023, India’s Central Drugs Standard Control Organization revised its regulations to allow for non-animal approaches, thereby establishing a procurement corridor in a cost-sensitive location [17]. The simplest route is vendors selling cheaper plate-format devices rather than instrument-heavy systems.


Data Monetisation and Reference Library Licensing

Every chip run generates a compound-response record. Aggregated across customers and anonymised, those records become a predictive reference library — an asset that appreciates with use. Several platform companies now license access to historical toxicity datasets as a recurring-revenue product alongside hardware, mirroring the shift that reshaped genomics tooling [16].

Multi-Organ Coupling for ADME Prediction

Linking liver, intestine, and kidney compartments enables absorption, distribution, metabolism, and excretion prediction that no single chip delivers. This is where the Organ-on-a-chip Market moves from safety flagging to quantitative pharmacokinetics, a far larger budget pool.

Chemical and Cosmetics Testing Beyond Pharma

The EU cosmetics animal-testing ban and subsequent REACH pressure created demand from consumer goods and agrochemical firms with no legacy investment in rodent facilities [10]. These buyers adopt faster because they are not defending sunk costs.


Organ on chip Market Future Outlook

Machine Learning Turns Chip Data into Predictive Models

Chips generate rich, sparse datasets — exactly the input that supervised models need and rarely get from animal studies. Vendors are pairing devices with trained toxicity predictors so that a chip run refines a model rather than merely producing a result. By 2032, Market Research Future expects a majority of Organ-on-a-chip Market revenue to attach to platforms bundling analytical software, shifting margin away from hardware.

Service Economics Overtake Instrument Sales

Buyers want answers, not equipment. Contract research organisations are absorbing the operational burden, and the fee-per-study model removes the capital approval hurdle that stalls instrument purchases at mid-sized biotechs. Expect service revenue to approach parity with product revenue before 2030.

Standardisation Arrives, and Consolidates the Field

When OECD or ICH guidance lands, it will reference specific performance criteria, and platforms that fail them will exit [13]. Standardisation is usually described as an enabler; it is equally a filter. Analysts expect the vendor count to contract even as revenue quadruples.

Patient-Specific Chips Enter Clinical Decision-Making

Seeding a device with a patient's own cells to select therapy is technically demonstrated and commercially unproven. Oncology is the wedge, where tumour-derived organoid-on-chip screening could inform regimen choice. If reimbursement follows, the Organ-on-a-chip Market gains a clinical revenue stream entirely separate from pharmaceutical R&D budgets [20].


Organ on chip Market Segmentation

Segmentation of the Organ-on-a-chip Market follows organ type, application, and end user, each of which behaves differently under regulatory and budget pressure.

By Organ Type

The Organ-on-a-chip Market remains anchored by hepatic models, though multi-organ systems are closing the gap.

Segment Metric (2025) Primary Demand Driver
Liver 29.8% share Hepatotoxicity screening in candidate selection
Heart USD 0.068 Billion Cardiac safety and QT liability assessment
Lung 15.6% share Inhaled therapeutics and infection modelling
Kidney 11.2% share Nephrotoxicity and transporter studies
Intestine 9.4% share Oral bioavailability prediction
Other Organ Types 33.6% CAGR Multi-organ coupling and body-on-chip research


Liver dominance is not an accident of research fashion — drug-induced liver injury is the single most common reason a compound is withdrawn after approval, so it is the risk sponsors pay most to retire early [11]. Cardiac chips follow closely because ICH E14/S7B guidance already frames proarrhythmia assessment in terms sponsors can map onto contractility and field-potential readouts, making the regulatory conversation easier to start.

By Application

Application mix within the Organ-on-a-chip Market is shifting from discovery support toward regulated safety work.

Segment Metric (2025) Primary Demand Driver
Drug Discovery and Lead Identification USD 0.14 Billion Candidate triage before IND-enabling work
Toxicology and Safety Assessment 30.2% CAGR Regulatory acceptance of non-animal evidence
Disease Modelling 18.4% share Rare disease and oncology target validation
Personalized Medicine 8.9% share Patient-derived cell screening pilots
Other Applications 6.2% share Cosmetics, agrochemical, and defence testing


Discovery remains the largest application because it carries the lowest evidentiary burden — no regulator needs to approve an internal triage decision. Toxicology grows faster precisely because that burden is now being defined, and each published qualification converts a research budget into a compliance budget, which is stickier and larger.

By End User

End-user composition in the Organ-on-a-chip Market is tilting toward outsourced execution.

Segment Metric (2025) Primary Demand Driver
Pharmaceutical and Biotechnology Companies 56.2% share Internal preclinical decision-making
Academic and Research Institutes 24.1% share Grant-funded method development
Contract Research Organizations 32.1% CAGR Sponsor demand for turnkey study delivery
Other End Users 5.3% share Cosmetics, chemicals, government laboratories


Pharmaceutical buyers dominate spend, but academic institutions dominate publication output, and that asymmetry matters: peer-reviewed validation from university laboratories is what persuades industry safety committees. Contract research organisations are the swing factor, converting a capital purchase into an operating expense and thereby reaching the long tail of small biotechs.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 41.5% share Regulatory qualification, biotech cluster adoption
Europe USD 0.10 Billion Animal-testing phase-out, Horizon Europe consortia
Asia-Pacific 31.4% CAGR (2026–2035) CRO capacity, iPSC supply, NMPA reform
South America 3.8% share Academic pilots, regional CRO upgrades
Middle East & Africa USD 0.012 Billion Sovereign biotech funds, university programmes
Total 100.0%

Regional distribution across the Organ-on-a-chip Market tracks where regulatory reform and pharmaceutical R&D concentration overlap.


North America

Country Metric Key Driver
US 87.4% of region FDA roadmap and NIH funding
Canada USD 0.013 Billion CIHR translational grants
Mexico 24.6% CAGR Contract manufacturing spillover


Boston and the Bay Area account for the majority of U.S. installed base, because that is where the buyers sit. The FDA's own National Center for Toxicological Research operates evaluation programmes on these platforms, which gives sponsors confidence that submitted data will be read competently [2]. Canada's contribution is smaller but concentrated in Toronto and Montreal academic centres. Regional leadership of the Organ-on-a-chip Market is unlikely to change before 2035.

Europe

Country Metric Key Driver
Germany 24.8% of region Pharma R&D density, Fraunhofer programmes
UK USD 0.021 Billion NC3Rs funding and CRO base
France 15.2% of region INSERM translational networks
Italy 8.6% of region Academic consortium participation
Spain 7.1% of region Regional biotech clusters
Nordic Countries 29.3% CAGR Life-science infrastructure investment
Russia 2.4% of region Limited import access
Rest of Europe 10.6% of region Benelux and Swiss platform vendors


The European Parliament's 2021 resolution calling for a coordinated phase-out of animal experimentation set direction that national funders followed [12]. The Netherlands has been most explicit, with its transition programme targeting reduced reliance on animal procedures, and Dutch vendors hold outsized share relative to national R&D spend. Switzerland's pharmaceutical majors are among the largest single buyers on the continent.

Asia-Pacific

Country Metric Key Driver
China 38.9% of region NMPA reform, domestic CRO scale
India 34.2% CAGR CDSCO rule amendment, cost advantage
Japan USD 0.019 Billion AMED funding, pharma majors
South Korea 11.4% of region MFDS alignment, iPSC manufacturing
ASEAN 6.8% of region Singapore ASTAR programmes
Rest of Asia-Pacific 4.3% of region Australian academic adoption


China's preclinical CRO sector serves global sponsors, and those sponsors increasingly specify non-animal endpoints in statements of work — which pulls adoption regardless of domestic regulation. India's 2023 amendment permitting non-animal methods under its drug rules removed a legal obstacle rather than creating demand, but demand was already there [17]. Asia-Pacific will contribute the largest incremental dollar addition to the Organ-on-a-chip Market after North America across the forecast window.

South America

Country Metric Key Driver
Brazil 61.3% of region ANVISA alternative methods recognition
Argentina 18.7% of region University research programmes
Rest of South America 20.0% of region Chilean and Colombian pilots


Brazil's national council on animal experimentation has formally recognised a set of alternative methods, giving local laboratories a defensible basis for adoption [18]. Budget constraints mean uptake favours consumable-light plate formats over perfusion instruments. Growth is real but from a base small enough that regional share stays under 4% through the decade.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 33.8% of region Vision 2030 biotech strategy
UAE 26.4% of region Research free-zone investment
South Africa 19.1% of region Established academic pharmacology base
Egypt 9.7% of region Generic manufacturer testing needs
Rest of MEA 11.0% of region Israeli platform development


Saudi Arabia's National Biotechnology Strategy targets localisation of biopharmaceutical capability by 2030, and sovereign-funded research institutes have begun equipping laboratories accordingly [19]. Israel contributes disproportionate technical output relative to purchase volume. The region remains a rounding error commercially, but the installed base being built now determines who wins contracts in the 2030s.


Organ on chip Market By Region, 2025-2035

Competitive Benchmarking

The Organ-on-a-chip Market is moderately concentrated, with an estimated HHI in the 900–1,100 band and a top-five combined share near 46%. No vendor commands pricing power across organ types; instead, specialists dominate individual niches — one company owns liver, another owns vascularised tissue, a third owns neural. Consolidation pressure is building as standardisation approaches.

Company Est. Revenue Share Range Key Offerings for Organ-on-a-chip Market Strategic Positioning
Emulate, Inc. ~13–16% Liver-Chip, Intestine-Chip, Zoë culture module Regulatory validation leader; deepest FDA engagement
CN Bio Innovations ~9–12% PhysioMimix single- and multi-organ systems Strong ADME and multi-organ coupling focus
MIMETAS ~7–10% OrganoPlate plate-based platform Throughput-oriented; pumpless design lowers cost
TissUse GmbH ~5–8% HUMIMIC multi-organ chip series European leader in systemic co-culture
InSphero AG ~4–7% 3D InSight microtissue and liver platforms Metabolic disease and toxicology specialist
Hesperos, Inc. ~4–6% Human-on-a-Chip functional readout systems Rare disease and neuromuscular niche
Nortis, Inc. ~3–5% ParVivo perfusion systems Vascularised and kidney tissue focus
AxoSim, Inc. ~3–5% Nerve-on-a-Chip, brain organoid services Neurology-dedicated service model
AlveoliX AG ~2–4% AX Lung-on-Chip system Respiratory and barrier-function specialist
BiomimX S.r.l. ~2–4% uBeat mechanically stimulated chips Cardiac and joint disease modelling
SynVivo, Inc. ~2–4% Idealised microvascular network chips Blood-brain barrier and vascular assays
Draper Laboratory ~2–3% PREDICT96 high-throughput platform Government-funded programme heritage


Recent News & Developments

  • U.S. Food and Drug Administration (April 2025): Published a roadmap to reduce and eventually replace animal testing for monoclonal antibodies, naming organ chips among acceptable alternative approaches — the clearest regulatory signal to date [2]
  • National Institutes of Health (April 2025): Announced a policy shift to prioritise human-based research technologies across new funding solicitations, affecting a multi-billion-dollar extramural portfolio [3]
  • Emulate, Inc. (September 2024): Expanded its liver-chip validation dataset in collaboration with multiple pharmaceutical sponsors, strengthening the case for regulatory qualification [11]
  • CN Bio Innovations (June 2024): Launched an extended multi-organ configuration of PhysioMimix targeting quantitative ADME workflows [16]
  • MIMETAS (March 2024): Announced a strategic partnership with a top-ten pharmaceutical company covering kidney and liver screening programmes [16]
  • Central Drugs Standard Control Organisation, India (2023): Amended the New Drugs and Clinical Trials Rules to permit non-animal testing methods for drug safety evaluation [17]
  • OECD (2024): Advanced its work programme on new approach methodologies, initiating scoping for perfused tissue-model guidance [13]
  • Valo Health / Tara Biosystems (2023–2024): Integrated cardiac tissue platform capability into a computational drug discovery pipeline, illustrating consolidation between chip hardware and AI-driven discovery [20]


Organ on chip Market Report Scope

Parameter Detail
Market Scope Global Organ-on-a-chip Market — instruments, consumables, software, and services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 28.1% (2026–2035)
Market Size Checkpoints USD 0.37 Billion (2025); USD 0.48 Billion (2026); USD 4.46 Billion (2035)
Fastest Growing Segments Multi-organ / Other Organ Types; Toxicology and Safety Assessment; Contract Research Organizations
Companies Profiled 12 major vendors including Emulate, CN Bio Innovations, MIMETAS, TissUse, InSphero, Hesperos, Nortis, AxoSim, AlveoliX, BiomimX, SynVivo, Draper
Valuation Currency USD (constant 2025 dollars)

FAQs

How should a buyer evaluate vendors in the Organ-on-a-chip Market?
Ask for the comparative reference dataset, not the brochure. Vendors that can show blinded performance against known clinical outcomes are qualitatively different from those showing pretty images [11].
What validation burden falls on the customer rather than the vendor?
The customer owns context-of-use validation for their specific compound class. Vendors supply platform performance data; sponsors must still demonstrate fitness for their own decision [13].
Is buying instruments or outsourcing the better entry into the Organ-on-a-chip Market?
Outsource first. Fee-per-study contracts avoid capital approval and reveal whether the data actually changes internal decisions before you commit to infrastructure.
How do organ chips compare with organoids?
Organoids self-organise and capture tissue architecture; chips add perfusion, mechanical cues, and controlled interfaces. Increasingly, vendors combine both — organoids seeded inside perfused devices [5].
What drives total cost of ownership in the Organ-on-a-chip Market?
Consumables and cells, not the instrument. Recurring device and media spend typically exceeds the capital outlay within two years of routine operation [14].
Are data outputs portable between platforms?
Rarely. Proprietary file formats and vendor-specific readouts make cross-platform comparison difficult, which is why standardisation work matters commercially as much as scientifically [13].
Will regulators outside the United States accept chip-derived evidence?
The European Medicines Agency and Japan's PMDA both engage on non-animal methods through innovation pathways, though neither has issued binding acceptance criteria. Early scientific advice meetings are advisable [8].    
Author
Author
Author Profile
Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach

Research Methodology on Organ on Chip Market

Introduction

Organ-on-Chip (OoC) technology is an innovative technology that is revolutionizing the biomedical research field. It involves the creation of miniature lab-on-chip systems containing living cells, micro-channels, sensors, actuators and other related components. It has enabled researchers to bypass the traditional bottlenecks associated with animal studies, enabling them to develop more effective drugs that have a higher rate of success and faster results than conventional drug development studies. This technology has also enabled researchers to simulate more complex human physiology more accurately, which in turn has allowed the development of personalized medicines and treatments.

The purpose of this research project is to understand the current market size of the Organ-on-Chip technology, identify the key products in the market, determine the future growth of the technology, and assess the market potential of the technology.

Research Objectives

  • To analyze the market size of the Organ-on-Chip technology.
  • To identify key players in the Organ-on-Chip technology market.
  • To understand the growth potential of the technology.
  • To identify threats and opportunities in the Organ-on-Chip technology market.

Research Questions

  • What is the current market size of the Organ-on-Chip technology?
  • Who are the leading players in the Organ-on-Chip technology market?
  • What is the growth potential of Organ-on-Chip technology?
  • What are the threats and opportunities in the Organ-on-Chip technology market?

Research Approach

This research will employ descriptive, as well as exploratory research approaches in order to gain an in-depth understanding of the Organ-on-Chip technology market. Descriptive research is used to analyze the size and scope of the current Organ-on-Chip technology market and identify the key players in the industry. Exploratory research is employed to gain a better understanding of the growth potential of the technology, as well as identify the threats and opportunities present in the market.

Research Design

The research employs both qualitative and quantitative research designs. The qualitative design involves semi-structured interviews with key industry experts and stakeholders, as well as analyzing secondary sources including reports, industry white papers, and other available data. The quantitative design involves surveys and polls, as well as analysis of the data, gathered through qualitative research.

Sampling & Data Collection

The sample size for the research will be 1000 respondents, strategically chosen to provide a comprehensive overview of the Organ-on-Chip technology market. The sample includes representatives from key sectors of the industry, such as manufacturers of technology, agricultural and pharmaceutical companies, research institutions, government agencies, as well as other stakeholders. The data is collected using both primary and secondary methods. Primary methods include surveys and face-to-face interviews, while secondary methods involve analysis of available published documents, industry reports, and other available data.

Data Analysis

The collected data is analyzed using both quantitative and qualitative methods. Quantitative data analysis tools such as SPSS and Excel are utilized to analyze the collected data statistically and to generate results from the surveys and polls. Qualitative data analysis methods, such as content analysis and thematic analysis, are used to analyze the interviews conducted with experts and stakeholders.

Conclusion

The organ-on-chip technology market has enormous potential and could revolutionize the research and drug development sector. This research provides an in-depth understanding of the current market size and scope, the key players in the industry, the potential growth of the technology, as well as the threats and opportunities present in the market. The findings of this research prove to be beneficial for key stakeholders in the industry.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















