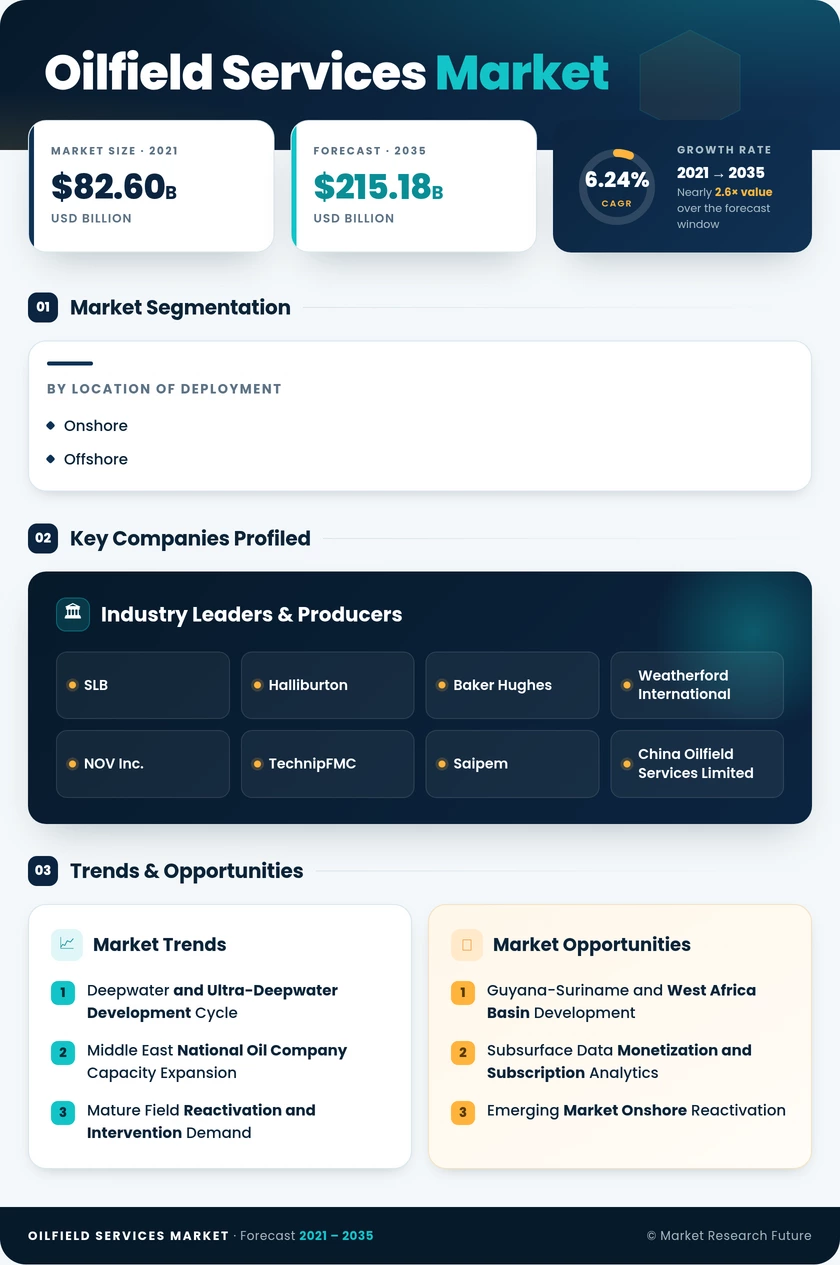
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Location Of Deployment | Onshore; Offshore | Onshore (63.5% share, 2025) | Offshore (6.9% CAGR, 2026–2035) |
Market Segmentation Overview
By Location Of Deployment
| Sub-Segment | Key Trend |
| Onshore | Longer laterals and higher completion intensity raise service content per well even as rig counts fall; Middle East conventional programmes provide volume-committed multi-year demand |
| Offshore | Deepwater sanctioning at a decade high combined with permanent floater retirements sustains firm day rates and long contract tenure through the 2030s |
Onshore leads on revenue because well counts are far higher and because Gulf-region conventional drilling — including ADNOC's roughly 40% activity expansion — sits almost entirely on land, giving contractors volume-committed backlog that spot work cannot match. Offshore grows faster despite the smaller base, since each deepwater well consumes several times the service content of an onshore equivalent and floater scarcity keeps pricing firm. The divergence is a pricing story rather than an activity story: onshore contractors in North America face persistent deflation from oversupplied pressure-pumping capacity, while offshore providers have repriced upward against tight rig availability. Contractors weighted toward Brazil, Guyana and West Africa have therefore shown better margin resilience than those anchored to US land.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA