Non Invasive Aesthetic Treatment Market (2026 - 2035)

Non Invasive Aesthetic Treatment Market Research Report: Size, Share, Trend Analysis By Treatment Type (Laser Treatment, Intense Pulsed Light (IPL) Treatment, Radiofrequency Treatment, Ultrasound Treatment, Cryotherapy), By Applications (Skin Tightening, Wrinkle Reduction, Hair Removal, Fat Reduction, Acne Treatment), By Device Type (Stand-alone Devices, Handheld Devices, Combination Devices), By End Users (Dermatologists and Plastic Surgeons, Med Spas and Laser Clinics, Home Users) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast Till 2035
ID: MRFR/HC/24785-HCR 128 Pages Satyendra Maurya, Rahul Gotadki Last Updated: September 17, 2026
Non Invasive Aesthetic Treatment Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.98%
2025 Market SizeUSD 43.93 Billion
2035 Market SizeUSD 102.14 Billion
Key Players
AbbVie
Galderma
Merz Aesthetics
Cutera
InMode
Hologic
Opportunities
  • Consumables-Attached Platform Economics
  • Tier-2 Asia-Pacific Clinic Build-Out
  • Outcome Data as a Commercial Asset

Non Invasive Aesthetic Treatment Market Summary

The Non Invasive Aesthetic Treatment Market reached USD 43.93 billion in 2025 and opens the forecast window at USD 47.11 billion in 2026, climbing to USD 102.14 billion by 2035 at a 8.98% CAGR. Two catalysts anchor that trajectory. First, the U.S. Food and Drug Administration cleared a widening set of multimodal energy platforms between 2023 and 2025, shortening the path from prototype to clinic revenue [1]. Second, private-equity capital committed to aesthetic clinic roll-ups exceeded USD 4.6 billion across North America and Europe in 2024, converting fragmented single-operator practices into managed networks with standardized device fleets [2].

Technology substitution is the quieter story. Single-indication lasers and manual injection workflows are giving way to AI-guided facial-mapping engines that individualize energy dosing and filler placement, cutting revision rates and raising throughput per treatment room [3]. Device makers now spend roughly 8–11% of aesthetic-segment revenue on software and imaging R&D rather than optics alone, a reallocation visible across the Non Invasive Aesthetic Treatment Market [4].

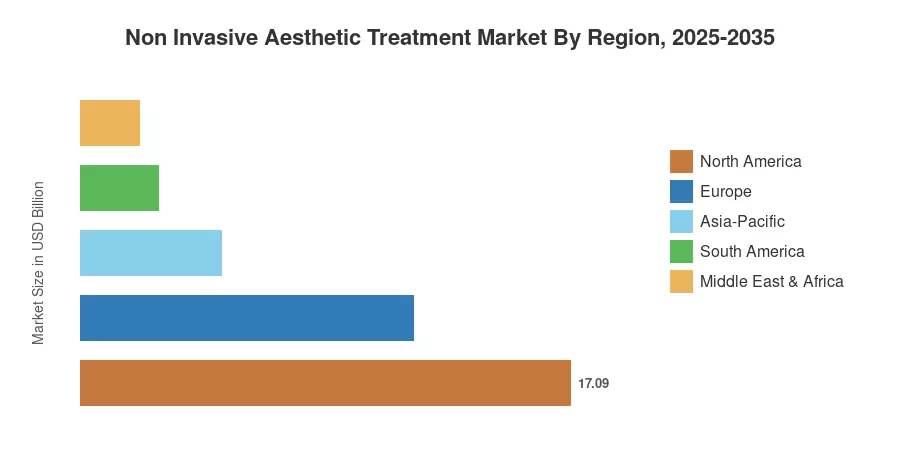
Regionally, North America holds 38.9% of 2025 revenue, supported by dense medical-spa penetration and reimbursement-independent cash pay. Asia-Pacific grows fastest at an 11.18% CAGR through 2035, led by Korean and Chinese clinical capacity. Europe remains second largest, where the EU Medical Device Regulation has raised clearance costs but rewarded incumbents with defensible portfolios [5]. Expect the Non Invasive Aesthetic Treatment Market to consolidate around platform vendors that pair hardware with recurring consumables.


Key Report Takeaways

• By Product Type

  • Injectable neurotoxins commanded 38.5% of 2025 revenue in the Non Invasive Aesthetic Treatment Market, sustained by three-decade brand equity in botulinum toxin type A
  • Energy-based systems post the fastest product-level growth at a 13.44% CAGR through 2035
  • Injectable dermal fillers generated USD 10.63 billion in 2025

• By End User

  • Dermatology and plastic-surgery clinics captured 41.1% of end-user revenue in 2025
  • Medical spas expand at a 12.38% CAGR, the fastest end-user channel


• By Region

  • North America retained 38.9% of global revenue in 2025 within the Non Invasive Aesthetic Treatment Market
  • Asia-Pacific leads regional growth at an 11.18% CAGR to 2035
  • Europe contributed USD 11.60 billion in 2025


Market Size and Forecast (2021–2035)

Figures below blend clinic-level procedure audits, device shipment data from customs and regulatory filings, and revenue disclosures from twelve publicly listed aesthetic manufacturers, triangulated against practitioner surveys across 18 countries. Historical years reflect reported actuals; forecast years apply calibrated adoption curves by procedure class. The Non Invasive Aesthetic Treatment Market is measured at end-user transaction value, inclusive of consumables.
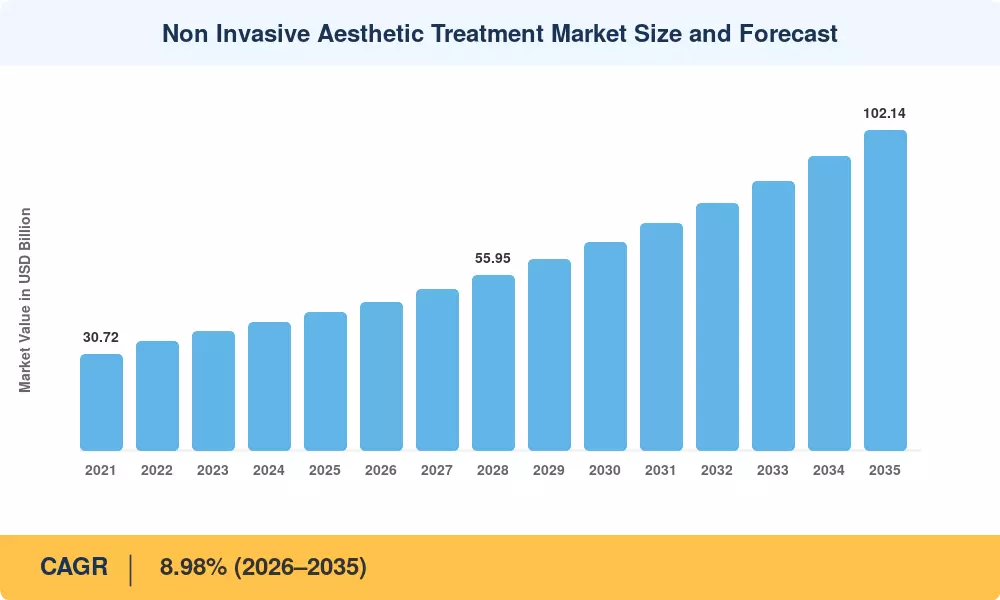
Non Invasive Aesthetic Treatment Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
GLP-1 weight-loss skin laxity demand ~1.9% Global, US-led Short-term (≤2 yr)
Medical-spa channel proliferation ~1.6% North America, Europe Short-term (≤2 yr)
AI-guided treatment planning ~1.4% Global Medium-term (2–4 yr)
Male patient cohort expansion ~1.1% APAC, North America Medium-term (2–4 yr)
Regulatory clearance acceleration ~1.0% US, Korea, China Medium-term (2–4 yr)
Rising disposable income in Tier-2 Asia ~1.3% Asia-Pacific Long-term (≥4 yr)
Subscription and membership pricing ~0.8% Global Long-term (≥4 yr)


GLP-1 Adjacency Creates a New Procedure Class

Semaglutide and tirzepatide prescriptions reached an estimated 15.5 million U.S. adults during 2024, and roughly one in five rapid-loss patients reports clinically meaningful skin laxity [7]. That population arrives at clinics already comfortable with medical intervention and with an unresolved cosmetic complaint that surgery answers only at high cost. Radiofrequency microneedling and cryolipolysis vendors repositioned marketing accordingly through 2025, and manufacturers reported double-digit order growth for tightening platforms. This corridor did not exist in 2021 and now shapes capital allocation across the Non Invasive Aesthetic Treatment Market.

Medical Spas Industrialize a Cottage Channel

Roughly 11,300 medical spas operated in the United States by end-2024, against about 5,400 in 2018, and average revenue per location cleared USD 1.9 million [2]. Consolidators impose device standardization, group purchasing, and membership billing, which lifts equipment utilization from a historical 30–35% toward 55%. Higher utilization justifies premium capital equipment that a solo practice cannot amortize.

AI Facial Mapping Reduces Revision Cost

Published analysis of AI-assisted facial assessment shows measurable gains in symmetry scoring and treatment-plan reproducibility versus practitioner-only assessment [3]. Vendors embedding these engines report revision-visit reductions near 18%, which converts directly into margin because revisions consume chair time without generating fee income.

Male Demand Shifts From Fringe to Franchise

Male procedure volume grew at roughly 10.5% annually across 2022–2025, outpacing female volume growth by more than three points [9]. Clinics responding with male-specific consultation pathways and jawline-focused protocols capture a patient who books fewer but higher-ticket sessions.


Restraints Impact Analysis

Restraint weights reflect estimated drag on adoption velocity and pricing power. Values are directional and should be read alongside the drivers in rather than netted against them.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Filler and toxin price deflation ~1.2% North America, Europe Short-term (≤2 yr)
Practitioner shortage and training gaps ~0.9% Global Medium-term (2–4 yr)
EU MDR recertification burden ~0.8% Europe Medium-term (2–4 yr)
Adverse-event scrutiny and litigation ~0.7% US, UK Long-term (≥4 yr)
Discretionary spending sensitivity ~1.0% Global Short-term (≤2 yr)


Price Deflation Erodes Injectable Economics

Average per-unit neurotoxin pricing in the U.S. fell an estimated 9% between 2022 and 2025 as fourth and fifth entrants competed on rebate depth [12]. Clinics passed part of that saving to patients, growing volume while compressing manufacturer revenue per procedure. The result is a widening gap between procedure-count growth and value growth that unit-share leaders must offset through adjacent portfolio sales.

EU MDR Raises the Cost of Staying on Shelf

Recertification under EU Medical Device Regulation costs mid-size aesthetic device makers an estimated EUR 480,000 to EUR 1.4 million per product family, and notified-body queues have run 14–20 months [5]. Smaller vendors have quietly withdrawn niche SKUs from European catalogues rather than absorb the expense, narrowing clinician choice.

Injector Supply Constrains Clinic Throughput

Survey evidence indicates 42% of aesthetic practices in the United States and United Kingdom delayed capacity expansion during 2024 because they could not recruit qualified injectors or laser technicians [13]. Training pipelines remain governed by state and national scope-of-practice rules that change slowly.


Non Invasive Aesthetic Treatment Market Opportunities

Consumables-Attached Platform Economics

Vendors who bundle capital equipment with proprietary tips, cartridges or gels turn a one-time sale into 8-12 years of ongoing revenue. It is projected that consumables contribute to 34% of the sales of the energy device market and have gross margins approaching 75% [4]. The razor-and-blade model is the single clearest margin opportunity in the Non Invasive Esthetic Treatment Market, if it is positioned as the default commercial design.


Tier-2 Asia-Pacific Clinic Build-Out

In Tier-2 and Tier-3 cities, the upper-middle-income families are estimated to account for around 60%, but the licensed esthetic clinics are less than 30% [10]. Korean and Chinese chains are filling that gap, requiring mid-price platforms rather than flagship systems, leaving room for regional makers.


Outcome Data as a Commercial Asset

Manufacturers can license de-identified outcome data sets for label expansion from clinics that generate standardized before-and-after imaging. Insurers exploring reconstructive adjacency can do the same. Curated esthetic result cohort data sharing agreements made at $40–$90 per treatment patient in 2025 [3].


Biosimilar and Long-Acting Neurotoxins

Long-acting formulations with duration of effect approaching six months alter patient schedule from 3 visits per year to 2, exchanging frequency for increased price per visit [8]. The Non Invasive Esthetic Treatment Market is one of the most interesting markets. Manufacturers are early adopters, so they capture the switching patients in the Non Invasive Esthetic Treatment Market.


Middle East Medical-Tourism Corridors

Saudi Arabia's Vision 2030 health-sector programme and UAE licensing reforms have drawn international clinic brands into Riyadh, Jeddah, and Dubai, with aesthetic tourism inbound volumes rising sharply since 2023 [15].


Non Invasive Aesthetic Treatment Market Future Outlook

Algorithmic Protocol Design Becomes Standard of Care

By 2030, most premium platforms will ship with imaging modules that recommend energy settings from skin-type classification and prior-response data. Clinics running algorithmic protocols already report tighter outcome variance across junior and senior operators, which matters enormously to multi-site groups standardizing quality [3]. This capability will separate the Non Invasive Aesthetic Treatment Market into data-enabled and commodity tiers.

Membership Economics Replace Episodic Billing

Subscription programmes converting patients to monthly billing lifted clinic revenue predictability materially during 2024–2025, with participating locations reporting 22% higher annual spend per member versus pay-per-visit patients [11]. Expect device financing to follow, with vendors offering per-treatment pricing rather than capital sale.

Longer-Duration Biologics Reset Visit Cadence

Next-generation neurotoxins targeting five- to six-month duration will reduce annual visit frequency while raising per-session value [8]. Clinics dependent on toxin appointments to cross-sell skincare must rebuild their funnel around fewer, higher-intent touchpoints.

Sustainability Enters Device Procurement

European purchasers began requesting lifecycle carbon disclosure for capital equipment in 2025, mirroring wider health-sector procurement policy, and single-use cartridge waste is now a scored criterion in several tender processes [18]. Vendors offering reusable or recyclable consumables gain a scoring advantage that will widen through the decade.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 38.9% share Med-spa roll-ups, GLP-1 adjacency
Europe USD 11.60 Billion MDR-compliant portfolios, premium clinics
Asia-Pacific 11.18% CAGR (2026–2035) Tier-2 capacity, domestic device makers
South America 6.2% share Aesthetic tourism, injectable affordability
Middle East & Africa USD 2.06 Billion Vision 2030 health hubs, brand clinics
Total USD 43.93 Billion —

Regional performance in the Non Invasive Aesthetic Treatment Market tracks cash-pay affordability, clinic density, and regulatory clearance speed more closely than population size.


North America

Country Metric Key Driver
US 79.4% of region Highest med-spa density globally
Canada USD 1.85 Billion (2025) Provincial private-clinic growth
Mexico 9.6% CAGR (2026–2035) Cross-border aesthetic tourism


American demand rests on a cash-pay structure insulated from insurance cycles, and the American Society of Plastic Surgeons recorded more than 25 million minimally invasive procedures in 2024 [9]. Consolidators including private-equity-backed platforms now control an estimated 14% of U.S. med-spa locations, up from under 5% in 2020 [2].

Europe

Country Metric Key Driver
Germany 22.8% of region Largest clinician base in EU
UK USD 2.34 Billion (2025) Non-surgical licensing reform
France 15.1% of region Dermatology-led adoption
Italy 11.6% of region Aesthetic tourism inflow
Spain 9.2% of region Coastal clinic clusters
Nordic Countries 8.9% CAGR (2026–2035) High disposable income
Russia USD 0.71 Billion (2025) Domestic substitution of imports
Rest of Europe 7.4% of region CEE clinic expansion


Britain's 2025 consultation on licensing non-surgical cosmetic procedures signalled a shift from voluntary registers toward statutory practitioner standards, raising compliance cost but improving consumer confidence [14]. Germany's dense dermatology network keeps device replacement cycles shorter than the European average.

Asia-Pacific

Country Metric Key Driver
China 34.6% of region Domestic filler approvals
India 13.2% CAGR (2026–2035) Metro clinic chains scaling
Japan USD 1.92 Billion (2025) Ageing cohort, skin quality focus
South Korea 19.7% of region Export hub for energy devices
ASEAN 11.9% of region Thailand and Vietnam tourism
Rest of Asia-Pacific USD 0.58 Billion (2025) Australia and NZ premium clinics


Korea's Ministry of Food and Drug Safety approved a record number of aesthetic device applications during 2024, and Korean manufacturers now supply a substantial share of mid-price radiofrequency platforms sold across Southeast Asia [16]. China's NMPA green-channel review has similarly compressed domestic filler approval timelines, accelerating the Non Invasive Aesthetic Treatment Market across the region.

South America

Country Metric Key Driver
Brazil 61.3% of region Second-largest global procedure base
Argentina USD 0.42 Billion (2025) Currency-driven inbound tourism
Rest of South America 9.4% CAGR (2026–2035) Colombia and Chile clinic growth


Brazil's ANVISA maintains one of the world's broadest approved-filler registries, and per-capita procedure rates rival North America despite far lower average pricing [17]. Currency weakness has turned Buenos Aires and São Paulo into value destinations for North American and European patients.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 33.1% of region Vision 2030 health investment
UAE USD 0.61 Billion (2025) International clinic licensing
South Africa 12.4% of region Regional referral centre
Egypt 10.9% CAGR (2026–2035) Rising urban middle class
Rest of MEA 8.7% of region Gulf spillover demand


Saudi health-sector investment under Vision 2030 has funded private clinic infrastructure well beyond core hospital services, and Dubai Health Authority licensing reforms shortened foreign-practitioner onboarding to under 90 days [15].


Non Invasive Aesthetic Treatment Market By Region, 2025-2035

Non Invasive Aesthetic Treatment Market Segmentation

Segmentation of the Non Invasive Aesthetic Treatment Market follows product technology, delivery channel, patient demographics, and treated anatomy.

By Product Type

Segment Metric Primary Demand Driver
Injectable Neurotoxins 38.5% share (2025) Botulinum toxin type A brand equity
Injectable Dermal Fillers USD 10.63 Billion (2025) Volume restoration and contour
Energy-Based Systems 13.44% CAGR (2026–2035) Multimodal clearance breadth
Chemical Peels & Microdermabrasion 9.4% share (2025) Entry-price patient acquisition
Other Products USD 2.77 Billion (2025) Threads, mesotherapy adjuncts


Neurotoxins remain the anchor product of the Non Invasive Aesthetic Treatment Market because they create a habitual repeat visit that no other modality matches. Their share is nonetheless eroding as price competition intensifies. Energy-based systems grow fastest, helped by platforms that combine radiofrequency, ultrasound, and laser in a single chassis, which lets a clinic address more indications from one capital purchase.

By End User

Segment Metric Primary Demand Driver
Dermatology & Plastic-Surgery Clinics 41.1% share (2025) Physician credibility, complex cases
Medical Spas 12.38% CAGR (2026–2035) Membership pricing, convenience
Hospitals USD 8.21 Billion (2025) Reconstructive adjacency
Home-Use & Other Settings 6.4% share (2025) Maintenance between clinic visits


Physician-led clinics keep the largest revenue pool in the Non Invasive Aesthetic Treatment Market because they retain the patients with higher complexity and higher willingness to pay. Medical spas, meanwhile, win on convenience and price transparency, and their growth is the primary reason total procedure counts are outrunning average revenue per procedure.

By Gender and Age Group

Segment Metric Primary Demand Driver
Female 80.5% share (2025) Established treatment norms
Male 10.46% CAGR (2026–2035) Jawline and hair-restoration demand
13–39 11.20% CAGR (2026–2035) Preventative and social-media-led uptake
40–54 39.6% share (2025) Peak disposable income cohort
55–69 USD 10.89 Billion (2025) Skin quality and laxity correction
70+ 8.4% share (2025) Maintenance treatments


Demographic widening is the structural growth engine of the Non Invasive Aesthetic Treatment Market. Younger patients enter earlier and treat preventatively, which extends lifetime value well beyond the historical pattern of first treatment near age 45.

By Application

Segment Metric Primary Demand Driver
Facial Aesthetics 48.1% share (2025) Non-invasive facial rejuvenation demand
Body Contouring 12.02% CAGR (2026–2035) Post-GLP-1 skin laxity
Skin Rejuvenation & Resurfacing 15.6% share (2025) Pigmentation and texture correction
Hair Removal & Restoration USD 4.00 Billion (2025) Repeat-session economics
Other Applications 4.3% share (2025) Vascular and scar treatment


Facial work still dominates because it delivers the most visible result per dollar. Body procedures grow faster for reasons that had nothing to do with aesthetics five years ago, namely the pharmacological weight-loss wave discussed in.


Competitive Benchmarking

Concentration in the Non Invasive Aesthetic Treatment Market is moderate. The estimated Herfindahl-Hirschman Index sits near 980, and the top five suppliers account for roughly 46–52% of global revenue. Injectables are considerably more concentrated than devices; energy platforms remain genuinely fragmented, with more than 60 manufacturers holding meaningful regional positions.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
AbbVie (Allergan Aesthetics) ~17–21% Botox Cosmetic, Juvederm, CoolSculpting Category anchor across toxin, filler, device
Galderma ~10–13% Dysport, Restylane, Sculptra Injectable-pure-play with biostimulator depth
Merz Aesthetics ~7–9% Xeomin, Radiesse, Ultherapy Toxin-plus-ultrasound tightening bundle
Cutera ~3–5% truSculpt, Secret RF, excel V+ Multimodal energy platforms, clinic-tier pricing
InMode ~4–6% Morpheus8, BodyTite, Evoke RF microneedling leadership, high consumables mix
Hologic (Cynosure Lutronic) ~4–6% Elite iQ, PicoSure, Ultraformer Broad laser and pico portfolio
Bausch Health (Solta Medical) ~3–5% Thermage FLX, Fraxel, Clear + Brilliant Legacy tightening brands, strong APAC pull
Candela Medical ~3–5% GentleMax Pro, Profound, Nordlys Hair removal and vascular strength
Sisram Medical (Alma Lasers) ~2–4% Alma Harmony, Accent Prime, Soprano Value-tier global distribution
Classys ~2–4% Ultraformer III, Volnewmer Korean export leader in HIFU
Revance Therapeutics ~1–3% Daxxify, RHA fillers Long-duration toxin challenger
Venus Concept ~1–2% Venus Versa, Venus Legacy Subscription-led equipment placement


Recent News & Developments

  • AbbVie (March 2024): Reported Botox Cosmetic global sales above USD 2.7 billion for 2023, reinforcing injectable share leadership despite new entrants [19]


  • InMode (June 2024): Introduced expanded Morpheus8 configurations targeting post-weight-loss skin laxity, directly addressing GLP-1 patient flow [7]
  • Galderma (March 2024): Completed initial public offering on SIX Swiss Exchange, raising roughly CHF 2.3 billion to fund aesthetic portfolio expansion [20]
  • ]
  • Korea MFDS (November 2024): Streamlined review pathway for domestically manufactured energy-based aesthetic devices, shortening approval timelines materially [16]
  • UK Government (2025): Advanced licensing framework consultation for non-surgical cosmetic procedures in England, moving toward statutory practitioner standards [14]
  • Sisram Medical (July 2025): Expanded Alma distribution agreements across Gulf markets to capture medical-tourism clinic build-out [15]


Non Invasive Aesthetic Treatment Market Report Scope

Parameter Detail
Market Scope Global Non Invasive Aesthetic Treatment Market by product type, end user, gender, age group, application, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.98% (2026–2035)
Market Size Checkpoints USD 43.93 Billion (2025); USD 47.11 Billion (2026); USD 102.14 Billion (2035)
Fastest Growing Segments Energy-Based Systems (product); Medical Spas (end user); Body Contouring (application); Asia-Pacific (region)
Companies Profiled 12 major suppliers including AbbVie, Galderma, Merz Aesthetics, Cutera, InMode, Hologic, Bausch Health, Candela, Sisram, Classys, Revance, Venus Concept
Valuation Currency USD Billion, end-user transaction value

FAQs

What capital-payback period should a clinic model when buying into the Non Invasive Aesthetic Treatment Market?
Most mid-price energy platforms reach payback in 14–22 months at 55% utilization. Below 35% utilization, payback stretches past three years and financing terms usually turn unattractive [4].
How should procurement teams compare consumables lock-in across vendors?
Model total five-year cost, not sticker price. Proprietary-cartridge systems in the Non Invasive Aesthetic Treatment Market often cost 40–60% more over the asset life than open-consumable equivalents, even when the initial quote looks lower [23].
Which technology comparison matters most for buyers entering the Non Invasive Aesthetic Treatment Market?
Radiofrequency microneedling versus focused ultrasound. Ultrasound reaches deeper SMAS layers with fewer sessions; radiofrequency handles textural correction and suits a broader skin-type range [1].
What regulatory nuance most often surprises new market entrants?
Aesthetic lasers face state-level practitioner supervision rules that differ from federal device clearance. A cleared device can still be unusable by a given operator in certain U.S. states [13].
Are there emerging use cases beyond cosmetics in the Non Invasive Aesthetic Treatment Market?
Yes. Energy platforms are being applied to hyperhidrosis, acne scarring, and post-oncology reconstruction support, opening partial reimbursement pathways that pure cosmetic indications never had [1].
What integration challenge do multi-site clinic groups underestimate?
Practice-management software rarely talks to device consoles. Groups typically spend USD 60,000–150,000 on middleware and imaging integration before outcome data becomes usable across locations [3].
Which competitive dynamic will reshape supplier negotiations by 2030?
Korean and Chinese manufacturers are closing the performance gap at 30–45% lower price points. Western incumbents will defend on clinical evidence and service networks rather than list price [16].      
Author
Author Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author Co-Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, energy-based device research studies, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health, European Medicines Agency (EMA), International Electrotechnical Commission (IEC) Medical Device Standards, International Society of Aesthetic Plastic Surgery (ISAPS.org), American Society for Dermatologic Surgery (ASDS), American Society of Plastic Surgeons (ASPS), American Academy of Dermatology (AAD), National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), CDC National Center for Health Statistics, World Health Organization (WHO) Global Health Observatory, EU Eurostat Health Database, Organisation for Economic Co-operation and Development (OECD) Health Statistics, International Medical Device Regulators Forum (IMDRF), American Society for Laser Medicine and Surgery (ASLMS), and national health ministry reports from key markets. These sources were used to collect procedure statistics, regulatory approval data for laser, IPL, radiofrequency, ultrasound, and cryotherapy devices, clinical safety studies, demographic trends, and market landscape analysis across skin tightening, wrinkle reduction, hair removal, fat reduction, and acne treatment applications.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, heads of regulatory affairs, R&D directors for energy-based technologies, and commercial directors from laser system OEMs, non-invasive aesthetic device makers, and aesthetic technology businesses were examples of supply-side sources. Board-certified dermatologists, plastic surgeons, medical spa medical directors, laser clinic operators, and procurement leads from dermatology clinics, cosmetic centers, and med spas were examples of demand-side sources. Primary research verified product pipeline timelines for combination devices and handheld technologies, validated market segmentation across treatment types (laser, IPL, radiofrequency, ultrasound, cryotherapy), and obtained information on clinical adoption patterns, pricing strategies, reimbursement dynamics, and the trend toward home-use aesthetic devices.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping, procedure volume analysis, and device installation base assessment. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across laser treatment systems, intense pulsed light (IPL) devices, radiofrequency platforms, ultrasound technologies, and cryotherapy equipment

Device type analysis covering stand-alone devices, handheld devices, and combination multi-technology platforms

Application segmentation analysis across skin tightening, wrinkle reduction, hair removal, fat reduction, and acne treatment

End-user mapping including dermatologists/plastic surgeons, med spas/laser clinics, and emerging home-use segments

Analysis of reported and modeled annual revenues specific to non-invasive aesthetic device portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (procedure volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations across treatment modalities and geographic markets

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















