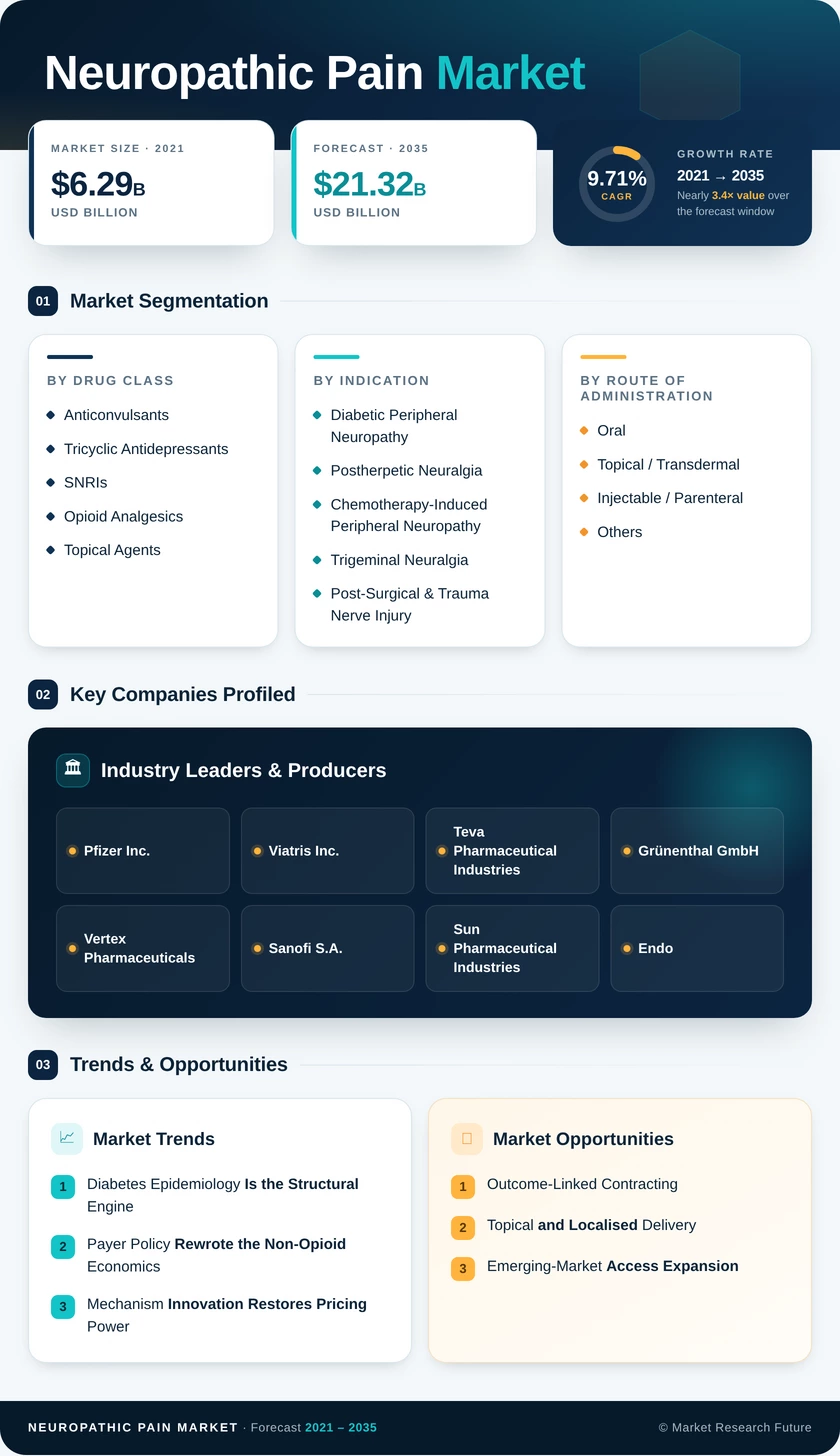
Neuropathic Pain Market (2026 - 2035)

ID: MRFR/HC/0881-CR 200 Pages Nidhi Mandole Last Updated: September 15, 2026
Neuropathic Pain Market Research Report By Type of Neuropathic Pain (Diabetic Neuropathy, Postherpetic Neuralgia, Trigeminal Neuralgia, Chemotherapy-Induced Peripheral Neuropathy), By Treatment Type (Medications, Physical Therapy, Surgical Procedures, Electrical Stimulation), By Route of Administration (Oral, Topical, Injectable), By End User (Hospitals, Clinics, Home Care) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
Neuropathic Pain Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)9.71%
2025 Market SizeUSD 8.48 Billion
2035 Market SizeUSD 21.32 Billion
Key Players
Pfizer Inc.
Viatris Inc.
Teva Pharmaceutical Industries
Grünenthal GmbH
Vertex Pharmaceuticals
Sanofi S.A.
Opportunities
  • Outcome-Linked Contracting
  • Topical and Localised Delivery
  • Emerging-Market Access Expansion
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Drug Class |
    2. 2.2 By Indication |
    3. 2.3 By Region
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Diabetes Epidemiology as the Structural Engine |
    2. 4.2 Non-Opioid Reimbursement Reform |
    3. 4.3 Mechanism Innovation and Pricing Power |
    4. 4.4 Cancer Survivorship and Supportive Care Demand
  5. 5 Restraints Impact Analysis |
    1. 5.1 Price Erosion in Mature Molecules |
    2. 5.2 Clinical Efficacy Ceilings |
    3. 5.3 Regulatory Tightening Around Gabapentinoids
  6. 6 Opportunities |
    1. 6.1 Outcome-Linked Contracting |
    2. 6.2 Topical and Localised Delivery |
    3. 6.3 Emerging-Market Access Expansion |
    4. 6.4 Real-World Evidence as a Revenue Line |
    5. 6.5 Precision Phenotyping and Stratified Trials
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Digital Phenotyping and Algorithmic Titration |
    2. 8.2 Value-Based Contracting |
    3. 8.3 Mechanism Diversification Beyond Ion Channels |
    4. 8.4 Manufacturing Localisation and Supply Resilience
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Drug Class | |
      1. 9.1.1 Anticonvulsants | |
      2. 9.1.2 Tricyclic Antidepressants | |
      3. 9.1.3 SNRIs | |
      4. 9.1.4 Opioid Analgesics | |
      5. 9.1.5 Topical Agents | |
      6. 9.1.6 Local Anesthetics & Others |
    2. 9.2 By Indication | |
      1. 9.2.1 Diabetic Peripheral Neuropathy | |
      2. 9.2.2 Postherpetic Neuralgia | |
      3. 9.2.3 Chemotherapy-Induced Peripheral Neuropathy | |
      4. 9.2.4 Trigeminal Neuralgia | |
      5. 9.2.5 Post-Surgical & Trauma Nerve Injury | |
      6. 9.2.6 Central Neuropathic Pain | |
      7. 9.2.7 HIV-Associated & Others |
    3. 9.3 By Route of Administration | |
      1. 9.3.1 Oral | |
      2. 9.3.2 Topical / Transdermal | |
      3. 9.3.3 Injectable / Parenteral | |
      4. 9.3.4 Others |
    4. 9.4 By Distribution Channel | |
      1. 9.4.1 Hospital Pharmacies | |
      2. 9.4.2 Retail Pharmacies | |
      3. 9.4.3 Online Pharmacies | |
      4. 9.4.4 Others
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Pfizer Inc. | |
      2. 10.3.2 Viatris Inc. | |
      3. 10.3.3 Teva Pharmaceutical Industries | |
      4. 10.3.4 Grünenthal GmbH | |
      5. 10.3.5 Eli Lilly and Company | |
      6. 10.3.6 Vertex Pharmaceuticals | |
      7. 10.3.7 Sanofi S.A. | |
      8. 10.3.8 Sun Pharmaceutical Industries | |
      9. 10.3.9 Endo, Inc. | |
      10. 10.3.10 Bausch Health Companies | |
      11. 10.3.11 Daiichi Sankyo Company | |
      12. 10.3.12 Novartis AG
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Neuropathic Pain Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Neuropathic Pain Market — Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Neuropathic Pain Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Neuropathic Pain Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Neuropathic Pain Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Neuropathic Pain Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Neuropathic Pain Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Neuropathic Pain Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Neuropathic Pain Market Size, by Drug Class, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Neuropathic Pain Market Size, by Indication, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Neuropathic Pain Market Size, by Route of Administration, 2021–2035 (USD Billion) |
  29. TABLE 14 Global Neuropathic Pain Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Neuropathic Pain Market Size, by Drug Class, 2021–2035 (USD Billion) |
  31. TABLE 16 Europe Neuropathic Pain Market Size, by Indication, 2021–2035 (USD Billion) |
  32. TABLE 17 Asia-Pacific Neuropathic Pain Market Size, by Route of Administration, 2021–2035 (USD Billion) |
  33. TABLE 18 South America Neuropathic Pain Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  34. TABLE 19 Middle East & Africa Neuropathic Pain Market Size, by Drug Class, 2021–2035 (USD Billion) |
  35. TABLE 20 Competitive Benchmarking Matrix — Global Neuropathic Pain Market, 2026 |
  36. TABLE 21 Company Profiles — Key Players, Global Neuropathic Pain Market |
  37. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 |
  38. TABLE 23 Report Scope & Methodology Summary |
  39. TABLE 24 Detailed Sources & Citations Index
  40. 16 LIST OF FIGURES |
  41. FIGURE 1 Market Dynamics — Drivers, Restraints, Opportunities and Challenges |
  42. FIGURE 2 Industry Value Chain Analysis — Discovery to Dispensing |
  43. FIGURE 3 Porter's Five Forces Analysis |
  44. FIGURE 4 Global Market Size Trend Line, 2021–2035 (USD Billion) |
  45. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 (%) |
  46. FIGURE 6 Market Share by Drug Class, 2025 vs 2035 (%) |
  47. FIGURE 7 Market Share by Indication, 2025 vs 2035 (%) |
  48. FIGURE 8 Market Share by Route of Administration, 2025 (%) |
  49. FIGURE 9 Market Share by Distribution Channel, 2025 (%) |
  50. FIGURE 10 Regional Revenue Share Distribution, 2025 (%) |
  51. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  52. FIGURE 12 Country-Level Contribution Heat Map, 2025 |
  53. FIGURE 13 Competitive Landscape — Estimated Revenue Share Bands, 2026 |
  54. FIGURE 14 Strategic Positioning Quadrant — Innovation vs Scale |
  55. FIGURE 15 Pipeline Distribution by Mechanism Class, 2026

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Drug ClassAnticonvulsants; Tricyclic Antidepressants; SNRIs; Opioid Analgesics; Topical Agents; Local Anesthetics & OthersAnticonvulsantsTopical Agents
By IndicationDiabetic Peripheral Neuropathy; Postherpetic Neuralgia; Chemotherapy-Induced Peripheral Neuropathy; Trigeminal Neuralgia; Post-Surgical & Trauma Nerve Injury; Central Neuropathic Pain; HIV-Associated & OthersDiabetic Peripheral NeuropathyChemotherapy-Induced Peripheral Neuropathy
By Route of AdministrationOral; Topical / Transdermal; Injectable / Parenteral; OthersOralTopical / Transdermal
By Distribution ChannelHospital Pharmacies; Retail Pharmacies; Online Pharmacies; OthersHospital PharmaciesOnline Pharmacies
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Drug Class

Sub-SegmentKey Trend
AnticonvulsantsVolume leadership persists while net pricing compresses under generic saturation
Tricyclic AntidepressantsRetained in cost-sensitive systems despite anticholinergic tolerability limits
SNRIsDuloxetine anchored by category 1 guideline support in oncology supportive care
Opioid AnalgesicsConfined to refractory and palliative settings as stewardship programmes tighten
Topical AgentsFastest-compounding class; quarterly patch economics outperform daily orals
Local Anesthetics & OthersGrowth tied to interventional block procedures in specialist clinics


Drug class is where the value-versus-volume split is starkest. Prescription counts still concentrate in generic orals, but incremental revenue is migrating toward localised formulations and mechanism-differentiated entrants that can defend a premium tier.

By Indication

Sub-SegmentKey Trend
Diabetic Peripheral NeuropathyScreening mandates convert undiagnosed prevalence into treated demand annually
Postherpetic NeuralgiaZoster vaccination will slow incidence, but prevalent cohorts sustain demand into the 2030s
Chemotherapy-Induced Peripheral NeuropathyPredictable, regimen-linked demand makes it the most forecastable growth segment
Trigeminal NeuralgiaCarbamazepine remains standard; surgical referral rates rising
Post-Surgical & Trauma Nerve InjuryPerioperative prevention protocols expand preventive prescribing
Central Neuropathic PainMultiple sclerosis and spinal cord injury cohorts drive specialist-channel volume
HIV-Associated & OthersConcentrated in sub-Saharan Africa; low-cost oral agents dominate


Indication mix determines channel strategy. Metabolic and post-viral indications flow through primary care and retail, while oncology and central presentations require hospital and specialist access — two very different commercial builds.

By Route of Administration

Sub-SegmentKey Trend
OralDefault first-line route; cost structure caps revenue upside
Topical / TransdermalPreferred in elderly and localised presentations; strongest margin profile
Injectable / ParenteralTied to interventional procedure volumes in accredited pain centres
OthersIntrathecal and implantable systems serve a small refractory population


Route mix determines commercial strategy. Oral therapies flow through primary care and retail channels, while topical and transdermal products emphasize localized treatment and specialist use. Injectable and parenteral therapies require hospital-based administration, whereas other formulations serve specialized delivery needs across the Neuropathic Pain Market.

By Distribution Channel

Sub-SegmentKey Trend
Hospital PharmaciesCapture initiation and titration; benefit from separate non-opioid payment rules
Retail PharmaciesSustain chronic refill volumes and generic substitution economics
Online PharmaciesFastest-growing channel on the back of permanent telehealth prescribing rules
OthersLong-term care and institutional mail-order supply grow with ageing demographics


Channel economics are shifting toward digital fulfilment for maintenance therapy while hospitals retain control of initiation. Manufacturers that align sampling, adherence support, and titration guidance to that split protect persistence rates.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.