Microcarriers Market (2026 - 2035)

Microcarriers Market Research Report Information By Product Type (Equipment {Bioreactors, Culture Vessels, Cell Counters, Filtration Systems, and Other Equipment}, Consumables {Media [Serum-Based Media, Serum-Free Media, and Other Media], Reagents, Microcarrier Beads {Cationic Microcarriers, Collagen-coated Microcarriers, Protein-coated Microcarriers, and Other Microcarrier Beads}), By Application (Vaccine Manufacturing, Cell Therapy, Biologics Manufacturing, and Other Applications), By End User (Pharmaceutical & Biotechnology Companies, Research Institutes, and Contract Research Organizations), and Region (North America, Europe, Asia-Pacific, and the Rest of the World)—Forecast till 2035

Forecast Period
2026-2035
CAGR
6.20%
2025 Market Size
USD 2.30 Billion
2035 Market Size
USD 4.18 Billion
Life Sciences ● Updated August 24, 2026 Report ID: MRFR/LS/5446-HCR | Pages: 90 | Author: Vikita Thakur, Kinjoll Dey

Microcarriers Market Summary

The Microcarriers Market was valued at USD 2.30 billion in 2025 and opens the forecast window at USD 2.43 billion in 2026, reaching USD 4.18 billion by 2035 at a 6.20% CAGR. Two catalysts anchor that trajectory. CEPI's 100 Days Mission has committed more than USD 3.5 billion toward pandemic-response manufacturing readiness, much of it flowing into adherent-cell vaccine platforms [3]. In parallel, the FDA's Office of Therapeutic Products has been expanding review capacity for cell and gene therapy filings, tightening the link between carrier supply reliability and clinical timelines [5].

Manufacturers are retiring roller bottles, multi-tray stacks and fixed-bed glass systems in favour of stirred single-use vessels seeded with cell culture microcarrier beads. The economics are hard to argue with: a 2,000 L single-use train can replace roughly forty 10-tray stacks while cutting cleaning validation to near zero. Sartorius and Cytiva together directed over USD 1.1 billion into bioprocess consumables capacity between 2022 and 2025 [7][8]. That capital is reshaping how the Microcarriers Market prices, packages and qualifies its products.

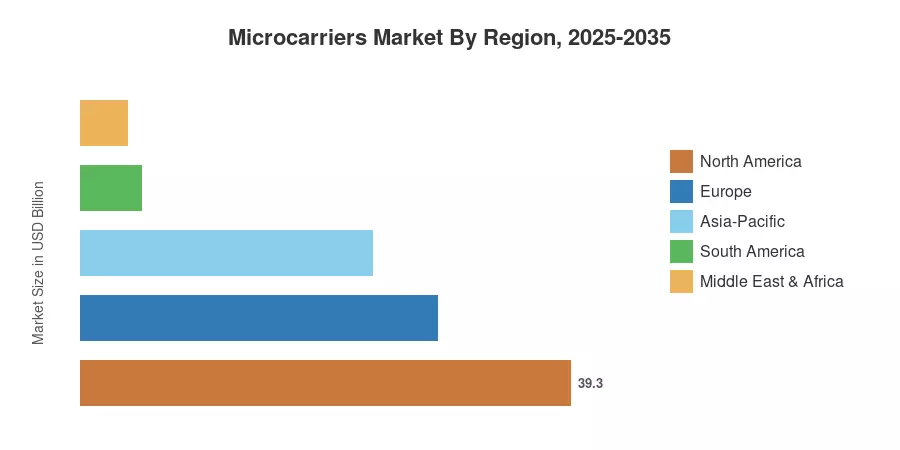
North America held 39.3% of the Microcarriers Market in 2025, supported by dense CDMO clusters in Massachusetts, Maryland and North Carolina. Asia-Pacific advances fastest at a 7.1% CAGR, propelled by Chinese and Indian vaccine tenders. Europe follows as the second-largest region on the strength of EMA-aligned ATMP manufacturing. Expect the gap between these three blocs to narrow through 2030.


Key Report Takeaways

• By Technology (Material Type)

  • Polystyrene-based carriers held 39.9% of the Microcarriers Market in 2025
  • Alginate-based carriers are expanding at a 7.0% CAGR through 2035
  • Dextran-based carriers generated USD 0.57 billion in 2025

• By Sector (Application & End User)

  • Vaccine manufacturing accounted for 35.9% of demand in 2025
  • Cell therapy applications post a 6.8% CAGR to 2035
  • CROs and CDMOs grow at 6.9% CAGR, the quickest end-user cohort

• By Region

  • North America commanded 39.3% share of the Microcarriers Market in 2025
  • Asia-Pacific climbs at 7.1% CAGR, the fastest regional pace
  • Europe contributed USD 0.66 billion in 2025


Market Size and Forecast (2021–2035)

Estimates blend bottom-up consumable consumption modelling across roughly 1,900 licensed biomanufacturing sites with top-down triangulation against reported bioprocess segment revenues from Thermo Fisher, Danaher, Sartorius and Merck KGaA [8][9][10]. Historical years are reconciled to customs-level trade data for polymer bead imports. Forecast years apply installed-capacity growth weighted by therapy-class approval rates.
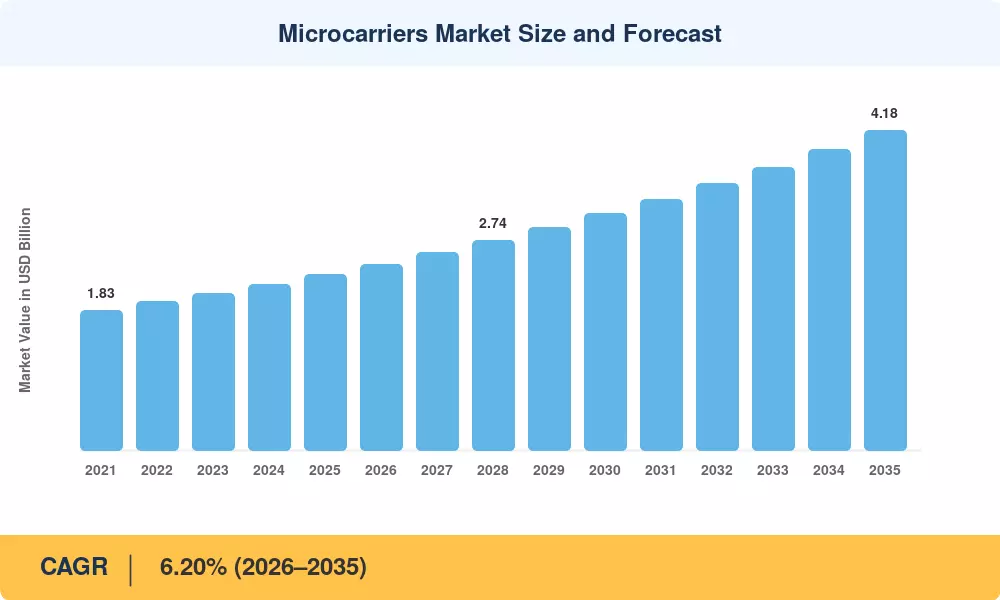
Microcarriers Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Cell-based vaccine capacity expansion ~1.3 pp Global Medium-term (2–4 yr)
Cell and gene therapy commercialisation ~1.1 pp North America, Europe Long-term (≥4 yr)
Migration to single-use continuous bioprocessing ~0.9 pp Global Medium-term (2–4 yr)
CDMO capacity buildout in Asia-Pacific ~0.8 pp Asia-Pacific Short-term (≤2 yr)
Cultivated-protein R&D funding ~0.6 pp Europe, Singapore, Israel Long-term (≥4 yr)
Automation and closed-system harvest ~0.5 pp Global Short-term (≤2 yr)
Regenerative medicine reimbursement pathways ~0.4 pp Japan, EU Long-term (≥4 yr)


Cell-Based Vaccine Capacity Expansion

Vero and MDCK cell platforms have displaced egg-based influenza production across a growing share of global capacity, and every litre of that capacity consumes carriers. Gavi's 2026–2030 replenishment targets USD 9.0 billion, with a stated priority on regional manufacturing hubs in Africa and Southeast Asia [4]. The African Vaccine Manufacturing Accelerator alone allocates USD 1.2 billion in outcome-based payments through 2035 [4]. Each new fill-finish-plus-drug-substance site typically adds 400–900 kg of annual carrier demand.

Cell and Gene Therapy Commercialisation

Adherent MSC and iPSC-derived products cannot scale on flatware beyond early Phase II. The Alliance for Regenerative Medicine counted more than 2,700 active clinical trials worldwide at the close of 2024, with roughly 12% using adherent cell types [6]. Once a sponsor validates a carrier for a pivotal trial, switching costs become prohibitive — a dynamic that rewards suppliers with documented lot-to-lot consistency and full regulatory support files.

Migration to Single-Use Continuous Bioprocessing

Perfusion and intensified fed-batch operations push cell densities toward 40–60 million cells per millilitre, roughly triple conventional batch performance [7]. Facilities running these platforms report utility consumption reductions near 30% and floor-space savings of 25–40% versus stainless-steel equivalents [7]. Carrier suppliers that ship gamma-irradiated, pre-hydrated formats in ready-to-use bags capture disproportionate value from this shift.

CDMO Capacity Buildout in Asia-Pacific

Contract manufacturers in South Korea, China and India added an estimated 1.4 million litres of biologics capacity between 2022 and 2025 [12]. India's Department of Biotechnology committed roughly USD 380 million under BioE3 to biomanufacturing infrastructure [13]. These sites tend to standardise on two or three carrier chemistries across many clients, which concentrates purchasing volume and intensifies price negotiation.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Biologics price compression and biosimilar entry ~-0.7 pp North America, Europe Medium-term (2–4 yr)
Cell detachment and harvest yield losses ~-0.6 pp Global Short-term (≤2 yr)
Shear stress complexity at commercial scale ~-0.5 pp Global Medium-term (2–4 yr)
Regulatory scrutiny of animal-derived components ~-0.4 pp Europe, North America Short-term (≤2 yr)
Validation and changeover cost for smaller labs ~-0.3 pp Emerging markets Long-term (≥4 yr)


Biologics Price Compression

Payers are squeezing biologics pricing hard. The US Inflation Reduction Act's negotiation programme covered 10 drugs in its first cycle and expands to 15 more for 2027, with negotiated prices averaging 22% below list [11]. Manufacturers respond by pressing consumable suppliers for 3–5% annual cost concessions. Carrier vendors absorb part of that through resin sourcing efficiency, but margin compression is real and persistent.

Harvest Yield and Detachment Losses

Recovering viable cells from a bead surface remains the least elegant step in the workflow. Trypsinisation cycles at 2,000 L scale routinely lose 15–25% of biomass, and enzymatic exposure can shift critical quality attributes [15]. Thermo-responsive and dissolvable chemistries address this, but they carry a 40–70% price premium and thinner regulatory precedent, which slows adoption among risk-averse commercial programmes.

Scale-Up Hydrodynamic Complexity

Translating a 3 L spinner result to a 500 L stirred tank is not a linear exercise. Kolmogorov eddy length must stay above bead diameter or cells shear off, forcing impeller redesign and often a change of carrier density [15]. Engineering studies suggest scale-up campaigns add 4–9 months to tech transfer timelines, a delay that occasionally pushes sponsors back toward fixed-bed alternatives.


Microcarriers Market Opportunities

Dissolvable and Enzyme-Free Carriers

Polymer chemistries that dissolve on demand remove bead-separation altogether, combining two unit actions into one. Early commercial data suggest improvements in recovery of 18-24% over standard trypsinisation [15]. Suppliers will be positioned for premium pricing as cell therapy volumes rise, with validated residual-clearance assays used in conjunction with dissolvable carriers.


Emerging-Market Vaccine Localisation

Africa presently produces less than 2% of the vaccinations it uses, well below an African Union target of 60% by 2040 [4]. Greenfield sites in Rwanda, Senegal, Egypt and South Africa are specifying adherent-cell platforms from day one. Distributors with local technical service and cold-chain-free carrier logistics will be there to grab this demand long ahead of global incumbents localizing.


Cultivated Protein and Food-Grade Substrates

Food-grade, edible carriers made from alginate, cellulose or soy protein avoid the removal problem altogether, because they become part of the product. Singapore, Israel and the Netherlands have combined invested over USD 400 million in public investment for the scaling up of grown protein [16]. This is an adjacent demand pool with volume requirements an order of magnitude higher than pharma


Carrier-as-a-Service and Process Data Monetisation

Some providers now put attachment-kinetics datasets, digital-twin models and outcome-linked pricing into packages for carriers. Selling the process expertise, rather than the bead alone, moves the relationship from procurement to cooperation and protects against commoditization. CDMO contracts are starting to include subscription models for carrier supply, qualification support, and audit documentation.


Xeno-Free and Recombinant Coating Chemistries

EMA guidance continues to tighten around animal-derived raw materials in ATMP manufacturing [17]. Recombinant vitronectin and laminin coatings remove that risk while improving iPSC attachment consistency. Suppliers who convert their coated portfolios to fully recombinant sourcing ahead of mandates gain a durable qualification advantage.


Microcarriers Market Future Outlook

Autonomous Bioprocessing and Digital Twins

By 2030, expect a meaningful share of commercial adherent processes to run under model-predictive control rather than fixed recipes. In-line Raman and dielectric spectroscopy now track cell density on beads in real time, feeding digital twins that adjust feed rates automatically. Vendors reporting on automated bioreactor microcarrier systems cite labour reductions approaching 40% and tighter batch-to-batch consistency [14]. The Microcarriers Market will increasingly compete on data integration, not just bead chemistry.

Platform Economics and Supplier Consolidation

Consumables businesses reward scale, and the last decade proved it. Danaher's Cytiva-Pall integration and Sartorius's Polyplus acquisition both aimed at owning more of the workflow rather than a single component [8][10]. Anticipate two or three further mid-size acquisitions by 2030 as larger suppliers buy specialty chemistry rather than build it. Buyers should model supplier concentration risk into qualification strategy.

The Cultivated Protein Volume Shock

Food-scale bioreactors operate at volumes pharma rarely contemplates. If cultivated-protein producers reach even modest commercial output by 2032, carrier demand from that sector could rival current vaccine consumption. The OECD has flagged alternative protein scale-up as a material agricultural technology shift [22]. Cost per kilogram, not per gram, becomes the governing metric — a genuine discontinuity for incumbent pricing models.

Sustainability Reporting and Single-Use Waste

Single-use convenience carries a polymer waste bill that regulators are starting to notice. CSRD reporting obligations now cover a large share of European manufacturers, and Scope 3 disclosures make consumable footprints visible to procurement teams [23]. Suppliers offering bio-based or recyclable carrier substrates, plus verified take-back schemes, will find that sustainability credentials move from nice-to-have to tender requirement across the Microcarriers Market.


Microcarriers Market Segmentation

Segmentation in the Microcarriers Market follows material chemistry, application, end user and operational scale — four axes that buyers weigh simultaneously during qualification.

By Material Type

Segment Metric (2025 / Forecast) Primary Demand Driver
Polystyrene-Based 39.9% share Proven vaccine-platform track record
Dextran-Based USD 0.57 billion Legacy Cytodex qualification base
Alginate-Based 7.0% CAGR Dissolvable harvest and food-grade use
Collagen/Gelatin-Based USD 0.28 billion Enhanced attachment for primary cells
Others (Cellulose, PLGA, Glass) 5.8% CAGR Niche and research applications


Polystyrene retains its lead because switching costs are brutal. Once a Vero-cell influenza process is licensed on a specific bead surface treatment, changing chemistry triggers comparability studies that can cost seven figures and consume two years. Alginate is the interesting story. Its dissolvable behaviour solves the harvest problem that limits every other chemistry, and food-grade applications give it a demand pool outside pharmaceutical qualification timelines entirely.

By Application

Segment Metric (2025 / Forecast) Primary Demand Driver
Vaccine Manufacturing 35.9% share Pandemic readiness and seasonal influenza
Cell Therapy 6.8% CAGR MSC and iPSC commercialisation
Regenerative Medicine USD 0.31 billion Tissue engineering scale-up
Recombinant Proteins USD 0.34 billion Adherent expression systems
Other Applications 5.4% CAGR Toxicology and screening models


Vaccines remain the volume engine, but cell therapy sets the pricing ceiling. A single autologous batch consumes grams of carrier yet tolerates costs that would be unthinkable in vaccine manufacturing, which lets suppliers sustain premium SKUs. The Microcarriers Market therefore operates as two economies at once: a high-volume, cost-pressured vaccine business and a low-volume, specification-driven therapy business.

By End User

Segment Metric (2025 / Forecast) Primary Demand Driver
Biopharma and Biotechnology Firms 48.0% share In-house commercial manufacturing
CROs and CDMOs 6.9% CAGR Outsourced capacity growth
Academic and Research Institutes USD 0.27 billion Grant-funded process development
Other End Users 5.2% CAGR Food-tech and industrial biotech


Biopharmaceutical and biotechnology firms maintain the largest market share, driven by their extensive portfolios and the necessity of securing high-quality microcarrier supply for large-scale in-house commercial manufacturing. Meanwhile, Contract Research Organizations (CROs) and Contract Development and Manufacturing Organizations (CDMOs) remain a critical growth engine, reflecting the broader industry trend of outsourcing bioprocessing capacity and de-risking infrastructure investment.

By Scale of Operation

Segment Metric (2025 / Forecast) Primary Demand Driver
Commercial Scale 53.1% share Licensed product manufacturing
Pilot Scale 7.0% CAGR Tech transfer and Phase III readiness
Laboratory Scale USD 0.51 billion Screening and early development


Commercial-scale manufacturing accounts for the largest market share, anchored by high-volume requirements for approved therapeutics and licensed biological products. Meanwhile, pilot-scale operations represent a vital growth segment, propelled by increasing demand for robust scale-up capabilities, complex technology transfers, and rigorous Phase III clinical trial readiness.


Regional Market Share Analysis

Region Share of Global Market (2025) Primary Investment Themes
North America 39.3% CGT commercialisation, CDMO consolidation, BARDA readiness
Europe 28.6% ATMP manufacturing, xeno-free conversion, HERA stockpiling
Asia-Pacific 23.4% Vaccine self-sufficiency, CDMO capacity, biosimilar scale
South America 4.9% Public vaccine institutes, technology transfer
Middle East & Africa 3.8% Localisation mandates, sovereign health funds
Total 100.0%

Regional demand in the Microcarriers Market tracks biomanufacturing capacity far more closely than population or healthcare spend, which explains why three regions absorb roughly 91% of global volume.


North America

Country Share of Region (2025) Key Driver
US 82.4% Dense CGT sponsor base and BARDA contracts
Canada 10.1% Biomanufacturing Strategy funding
Mexico 7.5% Nearshoring of fill-finish and drug substance


The US anchors the Microcarriers Market through sheer concentration of sponsors. Massachusetts alone hosts more than 130 cell and gene therapy developers, and the state's Life Sciences Initiative renewed at USD 500 million through 2033 [6]. Canada's Biomanufacturing and Life Sciences Strategy has deployed roughly CAD 2.2 billion, with Mississauga and Montreal sites specifying single-use adherent platforms [19]. Mexican capacity remains modest but is growing as nearshoring pulls sterile manufacturing south.

Europe

Country Share of Region (2025) Key Driver
Germany 24.2% Bioprocess equipment cluster and CDMO density
UK 18.6% Cell and Gene Therapy Catapult scale-up centre
France 14.1% France 2030 health innovation funding
Italy 9.3% Advanced therapy hospital exemptions
Spain 7.8% Public CAR-T manufacturing programmes
Nordic Countries 8.4% Vaccine institutes and academic spinouts
Russia 4.9% Domestic vaccine self-sufficiency
Rest of Europe 12.7% Contract manufacturing in Ireland and Switzerland


Europe's position rests on regulation as much as capacity. HERA has budgeted EUR 1.3 billion through 2027 for medical countermeasure readiness, explicitly including flexible cell-culture capacity [17]. The UK's Cell and Gene Therapy Catapult reported that its Stevenage manufacturing centre reached full tenancy in 2024, with several tenants running adherent platforms [6]. German suppliers meanwhile export a substantial share of global bioprocess hardware, tying regional carrier demand to equipment cycles.

Asia-Pacific

Country CAGR (2026–2035) Key Driver
China 7.9% Vaccine tenders and domestic biosimilar scale
India 8.4% BioE3 policy and Serum Institute capacity
Japan 5.6% Sakigake regenerative medicine pathway
South Korea 7.2% CDMO expansion at Songdo
ASEAN 7.6% Singapore cultivated-protein and vaccine hubs
Rest of Asia-Pacific 6.1% Australian ATMP research base


Asia-Pacific is the fastest-moving block in the Microcarriers Market, and India is its sharpest curve. The BioE3 policy commits roughly USD 380 million to biomanufacturing infrastructure, targeting bio-enabled products across health and food [13]. China's NMPA approved a record number of domestically developed vaccines in 2024, several on Vero-cell platforms [12]. South Korean CDMOs continue to add capacity at pace, with Songdo cluster investments exceeding USD 6 billion since 2022 [12].

South America

Country Market Value (2025, USD B) Key Driver
Brazil 0.066 Butantan and Fiocruz technology transfer
Argentina 0.022 Domestic biosimilar manufacturing
Rest of South America 0.025 Regional PAHO procurement pooling


Brazil dominates regional demand through its public institutes. Butantan's influenza and dengue programmes have driven multi-year carrier supply agreements, and Fiocruz's Bio-Manguinhos expansion added significant drug-substance capacity in 2024 [21]. Argentina's mAb producers use adherent platforms selectively. Across the region, procurement cycles are tied to PAHO Revolving Fund tenders, which creates lumpy, tender-driven ordering patterns rather than smooth consumption.

Middle East & Africa

Country Share of Region (2025) Key Driver
Saudi Arabia 28.7% Vision 2030 localisation of biologics
UAE 21.4% Sovereign investment in vaccine plants
South Africa 19.8% Afrigen and Biovac mRNA/vaccine hubs
Egypt 14.3% VACSERA capacity modernisation
Rest of MEA 15.8% AVMA outcome-based financing


Africa's manufacturing gap is the region's defining feature and its largest opportunity. The African Vaccine Manufacturing Accelerator's USD 1.2 billion facility pays producers on delivered doses rather than upfront grants, which sharpens demand signals for consumable suppliers [4]. Saudi Arabia's Vision 2030 biologics localisation targets have already produced joint ventures with European manufacturers. Egypt's VACSERA modernisation programme continues to convert legacy roller-bottle lines.


Microcarriers Market By Region, 2025-2035

Competitive Benchmarking

Concentration is moderate. The top five suppliers hold roughly 52% of global revenue, producing an estimated HHI near 950 — meaningful clustering at the top, with a long tail of regional and specialty producers. Distribution matters as much as manufacturing: several players reach customers primarily through catalogue channels and OEM bundling with bioreactor hardware.

Company Est. Revenue Share Range Key Offerings for Microcarriers Market Strategic Positioning
Thermo Fisher Scientific ~13–16% Nunc, Synthemax surface-treated carriers Broad catalogue reach and global logistics
Cytiva (Danaher) ~12–15% Cytodex, Cytopore dextran families Deepest regulatory precedent base
Sartorius AG ~9–12% Carriers bundled with Ambr and Biostat systems Hardware-consumable integration
Merck KGaA ~7–10% Coated and xeno-free carrier portfolio Strong ATMP raw-material compliance
Corning Incorporated ~6–9% Enhanced-attachment and dissolvable carriers Surface-science differentiation
Eppendorf SE ~4–6% Carriers paired with BioBLU vessels Pilot and bench-scale strength
Lonza Group ~3–5% Process-linked carrier supply CDMO-embedded specification control
Getinge (Applikon) ~2–4% Bioreactor-matched carrier kits Engineering-led scale-up support
Repligen Corporation ~2–4% Perfusion-compatible carrier accessories Intensified-process niche
HiMedia Laboratories ~2–3% Cost-competitive carrier lines Asia-Pacific and emerging-market value tier


Recent News & Developments

  • Corning (March 2024): Expanded its dissolvable carrier line with a lot-release specification for residual polymer clearance, addressing a key cell therapy qualification barrier [15].
  • Sartorius (June 2024): Completed a EUR 100 million consumables plant expansion in Yauco, Puerto Rico, adding bioprocess capacity serving North American CDMOs [10].
  • Cytiva (September 2024): Launched a ready-to-use, gamma-irradiated carrier format in single-use bags, cutting hydration and sterilisation steps from customer workflows [8].
  • CEPI (November 2024): Awarded funding to expand adherent-cell vaccine capacity across three African sites under the 100 Days Mission [3].
  • Merck KGaA (February 2025): Converted its coated carrier portfolio to fully recombinant sourcing, aligning with tightening EMA guidance on animal-derived materials [17].
  • Thermo Fisher (May 2025): Announced a co-development agreement with a cultivated-protein producer to qualify food-grade carrier substrates at pilot scale [16].
  • India DBT (July 2025): Released BioE3 implementation guidelines naming biomanufacturing consumables as a priority localisation category [13].
  • Danaher (October 2025): Consolidated Pall and Cytiva bioprocess consumables under a unified commercial structure to simplify customer qualification [8].


Microcarriers Market Report Scope

Parameter Detail
Market Scope Global microcarrier products used for anchorage-dependent cell expansion across pharmaceutical, therapeutic, research and food-technology applications
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.20% (2026–2035)
Market Size Checkpoints USD 2.30 billion (2025); USD 2.43 billion (2026); USD 4.18 billion (2035)
Fastest Growing Segments Alginate-based carriers (material); cell therapy (application); CROs and CDMOs (end user); pilot scale (operation)
Companies Profiled 10 leading suppliers including Thermo Fisher Scientific, Cytiva, Sartorius, Merck KGaA and Corning
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

What should procurement teams verify before qualifying a supplier in the Microcarriers Market?
Request the full regulatory support file, extractables and leachables data, and at least three consecutive lot-release certificates. Confirm the supplier holds dual manufacturing sites for the same SKU [24].
How do porous and non-porous carriers differ in practice?
Porous carriers shelter cells from shear and support higher densities per gram, but complicate harvest and nutrient transfer. Non-porous surfaces suit processes where cell recovery matters more than density [15].
Does carrier cost materially affect cost of goods in the Microcarriers Market?
Carriers typically represent 2–5% of drug substance cost of goods, far below media and labour. Their real leverage is on yield and batch failure rates, not unit price [7].
What integration problems appear most often during technology transfer?
Impeller geometry mismatch and inadequate sampling representativeness cause most failures. Teams frequently underestimate bead settling in transfer lines, which skews in-process counts and triggers avoidable investigations [15].
Are dissolvable carriers commercially ready for licensed products in the Microcarriers Market?
Several are used in late-phase clinical manufacturing, but few appear in approved commercial processes. Residual-polymer clearance assays remain the main regulatory discussion point [15].
Why does xeno-free sourcing change supplier selection?
Animal-derived coatings introduce adventitious agent risk and complicate European filings. Recombinant alternatives cost more upfront but shorten regulatory review and reduce long-term supply disruption exposure [17].
Can cultivated-protein producers use pharmaceutical-grade carriers?
Rarely, because pharma pricing cannot survive food-sector economics, food-grade edible substrates built from alginate or cellulose are being developed specifically for that cost structure [16].      
Author
Author
Author Profile
Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.
Co-Author
Co-Author Profile
Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed biotechnology journals, clinical trial repositories, and authoritative industry organizations. Key sources included the US Food & Drug Administration (FDA) Center for Biologics Evaluation and Research (CBER), European Medicines Agency (EMA) Committee for Advanced Therapies, International Council for Harmonisation (ICH) guidelines Q5A-D, World Health Organization (WHO) Technical Report Series for cell substrates, International Society for Cell & Gene Therapy (ISCT), Alliance for Regenerative Medicine (ARM), Parenteral Drug Association (PDA), International Society for Pharmaceutical Engineering (ISPE), and Advanced Regenerative Manufacturing Institute (ARMI). Academic sources included PubMed/NCBI, ClinicalTrials.gov, Nature Biotechnology, Cytotherapy, Vaccine, and Cell Stem Cell. Statistical data was gathered from the National Institutes of Health (NIH) Office of Science Policy, CDC Vaccine Manufacturing and Supply Data, OECD Biotechnology Statistics, World Bank Health Expenditure Database, Eurostat Research & Development Indicators, and national biotechnology association reports (BIO, EuropaBio, Japan Bioindustry Association).

The following sources were employed to gather data on bioprocessing capacity, regulatory approval pathways for cell-based therapies, vaccine production statistics, clinical pipeline analysis for cell and gene therapies, and technology adoption trends in suspension cell culture systems.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of Chief Executive Officers, Chief Scientific Officers, Vice Presidents of Process Development, regulatory affairs chiefs, and commercial directors from microcarrier manufacturers, single-use bioreactor OEMs, cell culture media suppliers, and bioprocess equipment providers. Demand-side sources included Senior Directors of Manufacturing Sciences, Process Development Scientists, and the Head of Cell Culture. Operations and procurement managers from biopharmaceutical companies that are involved in the production of vaccines, the manufacturing of cell therapies, and the application of regenerative medicine. This includes both innovator companies and contract development manufacturing organizations (CDMOs). Primary research has confirmed the product pipeline timelines for novel dissolvable microcarrier technologies, validated market segmentation across microcarrier materials (collagen, dextran, polystyrene), bioreactor configurations, and application workflows, and gathered insights on single-use technology adoption, per-liter production economics, and outsourcing dynamics for cell culture processes.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

• By Region: North America (32%), Europe (30%), Asia-Pacific (25%), Rest of World (13%)


Market Size Estimation

Revenue mapping and bioprocessing capacity analysis were implemented to determine global market valuation. The methodology comprised the following:

• Identification of 35+ key manufacturers in North America, Europe, Asia-Pacific, and Latin America who specialize in bioprocess consumables, cell culture apparatus, and microcarrier beads

• Product mapping for stirred-tank bioreactor and single-use vessel configurations, as well as for collagen-based, dextran-based, polystyrene-based, and dissolvable microcarrier categories

• Examination of annual revenues that are specific to cell culture product portfolios and contract manufacturing service revenues that are attributable to microcarrier-based processes, as reported and modeled

• In 2024, the coverage of manufacturers will account for 65-70% of the global market share.

• Segment-specific valuations for vaccine production, cell therapy manufacturing, and gene therapy applications are derived through extrapolation using bottom-up (installed bioreactor capacity × microcarrier density requirements × ASP by region) and top-down (manufacturer revenue validation across consumables and equipment segments) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















