Marine Engine Monitoring System Market Summary
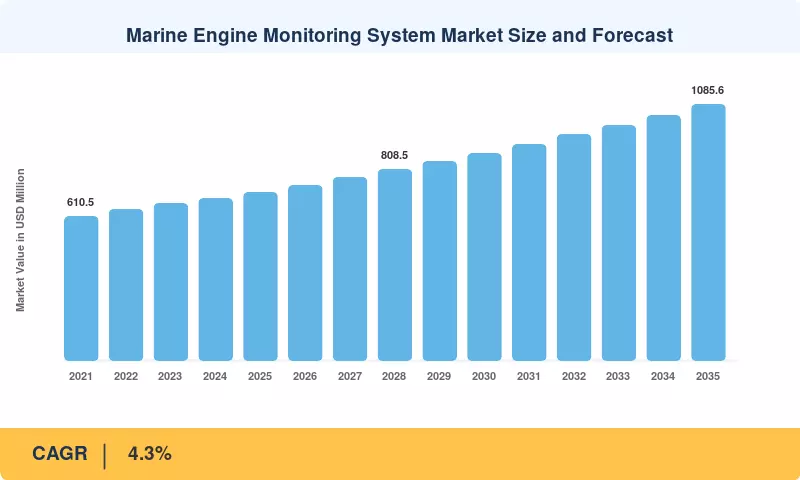
The Marine Engine Monitoring System Market was valued at USD 712.6 Million in 2025 and is projected to reach USD 743.2 Million in 2026, advancing to USD 1,085.6 Million by 2035 at a CAGR of 4.3% over 2026–2035. Two regulatory catalysts anchor this trajectory. The IMO Carbon Intensity Indicator (CII) tightens required reductions to 11% below the 2019 reference line by 2026 [1], and the EU Emissions Trading System began charging shipping for 40% of verified emissions in 2024, rising to 100% in 2026 [4]. Both regimes reward operators that measure fuel burn and engine load continuously rather than estimating them from noon reports.
Engine rooms are moving from analog gauge panels, standalone alarm units and handwritten logbooks toward networked sensor arrays, edge gateways and shore-side analytics. Classical alarm systems flagged faults only after thresholds were breached; current platforms combine vibration, exhaust-gas temperature, cylinder pressure and lube-oil condition data to forecast failures weeks ahead. Owners investing in vessel engine diagnostics are also responding to IACS Unified Requirements E26 and E27, which mandate cyber resilience for ships contracted from July 2024 [2]. Shipowners ordered 515 alternative-fuel vessels in 2024 [7], and each of those engines carries denser instrumentation than the diesel units it displaces.
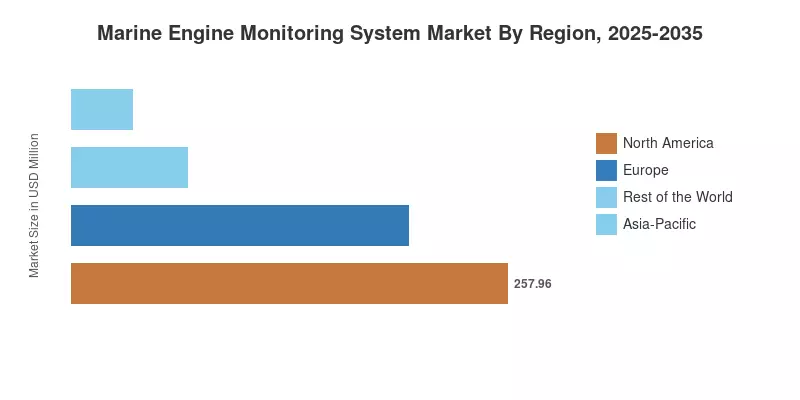
North America holds the dominant position with a 36.2% share, supported by naval procurement, a large cruise homeport base and domestic fleet renewal. Asia-Pacific is the fastest-growing region at a 5.1% CAGR, reflecting shipbuilding concentration in China, South Korea and Japan. Europe ranks second at USD 199.5 Million, driven by ETS and FuelEU compliance spending. Over the next decade, the Marine Engine Monitoring System Market will be shaped less by hardware volume than by the commercial value of the data each engine produces.
Key Report Takeaways
• By Type
- Vessel units, covering bulk carriers and general cargo ships, hold a 41.8% share of the Marine Engine Monitoring System Market, the largest of any type
- Container ships generated USD 197.2 Million in 2025, reflecting high sensor density on large dual-fuel newbuilds
- Passenger units are forecast to expand at a 5.0% CAGR as ferry operators replace aging propulsion plants
• By Engine Propulsion Type
- Diesel propulsion accounts for a 72.4% share, anchored by the two-stroke installed base
- Others, spanning dual-fuel LNG, methanol and hybrid-electric plants, are the fastest-growing propulsion group at a 6.1% CAGR
• By End Users
- tankers command a 38.6% share of Marine Engine Monitoring System Market revenue, driven by oil-major vetting requirements
- Cruise ships are the fastest-growing end user at a 6.4% CAGR on the back of a full orderbook
- passenger vessels represent USD 149.6 Million, led by ferry and ro-pax safety upgrades
• By Region
- North America leads the Marine Engine Monitoring System Market with a 36.2% share
- Asia-Pacific posts the highest regional growth at a 5.1% CAGR
- Europe accounts for USD 199.5 Million, underpinned by carbon-pricing exposure
Market Size and Forecast (2021–2035)
Market Research Future built the Marine Engine Monitoring System Market estimates from a bottom-up count of installed and newbuild systems by vessel type, cross-checked against supplier revenue disclosures, shipyard delivery data from Clarksons Research [22] and fleet statistics from UNCTAD [3]. Historical values for 2021–2024 reflect reported deliveries and retrofit activity, while forecast values for 2026–2035 apply scenario-weighted assumptions on regulation, fuel prices and newbuild volumes.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



