Liquid Dietary Supplements Market (2026 - 2035)

Liquid Dietary Supplements Market Size, Share, Industry Trend & Analysis Research Report By Ingredient Type (Vitamins & Minerals, Botanicals/Herbals, Proteins & Amino Acids, Omega-3 & Fatty Acids, Probiotics, Others), By Application (Sports Nutrition, Immune Health, Digestive Health, Cognitive & Stress Support, Energy & Weight Management, Bone & Joint Health, Others), By End User (Adults, Geriatric Population, Pregnant Women, Children), By Distribution Channel (Supermarkets/Hypermarkets, Pharmacies, Online Retail Stores, Specialty Stores, Other Channels), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/FnB/9932-CR 200 Pages Snehal Singh Last Updated: October 09, 2026
Liquid Dietary Supplements Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.6%
2025 Market SizeUSD 25.05 Billion
2035 Market SizeUSD 82.07 Billion
Key Players
Nestlé Health Science
Abbott Laboratories
Amway
Herbalife Ltd.
Haleon plc
Bayer AG
Opportunities
  • Personalized Subscriptions and First-Party Data
  • Emerging-Market Penetration Through Low-Cost Formats
  • Precision Dosing for Prenatal and Pediatric Users

Liquid Dietary Supplements Market Summary

The Liquid Dietary Supplements Market was valued at USD 25.05 Billion in 2025. It is projected to grow from USD 28.21 Billion in 2026 to USD 82.07 Billion by 2035, a CAGR of 12.6% over 2026–2035. Two regulatory catalysts anchor this outlook. The US FDA's 2024 final guidance on new dietary ingredient notification procedures gives formulators a clearer route for novel liquid actives [2]. India's FSSAI Health Supplements Regulations, 2022 formalized a category that previously operated in a regulatory grey zone [4].

Formulation technology is changing what a supplement looks like. Compressed tablets, large softgels and sugar-heavy syrups are giving way to micro-emulsified oils, liposomal vitamins, single-dose shots and ambient-stable probiotic liquids that improve absorption and dosing compliance. The consumer base is already large: the Council for Responsible Nutrition's 2023 survey found that 74% of US adults take supplements [5]. A growing share of that base, particularly older adults with swallowing difficulty, prefers drinkable formats.

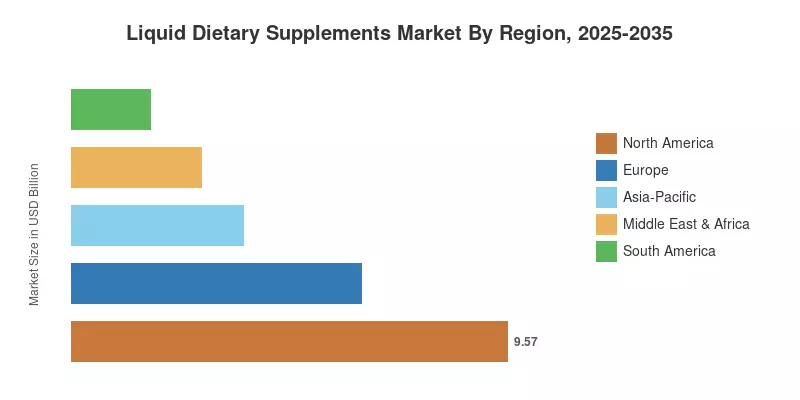
North America dominates the Liquid Dietary Supplements Market with a 38.2% share, supported by mature retail and direct-to-consumer infrastructure. Asia-Pacific is the fastest-growing region at a 15.1% CAGR, propelled by regulatory formalization in India and China and rising middle-class health spending. Europe ranks second at USD 6.36 billion, anchored by harmonized rules under Directive 2002/46/EC [7]. Over the next decade, competitive advantage will shift toward brands that pair clinical substantiation with delivery science.

Key Report Takeaways

• By Ingredient Type

  • Vitamins & Minerals hold a 29.9% share, the largest ingredient category in the Liquid Dietary Supplements Market.
  • Omega-3 & Fatty Acids lead ingredient growth at a 13.8% CAGR, helped by algal-sourced oils and micro-emulsion technology.

• By Application

  • Sports Nutrition accounts for a 26.4% share, driven by ready-to-drink shots for athletes and casual gym-goers.
  • Cognitive & Stress Support is the fastest-growing application at a 12.9% CAGR.

• By End User

  • Adults represent a 43.5% share, reflecting everyday wellness routines.
  • Pregnant Women form the fastest-growing end-user group, valued at USD 2.71 billion in 2025.

• By Distribution Channel

  • Supermarkets/Hypermarkets retain a 38.9% share on the strength of shelf visibility and promotions.
  • Online Retail Stores expand at a 15.6% CAGR, the fastest channel in the Liquid Dietary Supplements Market.

• By Region

  • North America leads with a 38.2% share.
  • Asia-Pacific grows fastest at a 15.1% CAGR.

Market Size and Forecast (2021–2035)

Estimates for the Liquid Dietary Supplements Market combine bottom-up revenue modelling of finished liquid products (drops, shots, syrups, tonics and ready-to-drink formats) with top-down validation against national health-survey usage data, trade statistics and company filings[12]. Historical values are reconciled with reported category sales. Forecasts reflect regulatory timelines, channel shifts and demographic trends.
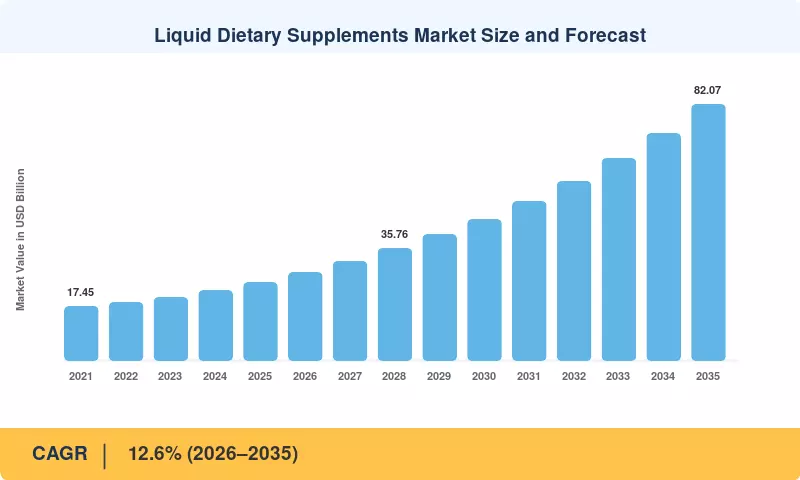
Liquid Dietary Supplements Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aging populations and swallowing difficulty +2.1% North America, Europe, Japan Long-term (≥4 yr)
Bioavailability and delivery-science innovation +1.9% Global Medium-term (2–4 yr)
E-commerce and subscription replenishment +1.7% North America, Asia-Pacific Short-term (≤2 yr)
Preventive health and immune awareness +1.4% Global Short-term (≤2 yr)
Sports and active-lifestyle RTD formats +1.2% North America, Europe Medium-term (2–4 yr)
Regulatory formalization in Asia +1.1% China, India, ASEAN Long-term (≥4 yr)


Aging Populations and Swallowing Difficulty

The World Health Organization projects that one in six people worldwide will be aged 60 or older by 2030 [8]. That demographic shift matters directly for format choice. A community-based study published in Dysphagia found swallowing difficulty in roughly 15% of older adults [9], a group that struggles with large tablets and softgels. Drinkable vitamin D, calcium and joint blends remove that barrier, which explains why geriatric demand is migrating to liquids faster than overall category growth would suggest.

Bioavailability and Delivery-Science Innovation

Liposomal encapsulation, micro-emulsions and free-fatty-acid omega-3 structures let brands make measurable absorption claims. A controlled study in Nutrition and Metabolic Insights reported significantly higher circulating vitamin C from liposomal delivery than from an unencapsulated equivalent [10]. These technologies support premium pricing of 30–60% over standard liquids. They also give mid-sized brands a defensible point of difference that is harder for private-label competitors to copy.

E-Commerce and Subscription Replenishment

E-commerce accounted for roughly 16% of total US retail sales in 2025, according to the US Census Bureau [11]. Liquid supplements suit subscription models well: consumption is predictable, bottles run out on a fixed cycle, and brands can bundle add-ons. Subscription programmes typically lift customer lifetime value by 25–40% for direct-to-consumer brands. They also generate first-party data that informs reformulation and targeting decisions.

Preventive Health and Immune Awareness

CDC data show that 57.6% of US adults used at least one supplement in the prior 30 days [12]. The pandemic converted occasional buyers into routine users, and immune-support liquids with zinc, vitamin D and elderberry kept much of that baseline. Seasonal demand peaks remain, but households now treat daily supplementation as preventive care. That behaviour favours easy-to-take liquid formats for the whole family.

Sports and Active-Lifestyle RTD Formats

The Sports & Fitness Industry Association counted 242 million active Americans in 2023, the highest level on record [13]. Ready-to-drink protein, electrolyte and pre-workout shots fit gym bags and commutes better than powders. Retailers are expanding chilled and ambient shot sets near checkouts. That placement captures impulse purchases from casual exercisers who would never buy a tub of powder.

Regulatory Formalization in Asia

China's SAMR filing route allows qualifying vitamin and mineral products to reach market in months rather than the two to three years typical of full registration [14]. India's FSSAI Health Supplements Regulations, 2022 set ingredient limits and labelling rules that give multinational brands the certainty needed to invest [4]. Together, these frameworks open two of the world's largest consumer bases to compliant liquid formats.

Restraints Impact Analysis

Restraint impacts below show the directional drag each factor exerts on the Liquid Dietary Supplements Market CAGR. They are qualitative estimates of relative weight, not additive deductions from the headline forecast.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Formulation stability and shelf-life limits -1.2% Global Medium-term (2–4 yr)
Claims scrutiny and regulatory fragmentation -1.0% Europe, North America Long-term (≥4 yr)
Packaging and logistics cost premium -0.8% Global Short-term (≤2 yr)
Adulteration and counterfeit products online -0.7% North America, Asia-Pacific Medium-term (2–4 yr)
Sugar and excipient concerns -0.6% Europe, North America Short-term (≤2 yr)


Formulation Stability and Shelf-Life Limits

Water-soluble vitamins degrade faster in liquid matrices than in dry tablets. Research in Food Chemistry shows vitamin C losses accelerating with temperature and dissolved oxygen [15]. Brands compensate with overages of 10–30%, which raises ingredient cost and complicates label-claim compliance. Probiotics face similar viability challenges without refrigeration or advanced encapsulation.

Claims Scrutiny and Regulatory Fragmentation

The European Union has authorized only around 260 general-function health claims, while thousands of submitted claims were rejected [16]. A claim permitted in the US under structure-function rules may be unusable in Europe. Multi-market brands therefore maintain separate labels and marketing copy, which raises compliance costs and slows rollouts.

Packaging and Logistics Cost Premium

Liquids are heavier and bulkier per dose than tablets, so freight costs per serving run materially higher. Glass bottles add breakage risk, and droppers require precision components. The EU Packaging and Packaging Waste Regulation, in force since February 2025, adds recyclability obligations that will push redesign spending across liquid SKUs [20].

Adulteration and Counterfeit Products Online

The U.S. Food and Drug Administration’s health fraud database includes over 1,000 contaminated items, many of which are offered online [18]. Branded tablets are harder to dilute or counterfeit than liquids, and marketplace listings make enforcement difficult. Every time one of these gets publicity, it undermines confidence in the industry, and real brands have to spend money on testing seals and anti-counterfeit packaging.


Sugar and Excipient Concerns

The WHO recommends limiting free sugars to below 10% of daily energy intake [17]. Many pediatric syrups and flavoured shots rely on sugar or artificial sweeteners for palatability. Parents and clinicians increasingly scrutinize these ingredients, so brands must invest in sugar-free taste-masking, which adds formulation complexity and cost.

Liquid Dietary Supplements Market Opportunities


Personalized Subscriptions and First-Party Data

Direct-to-consumer brands can use replenishment data as a commercial asset. Quiz-based personalization, AI-tuned delivery cycles and app-connected dose reminders allow companies to suggest targeted add-ons, and anonymized findings can improve retailer relationships. Brands that develop compliant data infrastructure can take a bigger slice of the internet growth mentioned and generate recurring revenue that investors appreciate highly.


Emerging-Market Penetration Through Low-Cost Formats

India, ASEAN and Brazil offer large underpenetrated consumer bases. Single-dose sachets and small bottles priced for daily-wage consumers lower the entry barrier, and FSSAI's 2022 framework gives formal legitimacy to compliant products [4]. India's 10.7%-10.8% CAGR signals the scale of the opening for brands that localize flavours and pricing.

Precision Dosing for Prenatal and Pediatric Users

Liquid prenatal lines use methylated folate and chelated iron to overcome common issues with tablet tolerability. Chewables can’t replicate milligram doses in pediatrics, but pipette droppers can. Repeat buy high trust sector with pharmacy channels and obstetric recommendations


Sustainable and Algal-Sourced Omega-3

Algal oils eliminate fish-sourcing issues and appeal to vegan consumers, while micro-emulsion processing removes the fishy aftertaste that has traditionally hampered liquid fish oil uptake. Brands that use sustainable sourcing and recyclable packaging can fulfill the 2030 packaging targets set by the EU [20] and gain premium retail space.


Institutional Elder-Care and Clinical Channels

Nursing homes, home-care providers and hospital discharge programs need sustenance for older people that is easier to swallow [9]. Clinical-backed liquid forms can access these procurement channels through medical-nutrition wholesalers. Contracts here are bigger and stickier than retail transactions.


Liquid Dietary Supplements Market Future Outlook


AI-Driven Personalization

Algorithms that combine wearable data, dietary logs and lab results will increasingly recommend tailored liquid blends. A recent market report estimates global consumer wellness spending at USD 1.8 trillion, with personalization among the fastest-growing interests . Liquids suit custom dosing because concentrations can be adjusted batch by batch, unlike pressed tablets.

Platform and Subscription Economics

Recurring revenue will define winners. Brands are converting one-time buyers into subscribers and expanding into adjacent functional beverages to raise basket size. Retail media networks and marketplace advertising will reward brands with strong reviews and conversion data.

Healthy-Aging Demand

Population aging is a structural tailwind. The WHO projects the global population aged 60 and older to reach 2.1 billion by 2050 [8]. Joint, cognitive and bone-health liquids designed for older consumers will gain shelf space, and institutional elder-care procurement will become a meaningful channel.

Sustainability and Packaging Compliance

Regulation (EU) 2025/40 sets recyclability requirements for all packaging placed on the EU market by 2030 [20]. Brands will shift toward recyclable PET, lighter glass and refill systems. Sustainability credentials, including algal sourcing and carbon disclosure, will increasingly influence retailer listings and investor screening.

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 38.2% share DTC subscriptions, sports shots, healthy aging
Europe USD 6.36 Billion Clinical claims, pharmacy channel, sustainable packaging
Asia-Pacific 15.1% CAGR Regulatory formalization, cross-border e-commerce, middle-class demand
South America 6.9% share Regulatory harmonization, pharmacy chains, direct selling
Middle East & Africa 11.4% CAGR Premium imports, wellness tourism, pharmacy expansion
Total USD 25.05 Billion —

Regional performance in the Liquid Dietary Supplements Market reflects differences in regulatory maturity, retail infrastructure and consumer health spending. North America leads in scale, while Asia-Pacific drives incremental growth.


North America

Country Key Metric Key Driver
US 86.4% of region DSHEA framework, mature DTC ecosystem
Canada USD 0.84 Billion Health Canada NHP licensing
Mexico 13.0% CAGR Pharmacy-chain expansion, rising obesity awareness


The US dominates regional demand thanks to the DSHEA framework, which allows structure-function claims without pre-market approval, and to high usage rates documented by the Council for Responsible Nutrition [5]. FDA's ingredient directory and 2024 NDI guidance have improved predictability for new liquid actives [2][6]. Canada's Natural Health Products Regulations require product licences, creating higher entry barriers but stronger consumer trust [23]. Mexico benefits from expanding pharmacy chains and government campaigns against diet-related disease.

Europe

Country Key Metric Key Driver
Germany 22.6% of region Strong pharmacy channel
UK USD 1.15 Billion Online retail, sports nutrition
France 10.9% CAGR Pharmacy and parapharmacy demand
Italy 11.4% of region Integratori culture, pharmacy sales
Spain USD 0.52 Billion Healthy-aging demand
Nordic Countries 11.3% CAGR Established liquid omega-3 tradition
Russia 6.8% of region Domestic production substitution
Rest of Europe USD 0.78 Billion Rising Central European spending


Europe's market operates under Directive 2002/46/EC, which harmonizes vitamin and mineral rules, while health claims must appear on the EU register [7][16]. Germany's pharmacies remain the most trusted channel for therapeutic liquids such as iron and vitamin D. The Nordic Countries have a long tradition of liquid cod-liver and fish oils, which supports premium omega-3 adoption. Post-Brexit, the UK maintains its own claims register, creating a separate compliance track.

Asia-Pacific

Country Key Metric Key Driver
China 34.2% of region SAMR filing pathway, cross-border e-commerce
India 17.8% CAGR FSSAI 2022 regulations, urban wellness demand
Japan USD 1.31 Billion Aging population, functional-claims system
South Korea 8.9% of region Health functional food culture
ASEAN 16.4% CAGR Rising incomes, online marketplaces
Rest of Asia-Pacific USD 0.58 Billion Australia's TGA-regulated market


China's dual registration-and-filing system has shortened launch timelines for common vitamin and mineral liquids [14]. India's FSSAI framework has attracted multinational investment [4]. Japan's Foods with Function Claims system was tightened in 2024 after a red yeast rice safety incident, raising compliance requirements for all producers [22]. ASEAN growth is propelled by mobile commerce platforms and young, health-conscious urban consumers.

South America

Country Key Metric Key Driver
Brazil 58.6% of region Anvisa RDC 243/2018 framework
Argentina 11.2% CAGR Pharmacy-led recovery
Rest of South America USD 0.43 Billion Direct-selling networks


Brazil's Anvisa RDC 243/2018 created a dedicated food-supplement category with ingredient lists and limits, replacing a fragmented framework [21]. Large pharmacy chains such as Raia Drogasil have expanded private-label liquid vitamins. Argentina's market is recovering from currency volatility, with pharmacies driving demand. Direct-selling companies remain important across smaller markets.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 27.5% of region Vision 2030 health programmes
UAE 13.6% CAGR Premium imports, wellness tourism
South Africa USD 0.26 Billion Complementary medicine regulation
Egypt 9.4% of region Local manufacturing, pharmacy reach
Rest of MEA 10.2% CAGR Urbanization, modern retail


Saudi Arabia's SFDA registration requirements shape product entry, while Vision 2030 health initiatives encourage preventive care [24]. The UAE serves as a regional hub for premium imported brands and wellness tourism. South Africa's SAHPRA is phasing in complementary medicine rules, which will raise standards. Egypt benefits from domestic pharmaceutical manufacturing capacity.

Liquid Dietary Supplements Market By Region, 2025-2035

Liquid Dietary Supplements Market Segmentation

By Ingredient Type

Segment Key Metric Primary Demand Driver
Vitamins & Minerals 29.9% share Daily wellness, deficiency correction
Botanicals/Herbals 21.3% share Ashwagandha, turmeric, adaptogens
Proteins & Amino Acids USD 3.18 Billion Sports recovery, healthy aging
Omega-3 & Fatty Acids 13.8% CAGR Cardiovascular, cognitive and prenatal claims
Probiotics 13.2% CAGR Ambient-stable encapsulation
Others 8.7% share Collagen, specialty actives


Within the Liquid Dietary Supplements Market, Vitamins & Minerals lead on the strength of daily multivitamin, vitamin D and iron use. Omega-3 & Fatty Acids grow fastest as micro-emulsion and algal oils remove taste barriers and support evidence-based heart and brain claims. Botanicals/Herbals benefit from solubilization aids that reduce sediment in curcumin and ashwagandha liquids. Probiotics gain ground as encapsulation keeps cultures viable without refrigeration, broadening retail placement.

By Application

Segment Key Metric Primary Demand Driver
Sports Nutrition 26.4% share RTD shots for athletes and gym-goers
Immune Health 22.1% share Zinc, vitamin D and elderberry tonics
Digestive Health USD 3.46 Billion Synbiotic shots, gut-health awareness
Cognitive & Stress Support 12.9% CAGR Nootropic demand from gamers and professionals
Energy & Weight Management 12.2% CAGR Metabolism and energy shots
Bone & Joint Health 9.8% share Collagen and vitamin K2 blends
Others USD 1.30 Billion Sleep, beauty and specialty uses


Sports Nutrition anchors application demand in the Liquid Dietary Supplements Market, aided by portable formats that appeal to both endurance athletes and casual exercisers. Cognitive & Stress Support is the fastest-growing area, supported by gaming communities, corporate wellness programmes and older adults concerned about memory. Immune Health keeps a stable seasonal base. Digestive Health shots increasingly link to app-based gut-health tracking.

By End User

Segment Key Metric Primary Demand Driver
Adults 43.5% share Everyday wellness, online purchasing
Geriatric Population USD 6.86 Billion Swallowing ease, joint and bone support
Pregnant Women USD 2.71 Billion Prenatal micronutrient adequacy
Children 18.3% share Taste-masked drops, precise dosing


Adults form the largest end-user group in the Liquid Dietary Supplements Market, buying mostly through e-commerce for everyday wellness. Pregnant Women are the fastest-growing group, as liquid prenatal formulas with methylated folate and gentle flavours ease nausea and improve compliance. The Geriatric Population values easy-to-swallow textures [9]. Children's products depend on pipette droppers and sugar-free taste-masking.

By Distribution Channel

Segment Key Metric Primary Demand Driver
Supermarkets/Hypermarkets 38.9% share Shelf visibility, promotions
Pharmacies USD 5.41 Billion Pharmacist trust, therapeutic lines
Online Retail Stores 15.6% CAGR Subscriptions, DTC platforms
Specialty Stores 12.3% share Sampling, expert advice
Other Channels USD 2.05 Billion Convenience stores, direct selling


Supermarkets/Hypermarkets remain the largest channel in the Liquid Dietary Supplements Market through broad shelf presence and promotions. Online Retail Stores grow fastest, as AI-driven subscription programmes adjust replenishment cycles and recommend add-ons [11]. Pharmacies sustain relevance for therapeutic liquids such as iron and high-dose vitamin D. Convenience stores are testing ambient energy shots near checkouts to capture impulse buys.

Competitive Benchmarking

The Liquid Dietary Supplements Market shows medium concentration. The top five players hold an estimated 28–32% combined share, and the Herfindahl-Hirschman Index is estimated at roughly 450–600, indicating a moderately fragmented field. Large consumer-health and nutrition companies compete with direct-selling networks and specialist liquid brands, while private labels pressure commoditized lines [25].

Company Est. Revenue Share Range Key Offerings for Liquid Dietary Supplements Market Strategic Positioning
Nestlé Health Science ~6–8% Liquid vitamins, protein drinks, Garden of Life liquids Science-led premium portfolio built through acquisitions
Abbott Laboratories ~5–7% Ensure and medical-nutrition liquids Clinical heritage and pharmacy reach [25]
Amway (Nutrilite) ~5–7% Liquid vitamins, botanical concentrates Direct-selling scale and plant-based sourcing
Herbalife Ltd. ~4–6% Herbal Aloe concentrate, protein drinks Distributor network and weight-management focus
Haleon plc ~3–5% Centrum and Emergen-C liquid lines Mass-market brand trust
Bayer AG ~3–5% One A Day and Berocca lines Pharmacy positioning and clinical claims
Glanbia plc ~2–4% Optimum Nutrition RTD shakes Sports-nutrition specialist
Pharmavite LLC ~2–3% Nature Made liquids and drops Retail scale and USP verification
NOW Foods ~1–3% Liquid vitamins, oils, extracts Value pricing and broad assortment
Nordic Naturals ~1–2% Liquid omega-3 and children's oils Purity testing and omega-3 expertise


Recent News & Developments


  • US FDA (March 2023): Launched an online ingredient directory consolidating agency actions on supplement ingredients, giving formulators faster visibility into compliance risks for new liquid actives. [6]
  • US FDA (March 2024): Finalized guidance on new dietary ingredient notification procedures and timeframes, clarifying the pathway for novel ingredients used in liquid formats. [2]
  • Japan Consumer Affairs Agency (September 2024): Tightened the Foods with Function Claims system after a red yeast rice safety incident, adding adverse-event reporting and manufacturing requirements. [22]
  • Council for Responsible Nutrition (October 2023): Published survey results showing 74% of US adults use supplements, confirming a broad demand base for liquid formats. [5]
  • European Union (February 2025): Regulation (EU) 2025/40 on packaging entered into force, setting 2030 recyclability targets that will shape liquid bottle and sachet design. [20]
  • Nestlé Health Science (2024): Continued portfolio reshaping toward premium, science-backed brands, signalling where large players expect liquid category value to concentrate.

Liquid Dietary Supplements Market Report Scope

Parameter Details
Market Scope Liquid Dietary Supplements Market by Ingredient Type, Application, End User, Distribution Channel and Region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 12.6% (2026–2035)
Market Size Checkpoints 2025: USD 25.05 Billion; 2026: USD 28.21 Billion; 2030: USD 45.34 Billion; 2035: USD 82.07 Billion
Fastest Growing Segments Omega-3 & Fatty Acids (13.8% CAGR); Cognitive & Stress Support (12.9% CAGR); Online Retail Stores (15.6% CAGR); Asia-Pacific (15.1% CAGR)
Companies Profiled Nestlé Health Science, Abbott Laboratories, Amway, Herbalife, Haleon, Bayer, Glanbia, Pharmavite, NOW Foods, Nordic Naturals
Valuation Currency USD Billion

FAQs

What should brands verify before choosing a contract manufacturer for the Liquid Dietary Supplements Market?
Confirm audited compliance with FDA's 21 CFR Part 111 rule and request matrix-specific stability data [3]. Liquids also need validated preservative-efficacy and microbial testing, capabilities many tablet-focused facilities lack.
How do liquid formats compare with gummies on dosing accuracy?
Liquids allow millilitre-level titration and avoid the potency drift common in heat-processed gummies. Sugar-free liquids also avoid the added sugar typical of gummy servings, an advantage for diabetic and pediatric users [17].
Are private-label products gaining ground in the Liquid Dietary Supplements Market?
Retailer brands are expanding in the Liquid Dietary Supplements Market's commoditized lines, such as vitamin D and iron drops, where price drives choice. Branded players keep the edge in clinically substantiated omega-3 and cognitive blends .
Which packaging choices best protect oxidation-sensitive liquids?
Amber glass or high-barrier PET with nitrogen headspace flushing slows oxidation of omega-3 and vitamin C actives [15]. Single-dose stick packs limit air exposure but raise recyclability questions under EU packaging rules [20].
What is the main hurdle for cross-border e-commerce entry into the Liquid Dietary Supplements Market?
Ingredient limits differ by country, so a compliant US formula may exceed Chinese or EU thresholds. China's cross-border channel offers a lighter route, but offline retail still requires SAMR approval [14].
How are investors valuing liquid supplement brands?
Acquirers in the Liquid Dietary Supplements Market pay premiums for recurring subscription revenue, clinical evidence and proprietary delivery technology. Brands dependent on paid social acquisition draw lower multiples as acquisition costs compress margins .
Do third-party certifications influence purchasing decisions?
Seals such as NSF Certified for Sport and USP Verified carry weight with athletes, pharmacists and institutional buyers. Many retailers now require independent contaminant testing before listing liquid SKUs [5].
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed nutritional science journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), National Institutes of Health (NIH) Office of Dietary Supplements, US Department of Agriculture (USDA) National Nutrient Database, World Health Organization (WHO) Global Nutrition Report, Centers for Disease Control and Prevention (CDC) National Health and Nutrition Examination Survey (NHANES), Council for Responsible Nutrition (CRN), International Food Information Council (IFIC), European Commission Directorate-General for Health and Food Safety, Food and Agriculture Organization (FAO) of the United Nations, Consumer Healthcare Products Association (CHPA), National Center for Complementary and Integrative Health (NCCIH), International Olympic Committee (IOC) Nutrition Consensus, Council of International Associations of Science Editors (CIASE), and national health ministry reports from key markets including Health Canada, Therapeutic Goods Administration (TGA) Australia, Pharmaceuticals and Medical Devices Agency (PMDA) Japan, and Food Safety and Standards Authority of India (FSSAI).

Consumption data, clinical safety studies, regulatory approval information, demographic trends, and market landscape analysis for protein supplements, vitamins and minerals, herbal supplements, omega fatty acids, amino acids, and other product categories were gathered from these sources.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, R&D directors, heads of regulatory affairs, and commercial directors from manufacturers of liquid dietary supplements, nutraceutical firms, and contract manufacturers were examples of supply-side sources. Registered dietitians, clinical nutritionists, pediatric nutrition consultants, sports medicine specialists, supermarket category managers, procurement leads from retail pharmacy chains, buyers of e-commerce platforms, and medical directors from health systems and wellness centers were among the demand-side sources. Market segmentation across product types (protein supplements, vitamins and minerals, herbal supplements, omega fatty acids, amino acids), end users (children, adults, pregnant women, athletes), distribution channels (online retailing, supermarkets, health stores, pharmacies), and formulations (ready-to-drink, concentrates, powdered) was validated by primary research. In addition to gathering information on formulation improvements, clean label adoption trends, pricing tactics, and e-commerce distribution dynamics, this method verified product pipeline timings.

Primary Respondent Breakdown:

By Company Tier Tier 1 (>USD 10B revenue) 38%

Tier 2 (USD 1B-10B revenue) 31%

By Designation C-level Executives 28%

Director Level 32%

Others (Managers, Specialists, Consultants) 40%

By Region North America 32%

Europe 29%

Asia-Pacific 31%

Rest of World (Latin America, Middle East & Africa) 8%


Market Size Estimation

Revenue mapping and consumption volume analysis were used to get the global market valuation. The methodology comprised:

Finding more than fifty-five major manufacturers in North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa

Product mapping for amino acids, omega fatty acids, protein supplements, vitamins and minerals, herbal supplements, and new functional categories

Analysis of reported and projected yearly revenues for liquid dietary supplement portfolios, such as powdered mixes that need liquid preparation, liquid concentrates, and ready-to-drink (RTD) formulations

Coverage of manufacturers that will account for 75–80% of the worldwide market share in 2024, including leading companies like Herbalife, Amway, GNC Holdings, Nestlé Health Science, Abbott Laboratories, Nature's Bounty, Bayer AG, and up-and-coming local experts

Extrapolation of segment-specific valuations across product types, end-user demographics, and distribution channels using top-down (manufacturer revenue validation, cross-referenced with retail audit data and e-commerce analytics) and bottom-up (consumption volume × Average Selling Price by country/region, adjusted for formulation type and distribution channel) methods

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















