Infrastructure Monitoring Market (2026 - 2035)

Infrastructure Monitoring Market Size, Share and Research Report By Technology (Wireless, Wired), By Application (Corrosion Monitoring, Crack/Strain Detection, Environmental & Seismic Monitoring, Other Applications), By End-User Industry (Civil Infrastructure, Energy & Utilities, Aerospace & Defense, Other End Users), By Deployment Model (On-Premise, Cloud/Edge), By Offering (Hardware, Software, Services) and By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Industry Forecast to 2035.

Forecast Period
2026-2035
CAGR
10.55%
2025 Market Size
USD 8.42 Billion
2035 Market Size
USD 22.96 Billion
Semiconductor & Electronics ● Updated September 10, 2026 Report ID: MRFR/SEM/4430-HCR | Pages: 100 | Author: Nirmit Biswas, Aarti Dhapte

Infrastructure Monitoring Market Summary

The Infrastructure Monitoring Market reached USD 8.42 Billion in 2025 and is projected to grow from USD 9.31 Billion in 2026 to USD 22.96 Billion by 2035, expanding at a 10.55% CAGR during the forecast period. This trajectory reflects a global pivot toward condition-based asset management, driven by the convergence of aging civil assets and aggressive public-sector stimulus. The U.S. Infrastructure Investment and Jobs Act alone earmarked over USD 110 Billion for surface transportation programs requiring real-time monitoring compliance, while the European Commission's revised Trans-European Transport Network (TEN-T) regulation mandates continuous surveillance of critical corridors by 2030 [1][2].

A sweeping technology transformation is reshaping the Infrastructure Monitoring Market as legacy manual inspection regimes give way to IoT-enabled sensor networks, cloud analytics, and AI-driven anomaly detection. Governments in North America, Japan, and the EU are channeling investment into digital-twin deployments that unify structural, geotechnical, and environmental data streams into single decision platforms. The U.S. Federal Highway Administration's Long-Term Bridge Performance Program, backed by more than USD 14 Billion in bridge-specific funding, exemplifies this shift [3]. Operators are abandoning fixed inspection cycles in favor of continuous, data-rich health assessments that lower lifecycle costs by 20–35% according to recent pilot evaluations [4].

North America held a commanding 31.8% share of the Infrastructure Monitoring Market in 2025, anchored by large-scale federal programs and early adoption of wireless sensor systems. Asia-Pacific is the fastest-growing region with a projected 12.75% CAGR, fueled by smart-city initiatives in China, India, and South Korea. Europe follows as the second-largest region at 25.3% share, where TEN-T corridor upgrades and seismic resilience mandates in Southern Europe sustain double-digit project pipelines. As climate risks intensify and inspection workforces thin, the Infrastructure Monitoring Market is poised to become a cornerstone of public asset management worldwide.


Key Report Takeaways

• By Technology

  • Wireless monitoring systems accounted for 65.8% of the Infrastructure Monitoring Market share in 2025, reflecting the rapid adoption of low-power wide-area networks across bridge and pipeline assets.
  • Wired monitoring continues to anchor high-precision applications in nuclear facilities and seismically active zones, though its growth rate trails the market average.

• By End-User Industry

  • Civil infrastructure held the dominant revenue position in the Infrastructure Monitoring Market, contributing roughly half of the total demand in 2025.
  • Energy and utilities end users are projected to register the second-fastest segment CAGR through 2035, driven by aging grid assets and offshore wind farm deployments.
  • Aerospace and defense spending on structural health assessment is accelerating as military operators extend airframe service lives beyond original design envelopes.

• By Region

  • North America led the Infrastructure Monitoring Market with 31.8% share in 2025, powered by federal bridge and pipeline programs.
  • Asia-Pacific is advancing at a 12.75% CAGR, the fastest among all regions through 2035.
  • Europe accounted for 25.3% of total revenue, with Germany, the UK, and France anchoring demand.


Market Size and Forecast (2021–2035)

Market Research Future's sizing methodology integrates bottom-up revenue analysis across hardware, software, and service verticals, validated against top-down macroeconomic benchmarks from the World Bank, OECD infrastructure spending indices, and national transportation budgets. Historical data (2021–2024) draws from company filings and procurement databases; the forecast (2026–2035) applies a calibrated compound growth model adjusted for policy cycles, technology cost curves, and regional capex plans.
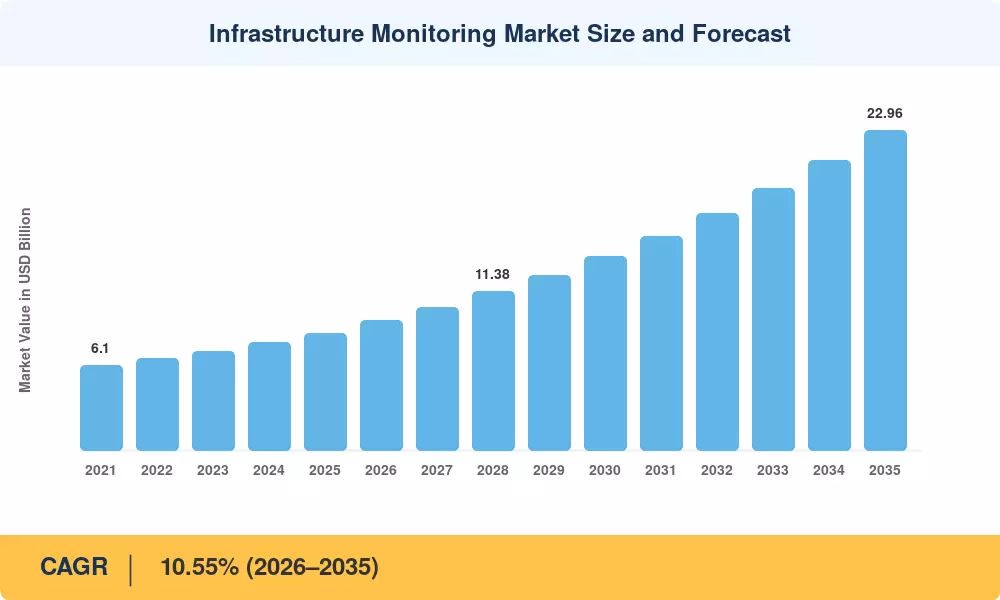
Infrastructure Monitoring Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Federal bridge and highway rehabilitation mandates +2.0 North America Short-term (≤2 yr)
Falling MEMS and wireless sensor unit costs +1.8 Global Medium-term (2–4 yr)
Smart-city IoT platform proliferation +1.5 Asia-Pacific, Europe Medium-term (2–4 yr)
Climate adaptation and seismic resilience regulation +1.4 Europe, APAC Long-term (≥4 yr)
Energy grid modernization and offshore wind growth +1.2 Europe, North America Medium-term (2–4 yr)
Insurance-linked risk modeling requirements +0.9 North America, Europe Long-term (≥4 yr)
Military airframe life-extension programs +0.7 North America, Europe Short-term (≤2 yr)


Federal Bridge and Highway Rehabilitation Mandates

The U.S. Infrastructure Investment and Jobs Act dedicated over USD 40 Billion specifically to bridge repair and replacement, with monitoring provisions written into grant eligibility criteria. States applying for National Bridge Inspection Standards funding must now demonstrate deployment of continuous monitoring on structures rated below a condition score of 5 [1]. Canada's National Trade Corridors Fund similarly ties disbursements to real-time surveillance of critical freight crossings, injecting approximately CAD 4.6 Billion into corridor upgrades through 2028 [14]. These mandates convert discretionary monitoring spend into compliance-driven procurement.

Falling Sensor Unit Costs

Average unit costs for MEMS-based accelerometers and strain gauges dropped roughly 38% between 2019 and 2024, according to industry component pricing trackers [6]. That cost trajectory has made dense sensor arrays economically viable for medium-span bridges and secondary road assets that were previously inspected on fixed schedules. The Infrastructure Monitoring Market benefits directly: lower hardware costs expand the addressable asset base from marquee projects to everyday municipal infrastructure, lifting total addressable volume significantly.

Smart-City IoT Platform Proliferation

China's "New Infrastructure" initiative budgeted over CNY 3.4 Trillion through 2025 for digital infrastructure, with structural monitoring embedded in urban rail, tunneling, and high-rise construction projects [7]. India's Smart Cities Mission Phase 2 extends IoT integration to 100 cities, while South Korea's Digital New Deal channels KRW 58.2 Trillion toward data-centric infrastructure governance [15]. These programs are pulling the Infrastructure Monitoring Market into broader urban data ecosystems rather than standalone project-level deployments.

Climate Adaptation and Seismic Resilience Regulation

The EU's revised Critical Entities Resilience Directive requires operators of essential infrastructure to implement continuous monitoring for climate and seismic risks by 2028 [10]. Japan's updated National Resilience Plan allocates JPY 15 Trillion for disaster-proofing aging bridges, tunnels, and port facilities, with sensor-based surveillance mandatory for structures older than 50 years [16]. These regulatory frameworks create durable, multi-decade demand floors for the Infrastructure Monitoring Market.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High upfront installation and commissioning costs –1.3 Global Short-term (≤2 yr)
Interoperability gaps between legacy wired and new wireless systems –1.0 North America, Europe Medium-term (2–4 yr)
Shortage of trained structural health engineers –0.8 Global Long-term (≥4 yr)
Data security and privacy concerns for critical assets –0.6 North America, Europe Medium-term (2–4 yr)
Fragmented municipal procurement frameworks –0.5 Emerging Markets Long-term (≥4 yr)


High Upfront Installation and Commissioning Costs

The cost of a full sensor network on a major bridge structure might range from USD 1.2 Million to USD 4.5 Million depending on the span length, hazard profile, and data communication needs [17]. These capital outlays compete with the immediate repair budgets of cash-starved municipalities, which hold over 60% of the U.S. bridge inventory. Secondary and tertiary asset tiers will penetrate the Infrastructure Monitoring Market at a slower pace until leasing and monitoring-as-a-service models develop to facilitate the transition of spending from capex to opex.


Interoperability and Legacy Integration Challenges

Many assets developed before 2010 include inbuilt wired sensor networks that use proprietary protocols from the original equipment maker. Retrofitting wireless overlays to such systems requires new gateway hardware and middleware that can extend project schedules by 6–12 months [18]. Standards bodies like IEEE and the Open Geospatial Consortium are developing consistent data schemas, but full protocol harmonization is unlikely before 2029, limiting short term upgrade cycles in the Infrastructure Monitoring Market.


Infrastructure Monitoring Market Opportunities

Monitoring-as-a-Service for Municipal Assets

Small and mid-size towns have the bulk of aged bridge and culvert inventory, but lack capital budgets for extensive sensor deployments. This latent demand can be turned into a recurrent revenue stream through subscription-based monitoring services that combine hardware installation, cloud analytics and quarterly condition reports into a package. Early movers such as Nova Metrix and Sixense have piloted municipal MaaS contracts in the North Eastern US and France, respectively [22].


AI-Driven Predictive Analytics Platforms

By marrying machine learning with constant sensor data, operators can see micro-crack propagation, corrosion start and load abnormalities months before any visible degradation occurs. Platforms that integrate AI inference with engineering simulation models can save unplanned maintenance costs by 25–40% [4]. This analytics layer is a high-margin software potential in the larger Infrastructure Monitoring Market.


Emerging-Market Pipeline and Rail Expansion

Latin America, the Middle East, and Sub-Saharan Africa are entering an infrastructure buildout phase where monitoring can be designed in from day one rather than retrofitted. Brazil's PAC program includes monitoring provisions for 7,500 km of new rail track, while Saudi Arabia's NEOM project specifies continuous structural surveillance for all transport corridors [23]. These greenfield deployments present faster sales cycles and higher attach rates than retrofit markets.

Data Monetization Through Insurance and ESG Reporting

Continuous monitoring data has value beyond operations. Insurers are building parametric products around real-time structural health indices, and ESG frameworks increasingly require asset-level resilience disclosure [12]. Infrastructure owners who share anonymized monitoring data with reinsurers and rating agencies can negotiate premium reductions of 10–18%, creating a financial feedback loop that subsidizes monitoring investment.

Offshore Wind and Subsea Asset Monitoring

The global offshore wind pipeline exceeds 380 GW through 2035, and every turbine foundation, subsea cable, and transition piece requires corrosion and fatigue monitoring [11]. This single vertical could add over USD 1.5 Billion in cumulative monitoring spend by 2032, making it one of the fastest-emerging opportunity pockets within the Infrastructure Monitoring Market.


Infrastructure Monitoring Market Future Outlook

AI and Autonomous Inspection Integration

By 2030, AI-powered anomaly detection will handle an estimated 60–70% of routine structural assessments currently performed by human inspectors, according to U.S. DOT research projections [3]. The Infrastructure Monitoring Market will shift from selling sensors to selling insight, with platform economics favoring vendors that integrate drone-captured imagery, sensor telemetry, and machine-learning diagnostics into unified dashboards.

Digital-Twin Mandates and Platform Economics

Multiple jurisdictions are moving toward mandatory digital-twin representation of critical assets. The UK's National Digital Twin Programme and Singapore's Virtual Singapore initiative signal that regulatory requirements for real-time asset replicas will expand globally by 2032 [8]. Vendors that control the digital-twin layer will capture recurring software revenue, fundamentally shifting the Infrastructure Monitoring Market's margin profile from hardware-heavy to software-centric.

ESG and Climate Disclosure as Demand Catalysts

The International Sustainability Standards Board's (ISSB) climate disclosure framework now requires asset-level resilience reporting, pushing infrastructure operators to invest in monitoring systems that generate auditable data [9]. By 2035, an estimated 40% of the Infrastructure Monitoring Market revenue could be tied to compliance-driven deployments rather than purely operational efficiency gains.

Electrification and Energy Transition Infrastructure

The IEA projects global investment in electricity grids to exceed USD 600 Billion annually by 2030 [11]. Every new transmission tower, substation, and offshore wind foundation requires lifecycle monitoring. This electrification supercycle will pull the Infrastructure Monitoring Market into energy verticals at a pace that rivals traditional civil infrastructure demand.


Infrastructure Monitoring Market Segmentation

By Technology

Segment Key Metric Primary Demand Driver
Wireless 65.8% share (2025) Low-power sensor proliferation and retrofit ease
Wired 10.18% CAGR (2026–2035) High-precision nuclear and seismic applications


Wireless monitoring dominates the Infrastructure Monitoring Market because retrofit deployments on existing structures overwhelmingly favor cable-free solutions. LPWAN protocols such as LoRaWAN and NB-IoT have reduced per-node communication costs below USD 5 annually, making dense deployments viable even for secondary-road bridges. Wired systems retain critical roles in nuclear containment monitoring and tunnel convergence measurement, where electromagnetic interference or explosion-proof requirements rule out wireless alternatives. The wired segment's growth rate, while lower, reflects steady replacement cycles in high-value industrial assets.

By Application

Segment Key Metric Primary Demand Driver
Corrosion Monitoring USD 2.38 Billion (2025) Pipeline integrity and coastal bridge protection
Crack/Strain Detection 10.85% CAGR Bridge load rating and building settlement tracking
Environmental & Seismic Monitoring 13.15% CAGR Climate adaptation mandates and earthquake codes
Other Applications USD 1.12 Billion (2025) Vibration, tilt, and temperature surveillance


Corrosion monitoring commands the largest application-level revenue within the Infrastructure Monitoring Market, driven by the massive installed base of oil and gas pipelines and coastal bridge decks. Environmental and seismic monitoring is the fastest-growing application, propelled by climate resilience mandates in Japan, Southern Europe, and the western United States.

By End-User Industry

Segment Key Metric Primary Demand Driver
Civil Infrastructure 50.2% share (2025) Bridge, tunnel, and dam surveillance
Energy & Utilities 12.82% CAGR Grid modernization and offshore wind
Aerospace & Defense USD 0.92 Billion (2025) Airframe life extension and runway monitoring
Other End Users 9.15% CAGR Mining, water treatment, and port assets


Civil infrastructure's dominant position in the Infrastructure Monitoring Market stems from the sheer volume of bridge, tunnel, and dam assets requiring surveillance globally. The American Society of Civil Engineers estimates over 46,000 U.S. bridges are rated structurally deficient, creating a persistent procurement pipeline [4]. Energy and utilities end users represent the fastest growth vector, as offshore wind operators and transmission grid managers embed monitoring into capital projects from commissioning onward.

By Deployment Model

Segment Key Metric Primary Demand Driver
On-Premise 72.0% share (2025) Data sovereignty for defense and nuclear assets
Cloud/Edge 14.05% CAGR Scalability and remote multi-site management


On-premise deployments dominate the Infrastructure Monitoring Market today, largely because defense installations and critical energy facilities mandate local data residency. Cloud and edge solutions are gaining rapidly; however, as municipalities and commercial operators seek centralized dashboards that aggregate data from hundreds of distributed assets without on-site server infrastructure.

By Offering

Segment Key Metric Primary Demand Driver
Hardware USD 3.92 Billion (2025) Sensor nodes, data acquisition units, gateways
Software 12.45% CAGR Analytics platforms and visualization tools
Services USD 1.85 Billion (2025) Installation, calibration, and managed monitoring


Hardware still constitutes the largest offering category in the Infrastructure Monitoring Market, though software is growing fastest as vendors shift toward platform-based recurring revenue models. Services revenue benefits from the increasing complexity of multi-hazard deployments, where specialized engineering expertise is required for installation design and data interpretation.


Regional Market Share Analysis

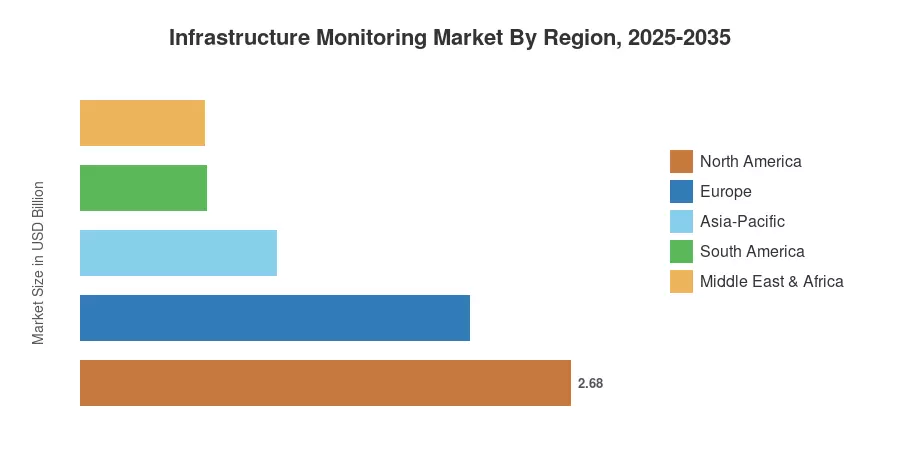
Region Key Metric Primary Investment Themes
North America 31.8% share (2025) Federal bridge rehabilitation, pipeline integrity
Europe 25.3% share (2025) TEN-T corridor upgrades, seismic resilience
Asia-Pacific 12.75% CAGR (2026–2035) Smart-city IoT, high-speed rail expansion
South America USD 0.69 Billion (2025) PAC infrastructure program, mining corridors
Middle East & Africa USD 0.68 Billion (2025) Mega-project surveillance, oil & gas pipelines
Total USD 8.42 Billion (2025)

The Infrastructure Monitoring Market exhibits clear regional stratification. North America and Europe dominate installed-base revenue while Asia-Pacific closes the gap rapidly through government-led smart-city and resilience programs.


North America

Country Key Metric Key Driver
US 72.4% of regional share IIJA bridge and highway monitoring mandates [1]
Canada 17.8% of regional share National Trade Corridors Fund [14]
Mexico 9.8% of regional share Rail modernization under T-MEC commitments


The United States accounts for the overwhelming majority of the North American Infrastructure Monitoring Market revenue, buoyed by the National Bridge Inspection Standards overhaul and dedicated federal grants that require continuous surveillance as a disbursement condition. Canada's corridor-centric approach targets freight chokepoints along the Trans-Canada Highway and St. Lawrence Seaway. Mexico's monitoring adoption is earlier-stage but growing as public-private concession agreements for toll roads begin incorporating sensor-based condition clauses.

Europe

Country Key Metric Key Driver
Germany 11.2% CAGR Autobahn bridge renewal program [2]
UK USD 0.42 Billion (2025) National Highways digital roads strategy
France 10.8% CAGR Post-Genoa mandate for viaduct monitoring
Italy USD 0.28 Billion (2025) Seismic retrofit requirements
Spain 9.4% CAGR High-speed rail corridor expansion
Nordic Countries USD 0.19 Billion (2025) Arctic climate resilience programs
Russia 8.6% CAGR Pipeline integrity along Siberian corridors
Rest of Europe USD 0.21 Billion (2025) EU cohesion funding allocations


Germany's bridge inventory crisis — with over 4,000 structures rated as critically deficient by the Federal Highway Research Institute — places it among Europe's fastest-growing markets for the Infrastructure Monitoring Market. The Genoa bridge collapse in 2018 triggered pan-European legislative action, with France and Italy implementing mandatory continuous monitoring for viaducts exceeding 100-meter spans. The UK's National Highways organization has committed GBP 1.2 Billion to its Digital Roads program through 2030, embedding sensor arrays into motorway and tunnel assets.

Asia-Pacific

Country Key Metric Key Driver
China 34.2% of regional share New Infrastructure initiative and high-speed rail
India 13.6% CAGR Smart Cities Mission Phase 2 [15]
Japan USD 0.51 Billion (2025) National Resilience Plan [16]
South Korea 12.9% CAGR Digital New Deal infrastructure governance
ASEAN USD 0.24 Billion (2025) Urban transit and flood resilience projects
Rest of Asia-Pacific 11.4% CAGR Mining and hydroelectric dam monitoring


Asia-Pacific represents the highest growth trajectory within the Infrastructure Monitoring Market. China's railway network alone exceeds 42,000 km of high-speed track, all requiring continuous structural surveillance, while India's Phase 2 smart-city investments embed monitoring into over 100 urban centers. Japan's aggressive stance on disaster resilience — reflected in JPY 15 Trillion in national resilience spending — ensures sustained demand for seismic and flood monitoring solutions on bridges and coastal defenses.

South America

Country Key Metric Key Driver
Brazil 58.3% of regional share PAC program rail and highway spending [23]
Argentina 22.1% of regional share Buenos Aires metro and highway upgrades
Rest of South America 19.6% of regional share Mining infrastructure and dam safety


Brazil's Growth Acceleration Program (PAC) provides the primary demand floor, with monitoring requirements attached to new rail and highway concessions. Argentina's metropolitan transit overhauls and Andean mining corridor expansion offer secondary growth pockets for the Infrastructure Monitoring Market.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 32.5% of regional share NEOM and Vision 2030 mega-projects [23]
UAE 26.8% of regional share Expo legacy infrastructure and rail projects
South Africa 18.4% of regional share Mining asset management and port modernization
Egypt 12.7% of regional share New Administrative Capital and Suez corridor
Rest of MEA 9.6% of regional share Oil and gas pipeline integrity programs


Saudi Arabia and the UAE anchor Middle East demand through mega-project surveillance requirements. NEOM's specifications mandate continuous structural monitoring across all built assets, creating a greenfield testbed for the Infrastructure Monitoring Market. South Africa's mining sector and Egypt's ambitious capital relocation project add incremental demand layers across the continent.


Infrastructure Monitoring Market By Region, 2025-2035

Competitive Benchmarking

The Infrastructure Monitoring Market exhibits medium concentration, with an estimated top-five share of 28–35% and a Herfindahl-Hirschman Index below 800. Incumbents compete on platform breadth and installed-base relationships, while specialist firms differentiate through application-specific expertise in seismic, corrosion, or geotechnical monitoring. Recent M&A activity — including platform acquisitions by large industrial conglomerates — signals consolidation pressure that will intensify through 2028.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Siemens AG ~7–10% End-to-end IoT platforms, cloud analytics Broad industrial portfolio, digital-twin integration
Honeywell International ~6–9% Connected sensors, building management systems Cross-vertical data platform, energy & defense
National Instruments (NI) ~5–8% Data acquisition hardware, test/measurement software High-precision engineering, OEM partnerships
Campbell Scientific ~4–6% Environmental sensors, dataloggers Research-grade accuracy, geotechnical niche
Nova Metrix (Geocomp) ~3–5% Wireless sensor networks, geotechnical monitoring Municipal bridge and dam specialization
Geokon ~3–5% Vibrating-wire sensors, readout systems Deep expertise in dam and tunnel monitoring
RST Instruments ~2–4% Geotechnical and structural sensors Mining and tunneling applications
Sixense (VINCI Group) ~2–4% Structural monitoring services, cloud platforms European infrastructure concessions integration
James Fisher Strainstall ~2–3% Load monitoring, offshore structural health Maritime and offshore energy specialization
Screening Eagle Technologies ~2–3% NDT hardware, AI inspection software Digital inspection workflow unification


Recent News & Developments

  • Siemens (April 2025) launched a $190 million plant in Fort Worth to produce AI-ready electrical equipment for local data-center and infrastructure clients.


Infrastructure Monitoring Market Report Scope

Parameter Detail
Market Scope Global Infrastructure Monitoring Market across hardware, software, and services
Study Period 2021–2035
Historical Period 2021–2024
Base Year 2025
Forecast Period 2026–2035
CAGR 10.55% (2026–2035)
Market Size (2025) USD 8.42 Billion
Market Size (2035) USD 22.96 Billion
Fastest Growing Segment Environmental & Seismic Monitoring (by application); Cloud/Edge (by deployment)
Companies Profiled 10+ including Siemens, Honeywell, National Instruments, Campbell Scientific, Nova Metrix, Geokon, RST Instruments, Sixense, Strainstall, Screening Eagle
Valuation Currency USD Billion

FAQs

How does monitoring-as-a-service pricing compare with outright sensor system purchase for a mid-size bridge?
MaaS contracts typically cost USD 35,000–60,000 per year per structure, compared with USD 1.5–3.0 Million in upfront purchase costs. Over a ten-year period, MaaS is roughly 20–30% more expensive in total but eliminates capital outlay barriers for municipalities [17].
Which data communication protocol is gaining the most traction for remote Infrastructure Monitoring Market deployments?
NB-IoT and LoRaWAN are leading adoption for remote sites due to ultra-low power consumption and carrier-grade reliability. NB-IoT holds an edge where cellular coverage exists; LoRaWAN dominates in off-grid and mountainous terrain [6].
What role do insurance underwriters play in accelerating Infrastructure Monitoring Market adoption?
Insurers increasingly offer 10–18% premium reductions for assets with continuous monitoring, creating direct financial incentives. Parametric insurance products are emerging that trigger payouts based on real-time sensor thresholds rather than post-event damage assessments [12].
How are cybersecurity concerns shaping procurement standards in the Infrastructure Monitoring Market?
NIST's SP 800-82 Rev 3 now covers industrial monitoring networks, requiring encrypted data transmission and role-based access controls. Procurement contracts for federal assets mandate FIPS 140-2 validated encryption modules [20].
What differentiates fiber optic sensing from conventional electrical sensors in corrosion monitoring applications?
Fiber optic sensors provide distributed measurement along entire cable lengths rather than point-by-point readings, enabling earlier detection of corrosion onset. They also offer immunity to electromagnetic interference, making them preferred for high-voltage environments [18].
How do building information modeling platforms integrate with the Infrastructure Monitoring Market ecosystem?
BIM platforms serve as the geometric backbone for sensor placement planning and data visualization. Real-time sensor feeds are overlaid onto 3D BIM models, enabling operators to locate anomalies spatially rather than interpreting abstract data tables [8].
What minimum sensor density do current standards recommend for highway bridge monitoring in the Infrastructure Monitoring Market?
FHWA guidelines recommend one tri-axial accelerometer per 15-meter span segment plus strain gauges at critical load-transfer points. Dense networks require 40–80 sensor nodes for a typical 200-meter span [3].    
Author
Author
Author Profile
Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author
Co-Author Profile
Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technical standards publications, industry associations, and authoritative engineering organizations. Key sources included the US Department of Transportation (DOT) Federal Highway Administration, National Institute of Standards and Technology (NIST), American Society of Civil Engineers (ASCE), Institute of Electrical and Electronics Engineers (IEEE), International Organization for Standardization (ISO), US Department of Energy (DOE) Office of Electricity, European Committee for Standardization (CEN), International Electrotechnical Commission (IEC), US Bureau of Transportation Statistics, World Bank Infrastructure Data, International Energy Agency (IEA), US Occupational Safety and Health Administration (OSHA), European Union Agency for Cybersecurity (ENISA), National Transportation Safety Board (NTSB), and national infrastructure reports from key markets including China's Ministry of Transport, India's Ministry of Road Transport and Highways, and Japan's Ministry of Land, Infrastructure, Transport and Tourism. These sources were used to collect infrastructure investment statistics, regulatory compliance data, structural health monitoring standards, IoT adoption trends, and technology landscape analysis for wireless monitoring systems, wired sensor networks, software platforms, hardware components, and professional services across civil infrastructure, energy, aerospace & defense, and mining sectors.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. CEOs, CTOs, VPs of engineering, heads of IoT solutions, and business development directors from companies that provide infrastructure monitoring technology, sensors, and industrial automation were examples of supply-side sources. Demand-side sources included procurement leads from government transportation agencies, energy companies, and smart city authorities; chief engineers; project directors from civil engineering firms; utilities operations managers; defense system integrators; mining operations executives; and infrastructure asset managers. Market segmentation, technological roadmap dates, and information on system integration trends, procurement cycles, and regulatory compliance needs were all confirmed by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installation base analysis. The methodology included:

Identification of 50+ key technology providers and system integrators across North America, Europe, Asia-Pacific, and Latin America

Product mapping across wireless sensor networks, wired monitoring systems, predictive analytics software, IoT hardware platforms, and professional services

Analysis of reported and modeled annual revenues specific to infrastructure monitoring portfolios

Coverage of manufacturers and service providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (deployment volume × ASP by region/sector) and top-down (technology provider revenue validation) approaches to derive segment-specific valuations for civil infrastructure, energy utilities, aerospace & defense, and mining applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















