Industrial Waste Management Market (2026 - 2035)

ID: MRFR/Equip/5027-HCR 100 Pages Priya Nagrale Last Updated: September 15, 2026
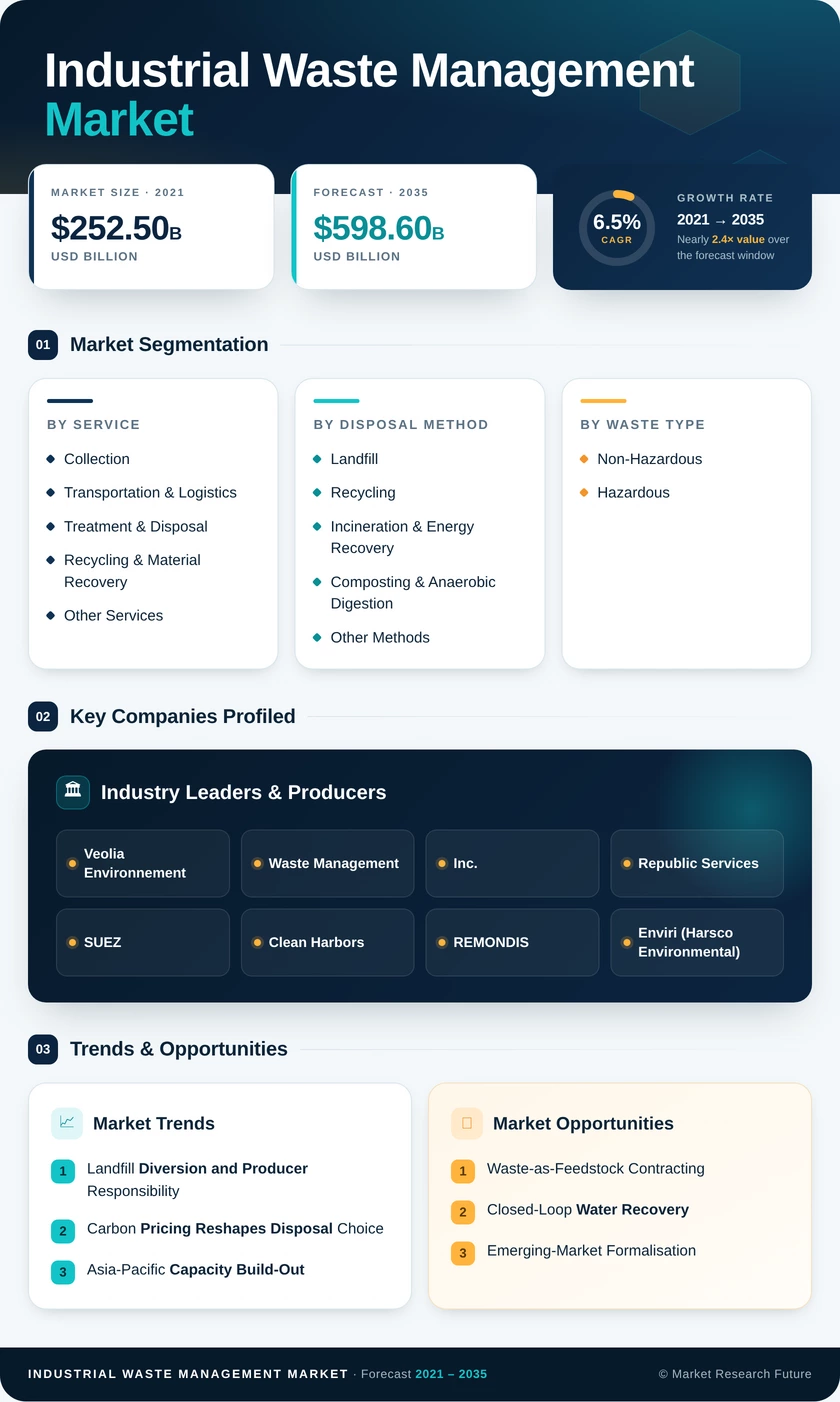
Industrial Waste Management Market Research Report By Service (Collection, Transportation & Logistics, Treatment & Disposal, Recycling & Material Recovery, Other Services), By Disposal Method (Landfill, Recycling, Incineration & Energy Recovery, Composting & Anaerobic Digestion, Other Methods), By Waste Type (Non-Hazardous, Hazardous), By Industry (Chemicals & Petrochemicals, Oil & Gas, Manufacturing, Construction & Demolition, Food & Beverage, Mining & Metallurgy, Other Industries) - Forecast to 2035
Industrial Waste Management Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.5%
2025 Market SizeUSD 318.9 Billion
2035 Market SizeUSD 598.6 Billion
Key Players
Veolia Environnement
Waste Management, Inc.
Republic Services
SUEZ
Clean Harbors
REMONDIS
Opportunities
  • Waste-as-Feedstock Contracting
  • Closed-Loop Water Recovery
  • Emerging-Market Formalisation
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
    4. 1.4 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Service | |
    2. 2.2 By Sector | |
    3. 2.3 By Region | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Estimate (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Landfill Diversion and Producer Responsibility | |
    2. 4.2 Carbon Pricing Reshapes Disposal Choice | |
    3. 4.3 Asia-Pacific Capacity Build-Out | |
    4. 4.4 Digital Chain-of-Custody | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Capital Intensity Slows Deployment | |
    2. 5.2 Permitting Friction | |
    3. 5.3 Commodity Price Swings | |
  6. 6 Opportunity Analysis | |
    1. 6.1 Waste-as-Feedstock Contracting | |
    2. 6.2 Closed-Loop Water Recovery | |
    3. 6.3 Emerging-Market Formalisation | |
    4. 6.4 Data Monetisation and Compliance Platforms | |
    5. 6.5 Decommissioning and Legacy Site Remediation | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Sorting and Plant Intelligence | |
    2. 8.2 Platform Economics in Service Delivery | |
    3. 8.3 Energy Recovery Meets Carbon Accounting | |
    4. 8.4 Disclosure Discipline | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Service | | |
      1. 9.1.1 Collection | | |
      2. 9.1.2 Transportation & Logistics | | |
      3. 9.1.3 Treatment & Disposal | | |
      4. 9.1.4 Recycling & Material Recovery | | |
      5. 9.1.5 Other Services | |
    2. 9.2 By Disposal Method | | |
      1. 9.2.1 Landfill | | |
      2. 9.2.2 Recycling | | |
      3. 9.2.3 Incineration & Energy Recovery | | |
      4. 9.2.4 Composting & Anaerobic Digestion | | |
      5. 9.2.5 Other Methods | |
    3. 9.3 By Waste Type | | |
      1. 9.3.1 Non-Hazardous | | |
      2. 9.3.2 Hazardous | |
    4. 9.4 By Industry | | |
      1. 9.4.1 Chemicals & Petrochemicals | | |
      2. 9.4.2 Oil & Gas | | |
      3. 9.4.3 Manufacturing | | |
      4. 9.4.4 Construction & Demolition | | |
      5. 9.4.5 Food & Beverage | | |
      6. 9.4.6 Mining & Metallurgy | | |
      7. 9.4.7 Other Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Veolia Environnement | | |
      2. 10.3.2 Waste Management, Inc. | | |
      3. 10.3.3 Republic Services | | |
      4. 10.3.4 SUEZ | | |
      5. 10.3.5 Clean Harbors | | |
      6. 10.3.6 REMONDIS | | |
      7. 10.3.7 Enviri (Harsco Environmental) | | |
      8. 10.3.8 Stericycle | | |
      9. 10.3.9 Reworld | | |
      10. 10.3.10 Cleanaway Waste Management | | |
      11. 10.3.11 Séché Environnement | | |
      12. 10.3.12 Daiseki Co., Ltd. | |
  11. 11 Recent News & Developments (2023–2025) | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Conversion | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Industrial Waste Management Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Industrial Waste Management Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Service, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Disposal Method, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by Waste Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Market Size, by Industry, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Market Size, by Service and Waste Type, 2021–2035 (USD Billion) | |
  30. TABLE 16 Europe Market Size, by Disposal Method and Industry, 2021–2035 (USD Billion) | |
  31. TABLE 17 Asia-Pacific Market Size, by Service and Industry, 2021–2035 (USD Billion) | |
  32. TABLE 18 South America Market Size, by Disposal Method, 2021–2035 (USD Billion) | |
  33. TABLE 19 Middle East & Africa Market Size, by Waste Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Competitive Benchmarking Matrix, 2026 | |
  35. TABLE 21 Company Profiles — Key Players | |
  36. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 | |
  37. TABLE 23 Report Scope & Methodology Summary | |
  38. TABLE 24 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  39. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Overview | |
  40. FIGURE 2 Industry Value Chain Analysis | |
  41. FIGURE 3 Porter's Five Forces Analysis | |
  42. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  43. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  44. FIGURE 6 Market Share by Service, 2025 vs 2035 (%) | |
  45. FIGURE 7 Market Share by Disposal Method, 2025 vs 2035 (%) | |
  46. FIGURE 8 Market Share by Waste Type, 2025 (%) | |
  47. FIGURE 9 Market Share by Industry, 2025 (%) | |
  48. FIGURE 10 Regional Market Share, 2025 (%) | |
  49. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) | |
  50. FIGURE 12 Country-Level Share within Asia-Pacific, 2025 (%) | |
  51. FIGURE 13 Country-Level Share within Europe, 2025 (%) | |
  52. FIGURE 14 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  53. FIGURE 15 Strategic Positioning Map of Leading Providers

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ServiceCollection; Transportation & Logistics; Treatment & Disposal; Recycling & Material Recovery; Other ServicesTreatment & DisposalRecycling & Material Recovery
By Disposal MethodLandfill; Recycling; Incineration & Energy Recovery; Composting & Anaerobic Digestion; Other MethodsLandfillComposting & Anaerobic Digestion
By Waste TypeNon-Hazardous; HazardousNon-HazardousHazardous
By IndustryChemicals & Petrochemicals; Oil & Gas; Manufacturing; Construction & Demolition; Food & Beverage; Mining & Metallurgy; Other IndustriesChemicals & PetrochemicalsFood & Beverage
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificMiddle East & Africa


Market Segmentation Overview

By Service

Sub-SegmentKey Trend
CollectionSource segregation at the generator site becomes contractual, not optional
Transportation & LogisticsRoute optimisation and fuel volatility push toward regional consolidation
Treatment & DisposalPermitted capacity scarcity sustains pricing power
Recycling & Material RecoveryContracted offtake replaces spot commodity sales
Other ServicesCompliance advisory grows with mandatory sustainability disclosure


Service mix is shifting from moving material to processing it. Providers that own permitted treatment assets convert collection contracts into captive feedstock, which is the clearest margin lever available in the current structure.

By Disposal Method

Sub-SegmentKey Trend
LandfillShare erodes steadily in tax-heavy jurisdictions
RecyclingPurity certification determines premium pricing
Incineration & Energy RecoveryCarbon accounting rules decide post-2028 economics
Composting & Anaerobic DigestionOrganic diversion mandates widen the addressable base
Other MethodsSpecialty destruction expands with new contaminant classifications


Method mix responds faster to policy than to technology. Where disposal is taxed and reported, recovery routes gain share within two to three budget cycles; where enforcement is weak, landfill economics still dominate.

By Waste Type

Sub-SegmentKey Trend
Non-HazardousVolume grows with industrial output but competes on price
HazardousReclassification events shift large volumes into higher-value handling


Hazardous handling carries the margin, the licensing burden, and the liability. Reclassification decisions by regulators remain the single largest source of demand discontinuity in this dimension.

By Industry

Sub-SegmentKey Trend
Chemicals & PetrochemicalsLong-term site contracts with integrated on-site services
Oil & GasDrilling residue and tank cleaning tied to activity cycles
ManufacturingMetalworking fluid recovery and process scrap valorisation
Construction & DemolitionInert material recovery targets drive on-site processing
Food & BeverageOrganic diversion and anaerobic digestion offtake
Mining & MetallurgyTailings governance after successive dam failure reviews
Other IndustriesPharmaceutical and electronics residues need specialist destruction


Industry mix explains contract duration more than contract value. Continuous-process sectors sign multi-year embedded service agreements, while project-driven sectors such as construction and oilfield services buy episodically and price aggressively.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.