Industrial Vehicles Market (2026 - 2035)

Industrial Vehicles Market Research Report By Vehicle Type (Forklifts, Tow Tractors, Aisle Trucks, Container Handlers, Others), By Propulsion Type (Internal Combustion Engine (ICE), Electric, Hybrid & Fuel Cell), By Application (Manufacturing, Warehousing, Freight & Logistics, Mining, Construction, Others), By Weight Category (Light Duty, Medium Duty, Heavy Duty), By Level of Autonomy (Non-Autonomous, Semi-Autonomous, Fully Autonomous) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/AT/1660-HCR 111 Pages Shubham Munde, Sejal Akre Last Updated: September 15, 2026
Industrial Vehicles Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.18%
2025 Market SizeUSD 42.77 Billion
2035 Market SizeUSD 70.86 Billion
Key Players
Toyota Industries Corporation
KION Group AG
Jungheinrich AG
Mitsubishi Logisnext
Crown Equipment Corporation
Hyster-Yale Inc.
Opportunities
  • Fleet-as-a-Service Contracts
  • Emerging-Market Localisation
  • Telematics Data Monetisation

Industrial Vehicles Market Summary

The global Industrial Vehicles Market closed 2025 at USD 42.77 billion and begins the forecast window at USD 44.98 billion in 2026, climbing to USD 70.86 billion by 2035 at a 5.18% CAGR. Two catalysts anchor that trajectory. The first is warehouse capital spending tied to e-commerce fulfilment, which pushed global material handling equipment orders past pre-pandemic peaks [1]. The second is regulatory: the EU Machinery Regulation 2023/1230, applicable from January 2027, forces a functional-safety redesign of powered industrial trucks sold across the bloc [4].

Electrification is the structural story inside the Industrial Vehicles Market. Lead-acid Class IV and V internal-combustion trucks are giving way to lithium-ion Class I and Class II platforms with opportunity charging, and diesel yard tractors are being displaced by battery-electric equivalents. California's Zero-Emission Forklift Regulation alone covers an estimated fleet of 90,000 units and mandates phase-out schedules beginning in 2026 [7]. Toyota Industries and KION together committed over USD 1.1 billion to electrification and automation R&D across 2023–2025 [11][12].

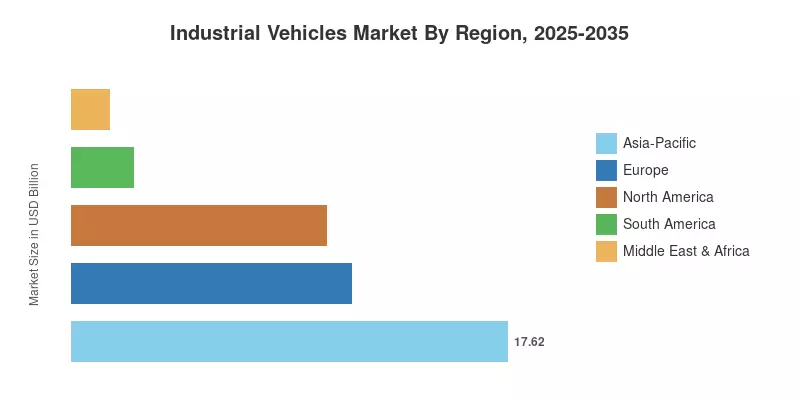
Regionally, Asia-Pacific dominates with 41.2% of 2025 revenue and also grows fastest at a 6.1% CAGR, powered by Chinese domestic manufacturers and India's production-linked incentive rollout. Europe holds 26.5%, defended by a dense installed base and strict emissions zoning. North America follows at 24.1%, where warehouse automation retrofits rather than greenfield builds now drive replacement demand. The next decade rewards vendors who sell uptime, not iron.


Key Report Takeaways

• By Technology

  • Electric propulsion accounted for 54.8% of the Industrial Vehicles Market in 2025, the single largest technology block
  • Hybrid and hydrogen fuel-cell platforms are expanding at an 11.4% CAGR through 2035
  • Fully autonomous units, still a small base, post a 17.8% CAGR as fleet operators pilot mixed manned/unmanned aisles

• By Sector

  • Manufacturing contributed USD 14.37 billion in 2025, the largest application pool
  • Warehousing expands at a 6.4% CAGR, outpacing the overall Industrial Vehicles Market
  • Mining and heavy-duty yard operations represent 8.9% of demand

• By Region

  • Asia-Pacific holds 41.2% revenue share and leads in growth
  • Europe generated USD 11.33 billion in 2025
  • South America grows at a 5.9% CAGR from a small base


Market Size and Forecast (2021–2035)

Historical values are triangulated from unit-shipment data published by national industrial truck associations, customs trade flows, and audited segment revenue disclosed by the ten largest OEMs. Forecast values apply a bottom-up unit-times-ASP build, adjusted for the mix shift toward higher-priced lithium-ion and automation-equipped platforms.
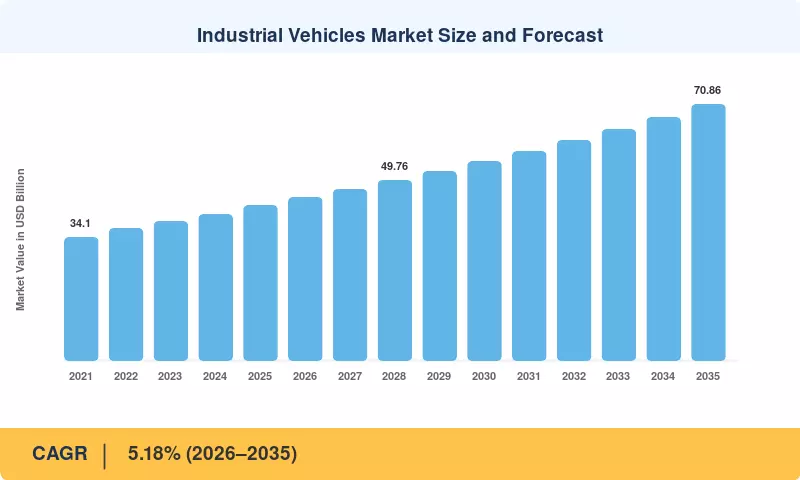
Industrial Vehicles Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
E-commerce warehouse buildout 1.35 Global Medium-term (2–4 yr)
Emissions regulation on ICE trucks 1.10 EU, US (CA) Long-term (≥4 yr)
Lithium-ion cost decline 0.85 Global Medium-term (2–4 yr)
Warehouse labour scarcity 0.75 NA, EU, Japan Short-term (≤2 yr)
Manufacturing reshoring incentives 0.60 NA, EU, India Long-term (≥4 yr)
Fleet telematics and uptime contracts 0.45 Global Short-term (≤2 yr)
Cold-chain and pharma logistics growth 0.30 APAC, EU Medium-term (2–4 yr)


Warehouse Capacity Expansion

The equipment market CAGR is expected to rise by approximately 1.35% due to the rapid expansion of e-commerce warehouse buildout, which is speeding material handling automation. As logistics companies quickly expand indoor fulfillment facilities designed for zero-emission electric vehicles, this structural growth is concentrated across medium-term (2–4 year) deployment cycles.


Emissions Rules Reshaping Propulsion Mix

Adopted in 2024, California's Zero-Emission Forklift Regulation prohibits new Class IV and V spark-ignition trucks weighing less than 12,000 pounds starting in 2026 and phases out older models on a fleet-size schedule through 2038 [7]. Although CARB modeling predicts lifetime operational savings of roughly 24%, compliance expenses range from USD 12,000 to USD 20,000 per unit beyond ICE equivalents [7]. A similar result is pushed by Europe's Stage V non-road emission limitations [4].


Labour Economics

Warehouse operator turnover in the United States exceeded 45% annually across 2023–2024, and mean hourly wages rose 18% over the same span [16]. Automation payback windows shortened accordingly — semi-autonomous tuggers now clear a 26-month payback in three-shift operations, down from 41 months in 2021 [15].

Battery Cost Curve

Lithium-iron-phosphate pack prices fell to roughly USD 92 per kWh in 2025 from USD 148 in 2021 [19]. Because batteries represent 30–38% of an electric truck's bill of materials, that decline compresses the price premium versus internal combustion to under 15% on Class III platforms [11].


Restraints Impact Analysis

Restraint weightings are directional drag estimates, not subtractive inputs to the headline CAGR of the Industrial Vehicles Market.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High upfront capital cost of electrification -0.70 Global Short-term (≤2 yr)
Charging infrastructure gaps in older facilities -0.55 EU, NA Medium-term (2–4 yr)
Interest-rate sensitivity of leased fleets -0.45 Global Short-term (≤2 yr)
Shortage of certified service technicians -0.35 NA, EU Long-term (≥4 yr)
Component and semiconductor supply volatility -0.25 Global Medium-term (2–4 yr)


Capital Intensity of Fleet Conversion

Converting a 120-truck mixed fleet to lithium-ion typically requires USD 2.4 to USD 3.1 million in equipment plus USD 400,000 to USD 650,000 in electrical infrastructure [11][12]. Mid-market operators frequently lack that balance-sheet headroom, and utility interconnection queues in several US states now exceed 14 months [8].

Service Capacity Constraints

Certified technician vacancies across North American dealer networks stood near 11,000 positions in 2024, roughly 17% of required headcount [16]. High-voltage battery servicing demands additional certification, and dealers report training pipelines running two years behind fleet electrification schedules [13].

Financing Sensitivity

Roughly 62% of powered truck acquisitions in mature markets are financed or leased [18]. Every 100-basis-point move in benchmark rates shifts monthly lease payments by 4–6%, which measurably delays replacement decisions in freight-exposed verticals.


Industrial Vehicles Market Opportunities

Fleet-as-a-Service Contracts

Bundling equipment, energy, telematics, and guaranteed uptime into a single per-hour rate converts capital expenditure into operating expenditure and removes the largest adoption barrier identified. Early programmes from KION and Jungheinrich show 8–12 percentage points of margin uplift over transactional sales, and lock in multi-year service annuities across the Industrial Vehicles Market [12][13].

Emerging-Market Localisation

Electric industrial trucks are among the eligible categories that received around USD 3.5 billion from India's production-linked incentive program for cars and parts [10]. Local assembly reduces delivery time to less than 12 weeks and eliminates a 15–18% import duty. Vietnam, Brazil, and Indonesia all have similar structural disparities.


Telematics Data Monetisation

A connected fleet generates 400 to 900 megabytes of operational telemetry per truck-month. Vendors selling impact analytics, operator scorecards, and predictive component alerts are realising USD 240 to USD 480 in annual recurring revenue per connected unit — margin that survives the equipment price war [15].

Hydrogen in High-Throughput Cold Chains

Fuel-cell trucks refuel in under three minutes and hold voltage in sub-zero environments where lithium chemistry derates. The US DOE has funded multiple material-handling hydrogen deployments, and cold-storage operators running three shifts represent the clearest commercial beachhead [8][20].

Retrofit and Second-Life Programmes

More than 40% of the installed base is over nine years old [2]. Lithium retrofit kits priced at USD 9,000 to USD 14,000 extend chassis life by five to seven years and open a service revenue channel that competes directly with new-unit sales.


Industrial Vehicles Market Future Outlook

Autonomy Moves From Pilot to Payroll

Mixed-fleet autonomy — where an autonomous guided vehicle shares aisles with manned trucks — is the decisive capability. Sensor bill-of-materials for a navigation stack fell roughly 55% between 2020 and 2025, and the Industrial Vehicles Market should see autonomous-capable units exceed 12% of new shipments by 2033 [15].

Energy Systems Become the Product

Charging orchestration, peak-shaving, and second-life battery arrays turn a fleet into a distributed energy asset. The IEA projects industrial electricity demand growth of about 2.1% annually through 2035, making load management a procurement criterion rather than a facilities afterthought [3].

Aftermarket Overtakes Iron on Margin

Parts, service, and rental already deliver a disproportionate share of OEM operating profit — Hyster-Yale and Jungheinrich both disclose aftermarket margins materially above new-equipment margins [13][14]. Expect the ten-year contract, not the purchase order, to become the standard commercial unit.

Scope 3 Reporting Pulls Fleets Into Disclosure

Diesel yard fleets fall directly between Scope 1 and 3 borders under CSRD, which requires big EU filers to disclose upstream and downstream emissions starting in 2025 [4]. Vendors with auditable telemetry will benefit from customers' growing need for emissions certificates per equipment hour.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 41.2% share Domestic OEM scale-up, export competitiveness
Europe USD 11.33 B Emissions compliance, automation retrofit
North America 24.1% share Warehouse density, zero-emission mandates
South America 5.9% CAGR Agribusiness logistics, port modernisation
Middle East & Africa USD 1.54 B Free-zone logistics hubs, mining
Total USD 42.77 B —

Regional performance in the Industrial Vehicles Market diverges sharply on propulsion mix rather than volume growth alone.


North America

Country Share of Region Key Driver
US 76.5% Fulfilment centre density; CARB mandates
Canada 13.8% Forestry and port handling
Mexico 9.7% Nearshoring manufacturing corridors


Nearshoring reshaped Mexican demand faster than any policy instrument. Manufacturing FDI into Mexico exceeded USD 36 billion in 2024, concentrated in Nuevo León and Bajío industrial parks that specify electric fleets from day one [14]. In the United States, the Inflation Reduction Act's Section 48C allocations extended to qualifying material-handling electrification projects [8].

Europe

Country Metric Key Driver
Germany 27.4% of region Automotive and machinery plants
UK USD 1.60 B Grocery and 3PL warehousing
France 4.0% CAGR Logistics corridor investment
Italy 11.9% of region Manufacturing SME base
Spain USD 0.93 B Port and agri-logistics
Nordic Countries 4.8% CAGR Early electrification adoption
Russia 6.5% of region Domestic substitution sourcing
Rest of Europe USD 1.30 B CEE contract manufacturing


Germany's dense Mittelstand base makes it the continent's replacement-cycle bellwether. The German machinery association reported a 6% decline in domestic truck orders in 2024 followed by stabilisation in 2025 as Machinery Regulation deadlines approached [5]. Nordic operators, backed by low-carbon electricity, already run electric shares above 70%.

Asia-Pacific

Country Metric Key Driver
China 44.6% of region Domestic OEM scale; export volume
India 8.9% CAGR PLI incentives; warehousing boom
Japan USD 2.78 B Automation-first factory logistics
South Korea 8.4% of region Semiconductor fab logistics
ASEAN USD 1.99 B Electronics assembly relocation
Rest of Asia-Pacific 5.7% CAGR Port and mining handling


China anchors the Asia-Pacific Industrial Vehicles Market on both consumption and supply. Anhui Heli and Hangcha together shipped well over a million units cumulatively across recent years and have converted domestic scale into aggressive export pricing across Southeast Asia and Latin America [9]. India's story is different — warehousing stock in the top eight cities passed 400 million square feet in 2025, and Grade-A facilities specify electric fleets almost exclusively [10].

South America

Country Metric Key Driver
Brazil 58.3% of region Agribusiness and port throughput
Argentina USD 0.35 B Food processing logistics
Rest of South America 24.1% of region Mining and beverage distribution


Brazilian port modernisation concessions awarded through 2024 committed billions to terminal upgrades, and container handlers plus heavy-duty yard tractors form the bulk of associated equipment spend [17]. Currency volatility, however, keeps used-equipment imports competitive against new units.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 29.7% of region Vision 2030 industrial cities
UAE USD 0.35 B Free-zone re-export logistics
South Africa 21.8% of region Mining and automotive assembly
Egypt 6.2% CAGR Suez Canal Economic Zone
Rest of MEA 14.9% of region Oil and gas support logistics


Saudi Arabia's National Industrial Development programme targets a manufacturing GDP contribution of roughly USD 320 billion by 2035, and every new industrial city carries embedded material-handling demand [20]. Dubai's free zones, meanwhile, function as the regional distribution point for Asian OEM inventory.


Industrial Vehicles Market By Region, 2025-2035

Industrial Vehicles Market Segmentation

Segment behaviour within the Industrial Vehicles Market splits along propulsion economics and duty cycle intensity.

By Vehicle Type

Segment Metric (2025) Primary Demand Driver
Forklifts 58.4% share Universal plant and warehouse handling
Tow Tractors USD 6.07 B Line-side delivery, airport ground handling
Aisle Trucks 6.9% CAGR High-bay narrow-aisle storage density
Container Handlers USD 3.89 B Port and intermodal throughput
Others 4.1% CAGR Specialised heavy handling


Forklifts remain the volume backbone of the Industrial Vehicles Market, but growth concentrates in narrow-aisle platforms as land costs push storage vertical. Aisle trucks command a 30–45% price premium and carry richer software attach rates. Tow tractors benefit from a separate dynamic — assembly plants moving to milk-run replenishment retire individual forklift trips in favour of trained tugger routes.

By Propulsion Type

Segment Metric (2025) Primary Demand Driver
Electric 54.8% share Emissions rules; lower TCO
Internal Combustion Engine (ICE) USD 17.75 B Outdoor, rough-terrain, heavy loads
Hybrid & Fuel Cell 11.4% CAGR Multi-shift cold chain; fast refuelling


Electric crossed the majority threshold in the Industrial Vehicles Market during 2024 and does not look back. Lithium-ion specifically displaces lead-acid rather than diesel in the first wave, eliminating battery-room floor space and watering labour. ICE persists where duty cycles involve outdoor yards, timber, and loads above eight tonnes.

By Application

Segment Metric (2025) Primary Demand Driver
Manufacturing USD 14.37 B Line-side logistics; reshoring
Warehousing 6.4% CAGR E-commerce fulfilment density
Freight & Logistics 16.8% share 3PL fleet expansion
Mining USD 3.81 B Heavy-duty underground and surface handling
Construction 5.5% CAGR Infrastructure programmes
Others 4.0% share Agriculture, aviation, retail


Manufacturing holds the largest absolute pool, yet warehousing sets the pace. Third-party logistics providers now specify standardised fleets across multiple client sites, which favours OEMs with global service coverage over regional specialists.

By Weight Category

Segment Metric (2025) Primary Demand Driver
Light Duty 46.2% share Indoor palletised goods
Medium Duty USD 14.76 B General industrial handling
Heavy Duty 4.6% CAGR Ports, steel, mining


Light-duty equipment commands the volume with a dominant 46.2% market share fueled by indoor palletised goods, yet medium-duty units form the core revenue engine at USD 14.76 billion for general industrial handling. Meanwhile, heavy-duty applications dictate the long-term growth trajectory at a steady 4.6% CAGR, anchored firmly in punishing industrial environments like ports, steel, and mining.

By Level of Autonomy

Segment Metric (2025) Primary Demand Driver
Non-Autonomous 78.6% share Installed base inertia; low capex
Semi-Autonomous USD 7.23 B Operator assistance, safety systems
Fully Autonomous 17.8% CAGR Labour scarcity; repetitive routes


Non-autonomous equipment anchors the market with a dominant 78.6% share driven by installed base inertia and low capital expenditure, yet semi-autonomous solutions establish a robust USD 7.23 billion foundation geared toward operator assistance and advanced safety systems. Meanwhile, fully autonomous systems dictate the future growth trajectory with a rapid 17.8% CAGR, propelled urgently by severe labour scarcity and predictable, repetitive material-handling routes.


Competitive Benchmarking

Concentration sits in moderate territory. Our HHI estimate falls between 950 and 1,150, with the top five vendors controlling roughly 52–58% of global revenue. That leaves a long tail of regional specialists — particularly in China and India — competing aggressively on price in light-duty categories while global majors defend share through service networks and financing arms.

Company Est. Revenue Share Range Key Offerings for Industrial Vehicles Market Strategic Positioning
Toyota Industries Corporation ~19–23% Full Class I–V range, automated platforms, logistics software Scale leader; deepest service network
KION Group AG ~13–16% Linde, STILL, Baoli brands; warehouse automation Automation-integrated portfolio
Jungheinrich AG ~7–9% Warehouse trucks, lithium systems, rental fleet Energy-systems specialist
Mitsubishi Logisnext ~6–8% Counterbalance, reach, and container handlers Strong Japanese and US OEM channels
Crown Equipment Corporation ~5–7% Electric lift trucks, InfoLink telematics Vertically integrated manufacturing
Hyster-Yale Inc. ~5–7% Heavy-duty and port equipment, Nuvera fuel cells Big-truck and hydrogen focus
Anhui Heli Co. ~4–6% Full-line electric and ICE trucks Domestic scale; export pricing
Hangcha Group ~4–6% Lithium-ion light and medium trucks Cost leadership in emerging markets
Hyundai Material Handling ~2–4% Diesel and electric counterbalance Construction-adjacent distribution
Komatsu Ltd. ~2–3% Heavy forklifts, mining support vehicles Heavy-duty engineering pedigree
Clark Material Handling ~1–2% Entry and mid-tier lift trucks Dealer-led value positioning
Godrej & Boyce ~1–2% India-manufactured lift trucks Localisation and service depth


Recent News & Developments

  • Toyota Industries (March 2024): Announced expanded lithium-ion assembly capacity in Indiana to serve North American demand, cutting delivery lead times materially [11]
  • KION Group (September 2024): Launched an integrated warehouse orchestration platform linking trucks, racking, and robotics under one control layer [12]
  • California Air Resources Board (June 2024): Adopted the Zero-Emission Forklift Regulation, setting the first binding phase-out schedule for spark-ignition trucks in the US [7]
  • Jungheinrich (February 2025): Completed acquisition of an automation software firm to strengthen its intralogistics stack [13]
  • Hyster-Yale (November 2024): Expanded Nuvera fuel-cell deployment with a major cold-storage operator across multiple US sites [14]
  • European Commission (January 2025): Published harmonised standards guidance supporting Machinery Regulation 2023/1230 implementation ahead of the 2027 application date [4]
  • Hangcha Group (August 2025): Opened a Southeast Asian assembly facility to serve ASEAN demand under regional trade preferences [9]
  • Crown Equipment (April 2025): Released an operator-assist package with automated speed and load-height interlocks for mixed-traffic environments [15]


Industrial Vehicles Market Report Scope

Attribute Detail
Market Scope Global Industrial Vehicles Market by vehicle type, propulsion, application, weight category, autonomy level, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.18% (2026–2035)
Market Size Checkpoints USD 42.77 B (2025); USD 44.98 B (2026); USD 70.86 B (2035)
Fastest Growing Segments Fully Autonomous; Hybrid & Fuel Cell; Aisle Trucks
Companies Profiled 12 leading global and regional manufacturers
Valuation Currency USD (constant 2025 exchange rates)

FAQs

How should buyers structure a total cost of ownership comparison in the Industrial Vehicles Market?
Model energy, maintenance, battery replacement, and residual value across a seven-year horizon rather than comparing sticker prices. Electric platforms typically win on TCO after year three despite a higher purchase price [11].
What certification requirements apply to operators of powered industrial trucks?
US employers must provide formal instruction, practical training, and evaluation every three years under OSHA 29 CFR 1910.178 [21]. Equivalent competence requirements apply across EU member states, with refresher intervals set nationally.
How does an AGV differ from an AMR in the Industrial Vehicles Market?
AGVs follow fixed guidance infrastructure such as magnetic tape or wire, making them cheap but inflexible. AMRs navigate dynamically using onboard mapping, costing more upfront but adapting to layout changes without re-engineering [15].
Is renting more sensible than purchasing for seasonal operations?
Short-term rental usually wins when annual utilisation falls below roughly 900 hours or peaks last under four months. Above that threshold, lease-to-own or purchase delivers better economics [18].
What integration challenges arise when adding automation to legacy Industrial Vehicles Market fleets?
Warehouse management system compatibility is the primary obstacle, followed by inconsistent floor conditions and inadequate Wi-Fi coverage. Budget 15–20% of project cost for facility readiness rather than equipment alone [15].
How do tariffs affect sourcing decisions for industrial trucks?
Import duties on Asian-manufactured units range widely by jurisdiction, and several markets apply additional anti-dumping measures. Local assembly or regional trade-agreement sourcing frequently offsets a 12–18% landed cost differential [10].
What resale values should fleet managers expect?
Well-maintained electric trucks retain roughly 30–38% of original value at seven years, ahead of comparable internal combustion units. Battery health documentation is now the decisive variable in secondary-market pricing [2].    
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory frameworks, industry technical standards, trade databases, and authoritative logistics and construction publications. Key sources included the US Occupational Safety and Health Administration (OSHA), US Environmental Protection Agency (EPA), European Commission Machinery Directive (2006/42/EC), International Organization for Standardization (ISO 3691 series for industrial trucks), American National Standards Institute (ANSI B56.1), Industrial Truck Association (ITA), World Industrial Truck Statistics (WITS), Material Handling Equipment Distributors Association (MHEDA), Association of Equipment Manufacturers (AEM), European Material Handling Federation (FEM), Japan Industrial Vehicles Association (JIVA), China Construction Machinery Association (CCMA), Bureau of Transportation Statistics, US Census Bureau Annual Survey of Manufactures, Eurostat Machinery and Equipment Statistics, OECD Glossary of Industrial Organisation, International Labour Organization (ILO) safety databases, and national ministry of industry reports from key manufacturing hubs.

Shipment data, safety certification criteria, fleet age demographics, regulatory compliance information, and market landscape analysis for internal combustion engine, electric, hybrid, compressed natural gas, and liquid propane gas vehicle technologies were gathered from these sources.


Primary Research

In the primary research process, supply-side and demand-side stakeholders were interviewed to obtain qualitative and quantitative insights. Supply-side sources included CEOs, VPs of Product Development, heads of engineering, and commercial directors from industrial vehicle OEMs, powertrain technology providers, and material handling equipment manufacturers. Demand-side sources comprised fleet procurement managers, director of logistics operations, warehouse facility managers, supply chain directors from third-party logistics (3PL) providers, and construction project managers from infrastructure development firms. Primary research validated market segmentation across weight categories (light duty, medium duty, heavy duty, ultra heavy duty), confirmed electrification product pipeline timelines, and gathered insights on fleet replacement cycles, total cost of ownership (TCO) analysis, and automation integration patterns.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

• By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Unit volume analysis and revenue mapping were used to get the global market valuation. The following were part of the methodology:

• Over fifty major manufacturers from North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa were identified.

• Product mapping between the categories of electric vehicles, tow tractors, container handling trucks, industrial tractors, and forklifts

• Examination of modeled and reported yearly revenues for the portfolios of material handling equipment and industrial vehicles

• Manufacturers that will account for 70–75% of the worldwide market in 2024

• Extrapolation to determine segment-specific valuations by fuel type, end-use industry, and weight categorization utilizing top-down (manufacturer revenue validation) and bottom-up (unit shipment volume × average selling price by country/region) approaches

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















