Ginger Oil Market (2026 - 2035)

Ginger Oil Market Size, Share, Industry Trend & Analysis Research Report By Product Type (Conventional Ginger Oil, Organic Ginger Oil), By Application (Food & Beverages, Pharmaceuticals & Nutraceuticals, Personal Care & Cosmetics, Aromatherapy & Wellness, Fragrance & Perfumery, Others), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/FnB/28785-HCR 128 Pages Varsha More Last Updated: September 17, 2026
Ginger Oil Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.65%
2025 Market SizeUSD 214.50 Million
2035 Market SizeUSD 371.60 Million
Key Players
Kancor Ingredients Ltd.
Synthite Industries Ltd.
doTERRA International
Young Living Essential Oils
Robertet Group
Givaudan SA
Opportunities
  • African Smallholder Integration
  • Functional Beverage Innovation
  • Data-Driven Quality Grading
 

Ginger Oil Market Summary

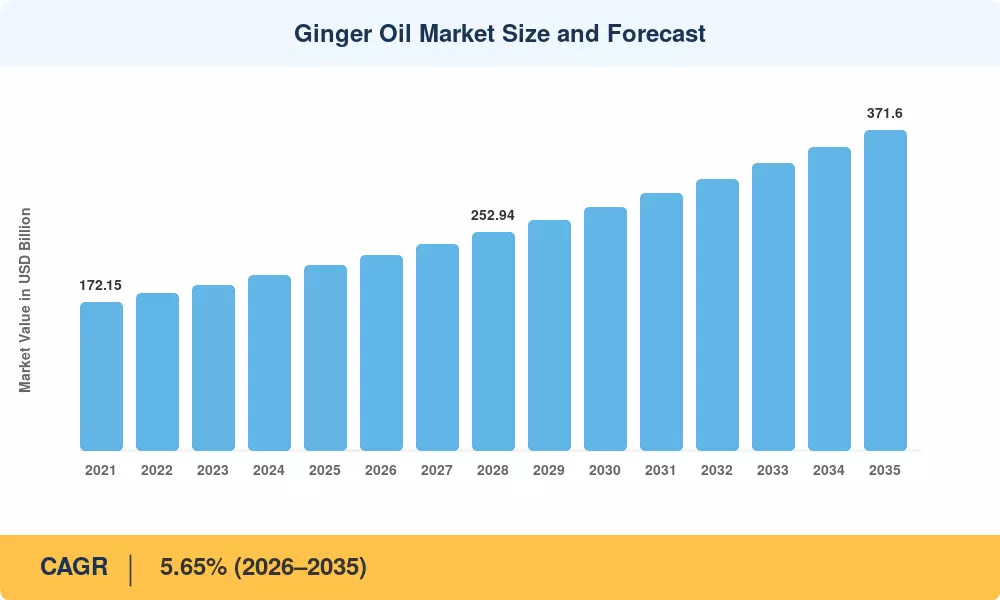
The ginger oil market reached an estimated USD 214.50 Million in 2025 and is projected to expand from USD 226.62 Million in 2026 to USD 371.60 Million by 2035, registering a CAGR of 5.65% over the forecast window. This steady trajectory reflects rising consumer appetite for steam distilled ginger essential oil across food, wellness, and personal-care verticals — reinforced by tightening regulatory mandates in the EU and North America that favor botanical ingredients over synthetic alternatives. India's Spices Board allocated INR 220 crore in FY 2024-25 to modernize post-harvest processing, directly boosting the supply quality of ginger oleoresin and extract destined for international buyers [2].

A significant transformation is reshaping extraction technology. Legacy solvent-based methods are giving way to supercritical CO₂ and cold-press techniques that preserve bioactive compounds like gingerols and shogaols — compounds central to ginger oil's anti-inflammatory use in pharmaceutical formulations. Global investment in clean-label extraction infrastructure exceeded USD 1.2 billion in 2024, with Kancor and Synthite each commissioning new distillation lines in Kerala [3].

Asia-Pacific commands roughly 42.45% of the ginger oil market, anchored by India's and China's dominance in raw-material cultivation The Middle East & Africa region is the fastest-growing territory at an 8.40% CAGR, driven by expanding aromatherapy and massage ginger oil adoption in GCC wellness tourism. Europe holds the second-largest share at approximately 23.80%, propelled by clean-label demand and culinary ginger flavoring oil integration in premium food manufacturing [4]. The decade ahead will reward suppliers who can bridge the gap between commodity-grade roots and traceable, certified-organic oil.

Key Report Takeaways

• By Product Type

  • Conventional ginger oil accounted for 68.10% of total ginger oil market revenue in 2025, supported by cost-competitive sourcing from Chinese exporters
  • Organic ginger oil is the fastest-growing segment at a 7.10% CAGR through 2035, reflecting retailer mandates for certified supply chains

• By Application

  • Food & beverages generated a 63.00% value share in the ginger oil market during 2025, with culinary ginger flavoring oil demand expanding across craft beverages and confectionery
  • Aromatherapy & wellness is projected to grow at a 7.78% CAGR, the highest among all application segments

• By Region

  • Asia-Pacific held 42.45% of the global ginger oil market in 2025
  • The Middle East & Africa is forecast to register an 8.40% CAGR through 2035
  • North America contributed USD 40.76 Million in 2025 value

Market Size and Forecast (2021–2035)

MRFR's market sizing integrates bottom-up revenue modeling across 45+ countries, validated against customs trade data, company financials, and primary interviews with processors and distributors. Historical figures draw on audited import-export databases, while forecast projections apply segment-level growth curves calibrated to macroeconomic indicators and regulatory timelines.
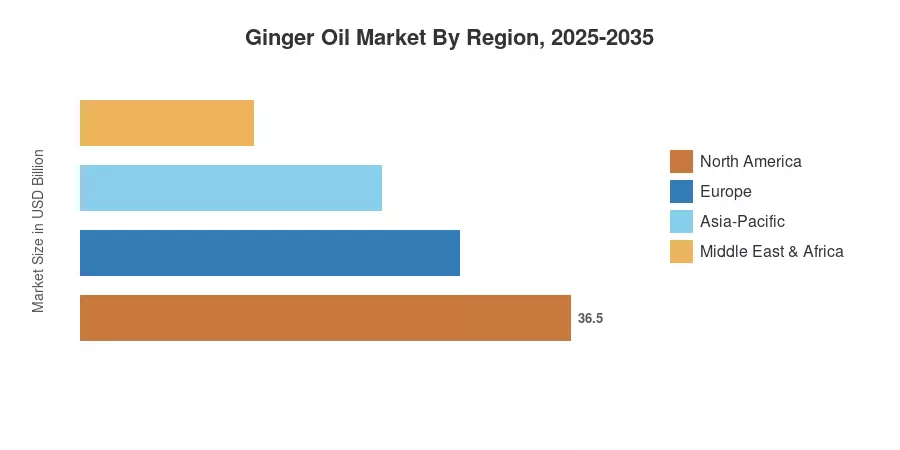
Ginger Oil Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising demand for natural food flavoring agents ~22% Global Short-term (≤2 yr)
Aromatherapy and wellness mainstreaming ~18% North America, Europe Medium-term (2–4 yr)
Clean-label & botanical regulatory mandates ~16% EU, North America Medium-term (2–4 yr)
Pharmaceutical bioactive ingredient sourcing ~14% Asia-Pacific, Europe Long-term (≥4 yr)
Organic & traceable supply chain premiums ~12% Global Long-term (≥4 yr)
GCC wellness tourism infrastructure investment ~10% Middle East & Africa Medium-term (2–4 yr)
E-commerce DTC channel expansion ~8% North America, Asia-Pacific Short-term (≤2 yr)


Natural Food Flavoring Demand

Consumers are actively replacing synthetic flavor compounds with plant-derived alternatives. The EU's revised Flavouring Regulation (EC 1334/2008) now requires disclosure of synthetic flavoring agents, giving culinary ginger flavoring oil a competitive edge in bakery, confectionery, and craft-beverage formulations. Nestlé and PepsiCo both expanded ginger-based product lines in 2024

Aromatherapy Mainstreaming

The global wellness economy surpassed USD 5.6 trillion in 2024, according to the Global Wellness Institute, with aromatherapy and massage ginger oil emerging as a top-five essential oil by retail volume in spa and home-use channels. Ginger oil anti-inflammatory use resonates with consumers managing chronic pain and stress, driving repeat purchases across subscription-based wellness platforms in the US and Germany [6].

Botanical Regulatory Mandates

Health Canada's updated Natural Health Products Regulations and the US FDA's draft guidance on botanical drug applications both expanded allowable therapeutic claims for steam-distilled ginger essential oil. These frameworks lower the regulatory barrier for nutraceutical and OTC formulations, creating a pull effect for pharmaceutical-grade ginger oleoresin and extract [7][11].

Organic Supply Chain Premiums

USDA-certified organic ginger oil commands a 35–50% price premium over conventional grades. As retailers like Whole Foods and Sephora mandate certified-organic ingredient sourcing across private-label lines, processors are investing in traceable farm-to-bottle supply chains — particularly in Uganda, Peru, and Northeast India [5].


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Raw-material price volatility & crop yield fluctuation ~–25% India, Nigeria Short-term (≤2 yr)
Adulteration & quality inconsistency ~–20% Asia-Pacific, Africa Medium-term (2–4 yr)
Competition from synthetic ginger flavor isolates ~–18% North America, Europe Long-term (≥4 yr)
High organic certification costs for smallholders ~–15% South America, Africa Medium-term (2–4 yr)
Limited cold-chain logistics in emerging origins ~–12% Southeast Asia, Africa Long-term (≥4 yr)


Raw-Material Price Volatility

India's 12% ginger production decline in 2025 — driven by erratic monsoon patterns in Meghalaya and Mizoram — pushed farm-gate prices up 28% year-on-year. This volatility compresses processor margins and forces quarterly price renegotiations that disrupt long-term supply contracts within the ginger oil market [4].

Adulteration Risks

Industry testing by SGS and Eurofins in 2024 flagged adulteration in roughly 15% of commercial ginger oleoresin and extract shipments originating from unregulated processing hubs. Dilution with cheaper citral-rich oils undermines buyer confidence and increases compliance costs for importers in the EU and Japan [13].

Synthetic Substitution Pressure

Advances in biotechnology-derived gingerol isolates allow flavor houses to replicate ginger profiles at 40–60% lower cost. While these synthetics lack the full terpene complexity prized in aromatherapy and massage ginger oil applications, they pose a credible threat in cost-sensitive industrial flavoring [14].


Ginger Oil Market Opportunities

African Smallholder Integration

Nigeria and Ethiopia produce approximately 650,000 tonnes of fresh ginger per year, but less than 8% is processed into essential oil locally. GIZ and USAID development initiatives are targeting the installation of 25 community-scale steam distillation facilities by 2027, creating a USD 30+ million export opportunity for steam distilled ginger essential oil [9].


Functional Beverage Innovation

The worldwide functional beverage category is increasing at a CAGR of 8.5%, with ginger-infused drinks, from kombucha to immunity shots, being some of the fastest-moving SKUs. Brands that blend culinary ginger flavored oil with turmeric and adaptogens are winning premium shelf space at Whole Foods, Boots and Amazon Fresh.


Data-Driven Quality Grading

AI-powered spectroscopic grading systems can now grade batches of ginger oleoresin and extracts by gingerol content in under 90 seconds. Companies employing these systems can attract price premiums of 15–20% by delivering batch-to-batch consistency — a valuable proposition for pharmaceutical and personal-care buyers [8].


Pharmaceutical Anti-Inflammatory Pipeline

Between 2022 and 2024, the number of registered ginger-based anti-inflammatory therapies with ClinicalTrials.gov increased by 34%. Positive Phase-II findings for the anti-inflammatory use of ginger oil in osteoarthritis topical formulations could unlock a USD 50+ million potential niche within the ginger oil industry by 2030 [11].


Subscription Wellness & DTC Channels

Direct-to-consumer essential oil subscriptions grew 22% in 2024 in the US alone. Brands like Vitruvi and Plant Therapy are expanding aromatherapy and massage ginger oil kits, creating recurring revenue streams that reduce channel dependency on wholesale distributors.


Ginger Oil Market Future Outlook

AI-Powered Quality Assurance and Traceability

Blockchain-integrated traceability platforms and AI-driven spectral analysis will become table stakes for premium ginger oil market participants by 2028. Near-infrared (NIR) grading can verify gingerol concentrations within seconds, enabling real-time batch certification that pharmaceutical and cosmetics buyers increasingly demand for ginger oleoresin and extract procurement [8].

Sustainable Sourcing and ESG Reporting

ESG disclosure mandates — including the EU's Corporate Sustainability Reporting Directive (CSRD) — will push ginger oil buyers to document origin traceability and fair-trade compliance across supply chains. Producers investing in Rainforest Alliance or Fair for Life certification will capture preferential sourcing contracts worth an estimated 20–30% margin premium [5].

Convergence of Wellness and Pharmaceuticals

The boundary between aromatherapy and massage, ginger oil and regulated pharmaceutical actives is blurring. As clinical evidence for ginger oil anti-inflammatory use accumulates, regulators in the US, EU, and Japan are expected to expand monograph coverage, creating a hybrid wellness-pharma category worth an incremental USD 25–40 million by 2032 [11].

Climate Adaptation in Cultivation Regions

Shifting rainfall patterns threaten traditional cultivation zones in India and Nigeria. Climate-resilient ginger cultivars developed by ICAR and CIAT are expected to enter commercial deployment by 2029, stabilizing yields of steam distilled ginger essential oil feedstock and reducing the raw-material volatility that has historically constrained ginger oil market growth [4][9].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific 42.45% share (2025) Cultivation modernization; export processing scale-up
Europe 23.80% share (2025) Clean-label food regulation; premium personal care
North America USD 40.76 Million (2025) Functional beverages; aromatherapy retail
South America 5.05% CAGR (2026–2035) Organic farming expansion; nutraceutical exports
Middle East & Africa 8.40% CAGR (2026–2035) Wellness tourism; smallholder oil programs
Total USD 214.50 Million (2025) —

The ginger oil market exhibits distinct regional dynamics shaped by cultivation footprints, regulatory environments, and end-use consumption patterns.


North America

Country Key Metric Key Driver
US 78.50% of regional share Functional beverage and DTC wellness retail
Canada 5.95% CAGR Health Canada botanical product approvals
Mexico USD 2.18 Million Traditional medicine and artisanal food production


The US drives the North American ginger oil market demand through a thriving functional-beverage sector and growing adoption of steam distilled ginger essential oil in boutique aromatherapy chains. Canada's updated NHP regulations have lowered barriers for ginger oil anti-inflammatory use in OTC topical products, attracting new brand entrants since 2023 [7].

Europe

Country Key Metric Key Driver
Germany 26.30% of regional share Pharmaceutical and nutraceutical formulation hub
UK 6.15% CAGR Premium clean-label food and wellness retail
France USD 5.42 Million Fragrance and perfumery demand
Italy 4.85% CAGR Culinary export sector integration
Spain USD 2.95 Million Emerging aromatherapy tourism
Nordic Countries 5.40% CAGR Organic personal care adoption
Russia USD 2.10 Million Traditional herbal medicine channels
Rest of Europe 12.60% of regional share Diversified cosmetic ingredient sourcing


Europe's ginger oil market benefits from the EU's stringent clean-label regulations, which position natural ginger oleoresin and extract as preferred alternatives to synthetic flavoring in processed food. Germany anchors pharmaceutical demand, while France's fragrance houses in Grasse remain significant buyers of high-grade culinary ginger flavoring oil and aromatic distillates [3][14].

Asia-Pacific

Country Key Metric Key Driver
China 33.70% of regional share Export processing and commodity oil production
India 6.80% CAGR Organic cultivation expansion and Ayurvedic demand
Japan USD 8.65 Million Premium personal care and food flavoring
South Korea 7.15% CAGR K-beauty ingredient innovation
ASEAN USD 6.30 Million Traditional medicine and emerging spa tourism
Rest of Asia-Pacific 4.90% CAGR Emerging cultivation origins


Asia-Pacific remains the production and consumption epicenter of the ginger oil market. China's 67% export surge in 2025 widened the price gap between commodity and premium-grade oils, while India's Spices Board investments target quality improvements in steam distilled ginger essential oil to capture higher-value markets in Europe and North America [2][4].

South America

Country Key Metric Key Driver
Brazil 58.40% of regional share Organic ginger cultivation in Espírito Santo
Argentina USD 1.45 Million Herbal supplement market growth
Rest of South America 5.25% CAGR Peru and Colombia organic exports


Brazil leads the South American ginger oil market with expanding organic farming in its southeastern states. Peruvian and Colombian producers are positioning certified-organic ginger oleoresin and extract for direct export to EU food processors under preferential trade agreements [9].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28.50% of regional share Vision 2030 wellness sector investment
UAE 8.90% CAGR Luxury spa and wellness tourism
South Africa USD 1.85 Million Traditional medicine and cosmetics manufacturing
Egypt 7.60% CAGR Essential oil distillation capacity
Rest of MEA 32.10% of regional share Nigerian ginger cultivation and processing


The Middle East & Africa region posts the highest CAGR in the ginger oil market, propelled by GCC wellness tourism build-outs and Nigeria's emergence as a major ginger-producing origin. Saudi Arabia's Vision 2030 program has earmarked USD 2.8 billion for health and wellness infrastructure, directly benefiting aromatherapy and massage ginger oil imports [6].

Ginger Oil Market By Region, 2025-2035
 

Ginger Oil Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Conventional Ginger Oil 68.10% share (2025) Cost-competitive supply from China and India
Organic Ginger Oil 7.10% CAGR (2026–2035) Retailer mandates and consumer premiumization


Conventional grades continue to dominate the ginger oil market, accounting for roughly two-thirds of revenue. Chinese processors benefit from large-scale operations and lower labor costs, making conventional steam distilled ginger essential oil the default option for industrial food and fragrance applications. Organic oil, however, is closing the gap. Certified-organic supply from India, Peru, and Uganda is expanding as development agencies and private investors fund conversion programs. Retailers like Sephora and Whole Foods now mandate organic sourcing across private-label essential oil lines, creating pull-through demand that raises procurement volumes for organic ginger oleoresin and extract [5].

By Application

Segment Key Metric Primary Demand Driver
Food & Beverages 63.00% share (2025) Clean-label flavoring replacement
Pharmaceuticals & Nutraceuticals USD 30.85 Million (2025) Bioactive ingredient pipeline for anti-inflammatory formulations
Personal Care & Cosmetics 5.85% CAGR Scalp-care and anti-aging formulation trends
Aromatherapy & Wellness 7.78% CAGR (2026–2035) Mainstream wellness adoption
Fragrance & Perfumery USD 10.25 Million (2025) Warm-spicy accord demand in niche perfumery
Others 3.90% CAGR Industrial and household applications


Food & beverages anchors the ginger oil market by application, driven by the rapid expansion of culinary ginger flavoring oil use in craft sodas, ginger ales, Asian-fusion sauces, and confectionery. The aromatherapy & wellness segment is the fastest-growing, benefiting from the mainstreaming of aromatherapy and massage ginger oil in both professional spa settings and home diffuser use. Ginger oil anti-inflammatory use in topical balms and ingestible capsules is fueling growth in the pharmaceutical sub-segment, where suppliers of pharmaceutical-grade steam distilled ginger essential oil are investing in GMP-compliant facilities to meet clinical supply requirements [6][11].


Competitive Benchmarking

The ginger oil market exhibits medium concentration, with the top five players holding an estimated 32–38% combined revenue share. The competitive structure is fragmented below the top tier, populated by regional distillers, cooperative-owned processors, and vertically integrated spice conglomerates. An estimated HHI of 550–700 signals moderate fragmentation with room for M&A-driven consolidation.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Kancor Ingredients Ltd. ~6–9% Steam distilled ginger essential oil, oleoresins Vertically integrated Indian processor
Synthite Industries Ltd. ~5–8% Ginger oleoresin and extract, CO₂ extracts Largest spice oleoresin exporter globally
doTERRA International ~4–7% Therapeutic-grade essential oils, wellness kits DTC wellness and aromatherapy and massage ginger oil
Young Living Essential Oils ~4–6% Essential oil blends, supplements MLM distribution and farm-to-bottle sourcing
Robertet Group ~3–5% Natural aromatic raw materials, fragrance compounds French fragrance and flavor house
Givaudan SA ~3–5% Flavor and fragrance ingredients Global flavor integration for culinary ginger flavoring oil
Symrise AG ~2–4% Natural flavor systems, aroma molecules Sustainable sourcing partnerships in Madagascar
Sydney Essential Oil Co. (SEOC) ~2–3% Australian-distilled ginger oil, custom blends Premium-origin positioning
Guangxi Wanshan Spice Co. ~2–3% Commodity and conventional ginger oil Low-cost Chinese volume producer
Biolandes SAS ~1–3% Organic essential oils, aromatic extracts Fair-trade sourcing from tropical origins


Recent News & Developments


  • EU Commission (January 2026): published an update on the purity of essential oils, including the requirement for batch-level GC-MS reporting of single-origin oils sold above certain value thresholds, explicit labeling when products contain synthetic constituents or nature-identical aroma chemicals, and increased oversight of unsupported health or therapeutic claims, with phased timelines and technical assistance for micro-producers during the first two years.


Ginger Oil Market Report Scope

Parameter Detail
Market Scope Global ginger oil market covering conventional and organic product types across six application segments
Study Period 2021–2035
CAGR (Forecast Period) 5.65% (2026–2035)
Base Year Value USD 214.50 Million (2025)
Forecast Endpoint USD 371.60 Million (2035)
Fastest Growing Segment Organic Ginger Oil (by product type); Aromatherapy & Wellness (by application)
Companies Profiled 10 (Kancor, Synthite, doTERRA, Young Living, Robertet, Givaudan, Symrise, SEOC, Guangxi Wanshan, Biolandes)
Valuation Currency USD Million

FAQs

How does ginger oil shelf life vary between steam distillation and CO₂ extraction methods?
Steam distilled ginger essential oil typically retains potency for 2–3 years when stored properly, while CO₂ extracts last 3–5 years due to higher antioxidant retention. Cold storage below 15°C extends viability for both grades [17].
What minimum order thresholds do processors require for custom ginger oil blends in the ginger oil market?
Most commercial processors set MOQs at 50–100 kg for standard grades and 25–50 kg for certified-organic custom blends. Smaller buyers often source through consolidators who aggregate demand [15].
How do tariff structures affect ginger oil market pricing for cross-border buyers?
HS code 3301.29 attracts 3–8% import duties in most OECD markets, while LDC-origin shipments qualify for preferential rates under GSP programs. Tariff engineering via re-export hubs like Singapore can reduce landed costs by 5–12% [4].
What quality certifications matter most for ginger oleoresin and extract procurement?
ISO 9235, FEMA GRAS status, and EU Pharmacopoeia monograph compliance are baseline requirements. Organic buyers additionally demand USDA NOP or EU Organic certification with annual third-party audits [5].
How does the ginger oil market address batch-to-batch gingerol variability?
Processors use HPLC and GC-MS testing to standardize 6-gingerol content within ±3% tolerance. AI-driven blending algorithms now optimize multi-origin lot combinations to guarantee consistent bioactive profiles [8].
What insurance and logistics risks should buyers factor into ginger oil market sourcing strategies?
Marine cargo insurance for essential oils typically runs 0.4–0.8% of CIF value. Temperature excursion clauses are critical, as exposure above 35°C degrades terpene profiles in aromatherapy and massage ginger oil shipments [17].
How do blockchain traceability platforms impact pricing power in the ginger oil market?
Blockchain-verified supply chains command 10–18% price premiums in B2B channels. Buyers pay more for immutable origin and processing records that satisfy CSRD audit requirements [5][19].    
Author
Author Author Profile Varsha More LinkedIn Senior Research Analyst
Experienced business professional with a demonstrated history of working in the CFnB industry. Skilled in market research, and market estimation. Strong professional with a Masters focused in marketing management.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, agricultural statistics, essential oil industry publications, and authoritative health and food safety organizations. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), US Department of Agriculture (USDA) National Agricultural Statistics Service, Food and Agriculture Organization (FAO) of the United Nations, International Trade Centre (ITC) Trade Map, National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Traditional Medicine Strategy, European Medicines Agency (EMA) Herbal Medicinal Products Committee, India Ministry of Commerce & Industry (Spices Board), China National Health Commission, National Institute of Food and Agriculture (NIFA), Essential Oil Association of India (EOAI), International Federation of Essential Oils and Aroma Trades (IFEAT), and national agricultural ministry reports from key ginger-producing countries (India, China, Nigeria, Indonesia).

Clinical studies on therapeutic properties, production and trade statistics, regulatory approval data for food and pharmaceutical grades, cultivation trends, and market landscape analysis for steam distillation, solvent extraction, cold pressing, and CO2 extraction methods across food grade, pharmaceutical grade, cosmetic grade, and industrial grade segments were all gathered from these sources.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Operations, heads of agricultural sourcing, experts in extraction technology, and commercial directors from producers of ginger oil, distilleries, and essential oil extractors were examples of supply-side sources. Demand-side sources included purchasing leaders from flavor and fragrance houses, R&D directors from personal care and cosmetics manufacturers, procurement managers from food and beverage firms, and quality control heads from pharmaceutical companies. Primary research obtained information on raw material sourcing patterns, pricing volatility, organic certification trends, and supply chain dynamics. It also verified processing capacity expansions and validated market segmentation by extraction method and grade.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through production volume analysis and revenue mapping across the value chain. The methodology included:

Identification of 50+ key manufacturers and extractors across North America, Europe, Asia-Pacific, Latin America, and Africa

Product mapping across steam distillation, solvent extraction, cold pressing, and CO2 extraction methods

Grade-specific analysis covering food grade, pharmaceutical grade, cosmetic grade, and industrial grade segments

Analysis of reported and modeled annual revenues specific to ginger oil portfolios

Coverage of manufacturers and extractors representing 72-78% of global market share in 2024

Extrapolation using bottom-up (production volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations across liquid, paste, and powder forms

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















