Frozen Snacks Market (2026 - 2035)

Frozen Snacks Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Potato-based Snacks, Pizza Snacks, Meat-Based Snacks, Baked Snacks, Dairy-Based Snacks, Plant-Based Snacks, Others), By Distribution Channel (Retail (Supermarkets / Hypermarkets, Convenience / Grocery Stores, Online Retail Stores, Others), Foodservice), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Forecast Till 2035
ID: MRFR/FnB/6482-HCR 90 Pages Snehal Singh Last Updated: October 05, 2026
Frozen Snacks Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.86%
2025 Market SizeUSD 136.4 Billion
2035 Market SizeUSD 240.7 Billion
Key Players
McCain Foods Limited
Lamb Weston Holdings Inc.
Nestlé S.A.
Conagra Brands Inc.
General Mills Inc.
Tyson Foods Inc.
Opportunities
  • Cold-Chain-Enabled Expansion in South and Southeast Asia
  • Foodservice Menu Partnerships
  • Retail Media and Shopper-Data Models

Frozen Snacks Market Summary

The global Frozen Snacks Market was valued at USD 136.4 billion in 2025 and is projected to reach USD 144.2 billion in 2026, rising to USD 240.7 billion by 2035 at a CAGR of 5.86% over 2026–2035. Two catalysts anchor that path. India's Production Linked Incentive Scheme for the Food Processing Industry carries an outlay of INR 10,900 crore and directly subsidizes frozen and value-added capacity [12]. In the United States, the FDA's updated "healthy" nutrient-content claim rule is pushing manufacturers to reformulate sodium, saturated fat, and added sugar across freezer-aisle portfolios [9].

Production technology is shifting just as quickly. Older batch fryers and mechanical blast freezers are giving way to continuous individual quick freezing (IQF) tunnels, spiral freezers, and coatings engineered for air-fryer finishing, which let ready-to-eat food perform at home much as it does in a restaurant kitchen. Cold storage is moving to natural refrigerants as the Kigali Amendment requires developed economies to cut HFC consumption by 85% by 2036 [16].

Europe holds the largest regional position at a 34.6% share, supported by mature discount retail and high per-capita freezer ownership. Asia-Pacific is the fastest-growing region at a 7.4% CAGR, while North America, valued at USD 40.6 billion in 2025, remains the second-largest region on the strength of its quick-service restaurant base. Over the next decade, growth will tilt steadily toward emerging-market cold chains and foodservice channels.

Key Report Takeaways

• By Product Type

  • Potato-based Snacks led the Frozen Snacks Market with a 30.4% share in 2025, anchored by fries, wedges, and hash browns
  • Plant-Based Snacks are the fastest-growing product type, expanding at a 6.55% CAGR through 2035
  • Pizza Snacks generated USD 25.8 billion in 2025 on the back of family snacking and game-day occasions

• By Distribution Channel

  • Retail accounted for 58.9% of Frozen Snacks Market revenue in 2025, led by Supermarkets / Hypermarkets
  • Foodservice is forecast to grow at a 7.03% CAGR as operators cut kitchen labor

• By Region

  • Europe commanded a 34.6% share in 2025
  • Asia-Pacific will post the fastest regional CAGR at 7.4%
  • North America reached USD 40.6 billion in 2025

Market Size and Forecast (2021–2035)

Historical values combine company filings, national trade and production statistics, retail scanner panels, and interviews with manufacturers and distributors. Forecasts are built bottom-up by product type, channel, and country, then reconciled against top-down consumption and pricing indicators from USDA ERS, Eurostat, and FAO datasets [1][2][3].
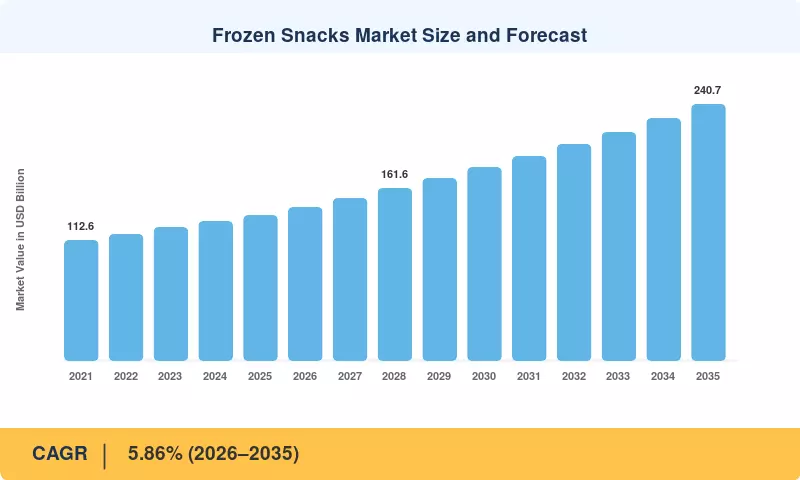
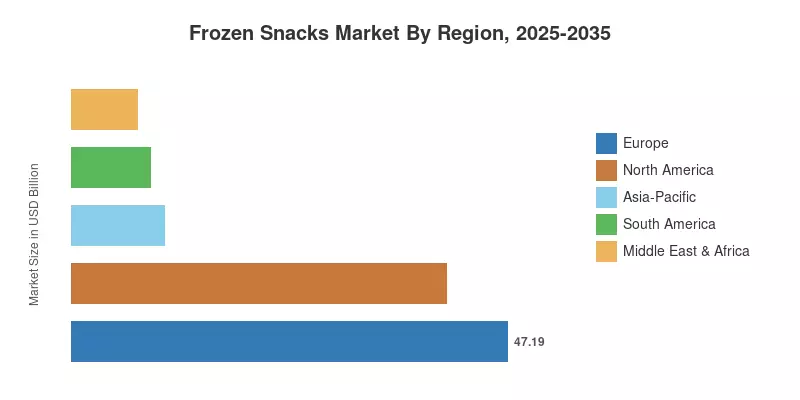
Frozen Snacks Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Urbanization and dual-income households +1.2% Global, strongest in Asia-Pacific Long-term (≥4 yr)
Foodservice labor efficiency +1.0% North America, Europe Medium-term (2–4 yr)
Air-fryer and home-appliance adoption +0.9% North America, Europe Short-term (≤2 yr)
Cold-chain build-out in emerging markets +0.8% Asia-Pacific, Middle East & Africa Long-term (≥4 yr)
Plant-based and better-for-you reformulation +0.6% Europe, North America Medium-term (2–4 yr)
E-grocery and private-label expansion +0.5% Global Short-term (≤2 yr)


Urbanization and Dual-Income Households

UN estimates show that, by 2050, 68% of the world's population will reside in cities, up from roughly 55% at the moment [4]. Urban households prefer portioned frozen snacks that cook in less than fifteen minutes because they cook in smaller kitchens, commute longer, and shop more frequently in contemporary retail formats. The impact is most noticeable in Asia-Pacific, where female labor force participation is increasing, and urban migration is concentrated, increasing the number of time-pressed purchasers.


Foodservice Labor Efficiency

Over half of U.S. food expenditures now come from eating out, USDA ERS data showed [1]. BLS reports that since 2021, food-service pay growth has been above the economy-wide average, indicating ongoing wage pressure on restaurant operators [5]. Pre-portioned and par-fried frozen snacks minimize spoilage, save prep processes, and standardize plating across sites. Frozen sides and appetizers are increasingly viewed by quick-service restaurants and delivery-only kitchens as a labor-substitution tool rather than a quality compromise.


Air-Fryer and Home-Appliance Adoption

Air fryers have moved from niche gadget to mainstream countertop appliance across the United States and the United Kingdom. Manufacturers now print air-fryer instructions on most potato and breaded SKUs, and McCain and Lamb Weston both cite air-fryer-specific coatings in recent investor materials [6][17]. Faster, oil-free preparation narrows the texture gap with restaurant fries. That keeps premium-priced products in rotation even when shoppers are cutting other discretionary spending.

Cold-Chain Build-Out in Emerging Markets

India's Pradhan Mantri Kisan Sampada Yojana, with an allocation of INR 4,600 crore through 2026, funds integrated cold-chain and value-addition projects [12]. FAO estimates that about 13% of food is lost between harvest and retail, much of it from inadequate refrigeration [13]. Each new reefer warehouse and distribution hub widens the area in which frozen snacks can be sold reliably. Tier-2 and tier-3 cities across South and Southeast Asia stand to gain most.

Plant-Based and Better-for-You Reformulation

The FDA's final rule on the "healthy" claim, issued in December 2024 with a compliance date of February 2028, sets limits on sodium, saturated fat, and added sugar [9]. Producers are responding with baked coatings, vegetable-forward fillings, and legume-based proteins. Europe's flexitarian shoppers are adopting these products faster than meat-free purists, which explains why plant-based ranges now sit next to conventional lines rather than in separate vegan bays.

E-Grocery and Private-Label Expansion

Insulated delivery and dark-store fulfillment have removed much of the friction from buying frozen items online. Panel data show private-label frozen share rising through 2023 and 2024 as shoppers traded down [18]. Retailers such as Aldi, Lidl, and Walmart use exclusive frozen snack lines to build basket size. That widens access to the category at lower price points while pushing branded makers toward innovation and premium tiers.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Potato and edible-oil price volatility −0.7% Europe, North America Short-term (≤2 yr)
Cold-chain energy costs −0.6% Global Medium-term (2–4 yr)
Nutrition labeling and HFSS rules −0.5% Europe, North America Medium-term (2–4 yr)
Fresh and chilled substitution −0.4% North America, Europe Long-term (≥4 yr)
Packaging sustainability compliance −0.3% Europe Long-term (≥4 yr)


Potato and Edible-Oil Price Volatility

Contract potato prices increased significantly in 2022 and 2023 due to heat and drought in northwest Europe, while FAOSTAT data indicates that yields vary annually among key producers [3]. In October 2024, Lamb Weston announced facility closures and a roughly 4% job decrease, citing raw-material costs and lower volumes [7]. After 2022, edible-oil rises made it harder for fried forms to make a profit.


Cold-Chain Energy Costs

Estimates from the International Institute of Refrigeration showed that refrigeration uses around one-fifth of the world's power [14]. The cost of carrying and storing deep-frozen cargo has increased due to European power rates, which are still significantly higher than they were before 2021. In price-sensitive markets, capacity increases are slowed because smaller producers without long-term energy contracts find it difficult to absorb these expenses.


Nutrition Labeling and HFSS Rules

The FDA proposed front-of-package nutrition labeling in January 2025, which would flag high sodium and saturated fat on many fried and cheese-filled snacks [10]. In the United Kingdom, HFSS rules restrict promotional placement, and a ban on paid online advertising of such products takes legal effect in January 2026 [19]. Both measures raise reformulation costs and limit in-store promotions.

Fresh and Chilled Substitution

UNEP's Food Waste Index Report 2024 found that 19% of food available to consumers is wasted, a figure retailers increasingly use to justify chilled, short-dated meal kits [15]. In North America, chilled deli and prepared-meal counters compete directly for the same snacking occasions. Some shoppers still regard frozen formats as less fresh, a perception that caps premium pricing.

Packaging Sustainability Compliance

The EU Packaging and Packaging Waste Regulation, published in January 2025, requires all packaging to be recyclable by 2030 [11]. Frozen snacks rely on multilayer films and poly-coated cartons that are hard to recycle. Redesigning packs for moisture and freezer-burn protection while meeting recyclability rules adds cost and testing time, especially for mid-sized European brands.

Frozen Snacks Market Opportunities

Cold-Chain-Enabled Expansion in South and Southeast Asia

India, Indonesia, and Vietnam combine fast-growing modern retail with low current per-capita frozen consumption. Subsidized cold storage under PMKSY [12] and private reefer investment create room for localized formats such as samosas, spring rolls, and dumplings. Producers that build regional plants rather than import will win on price and freshness.

Foodservice Menu Partnerships

Quick-service and casual-dining chains want signature sides without added labor. Co-developed coatings, sauces, and shapes under multi-year supply contracts give manufacturers stable volume and pricing power. Frozen appetizers built for delivery, with coatings that stay crisp for 20 minutes or more, address the biggest complaint in off-premise dining.

Retail Media and Shopper-Data Models

Retailer loyalty programs and e-grocery platforms now sell sponsored placement and purchase data to brands. Frozen snack makers can use this data to target air-fryer owners, flexitarians, or households with children, and to test limited-edition flavors with low risk. Direct-to-consumer bundles and subscription boxes offer a second, smaller data channel.

Better-for-You Reformulation Ahead of the 2028 Deadline

Brands that meet the FDA "healthy" thresholds early can use the claim on pack as soon as products qualify [9]. Baked coatings, vegetable-based crusts, and reduced-sodium seasonings offer a route to shelf differentiation before competitors catch up.

Gulf Hospitality and Tourism Demand

Saudi Arabia's Vision 2030 tourism targets and the UAE's hotel expansion pipeline drive institutional demand for consistent, halal-certified snacks. Import-dependent supply chains leave room for regional co-manufacturing.

Frozen Snacks Market Future Outlook

Automation and Data-Driven Plants

Vision systems, predictive maintenance, and AI-tuned fryer and freezer controls will lower waste and energy use. Labor shortages in North American and European plants make automation a necessity rather than an option. Plants that adopt these tools can cut energy per tonne and improve yield consistency, which matters more as raw-material prices swing.

Nutrition Shifts and GLP-1 Medications

Wider use of GLP-1 weight-loss drugs is changing portion sizes and snacking frequency in the United States. Nestlé's Vital Pursuit line, launched in 2024, shows how producers are designing higher-protein, smaller-portion formats for these consumers [8]. Expect protein-forward and fiber-fortified snacks to gain shelf space through 2035.

Low-Carbon Cold Chains

The Kigali Amendment's HFC phase-down [16] and rising energy prices will push warehouses and transport fleets toward CO2 and ammonia refrigeration. Producers will increasingly report Scope 3 emissions from cold storage, and retailers will favor suppliers with lower-carbon logistics.

Quick Commerce and Channel Economics

Ten-to-thirty-minute delivery platforms in India, the Middle East, and parts of Europe are building dark stores with dedicated freezer capacity. These platforms favor single-serve and multipack formats with high turnover, creating a new channel that sits between traditional retail and foodservice.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 40.6 Billion QSR supply contracts, air-fryer innovation
Europe 34.6% share Discount retail, plant-based ranges, packaging redesign
Asia-Pacific 7.4% CAGR Cold-chain build-out, localized formats
South America 6.3% share Modern retail expansion, potato processing capacity
Middle East & Africa USD 7.1 Billion Hospitality demand, halal certification
Total USD 136.4 Billion —

The Frozen Snacks Market shows a clear split between mature, retail-led Western regions and fast-growing, foodservice-led emerging regions. Europe leads on share, while Asia-Pacific sets the pace on growth.


North America

Country Metric (2025) Key Driver
United States 82.4% share of region QSR density and air-fryer adoption
Canada 5.4% CAGR Domestic potato processing capacity
Mexico USD 2.6 Billion Modern retail and convenience-store growth


North America's Frozen Snacks Market is shaped by the scale of U.S. quick-service chains, which buy par-fried potatoes and breaded items under long-term contracts. Pacific Northwest potato processing, led by Lamb Weston and Simplot, supplies both domestic and export demand. Canada's Alberta and Prince Edward Island processing belts feed U.S. retail, while Mexico's expanding OXXO network supports single-serve formats.

Europe

Country Metric (2025) Key Driver
Germany 21.8% share of region Discount-store frozen ranges
United Kingdom USD 8.1 Billion Air-fryer penetration and private label
France 4.9% CAGR Premium aperitif snacks
Italy 11.6% share of region Frozen pizza snacks
Rest of Europe USD 13.9 Billion Benelux processing and Nordic demand


European demand rests on high freezer ownership and the reach of Aldi and Lidl, whose private-label ranges set price benchmarks. Belgium and the Netherlands host Europe's largest potato processing clusters. Regulatory pressure is the strongest here: the PPWR recyclability mandate [11] and UK HFSS rules [19] are forcing packaging and recipe changes across the continent.

Asia-Pacific

Country Metric (2025) Key Driver
China 34.5% share of region Convenience-store and delivery platforms
Japan USD 7.2 Billion Mature konbini and bento culture
India 9.6% CAGR PLI and PMKSY cold-chain incentives
Australia 7.8% share of region Supermarket private label
Rest of Asia-Pacific USD 7.6 Billion Southeast Asian modern retail


Asia-Pacific growth rests on new cold-chain capacity and localized products such as dumplings, gyoza, and spring rolls. China's delivery platforms create steady foodservice pull. India is the standout growth market, as PLI incentives [12] attract multinational and domestic investment in frozen potato and vegetable snack lines.

South America

Country Metric (2025) Key Driver
Brazil 48.6% share of region Supermarket expansion and cheese bread snacks
Argentina 5.8% CAGR Export-oriented potato processing
Rest of South America USD 2.3 Billion Chile and Colombia modern retail


Brazil dominates regional demand through frozen pão de queijo and pizza snacks sold in large supermarket chains. Argentina has become a frozen fries exporter, with McCain operating a plant in Balcarce. Currency volatility remains the main risk, pushing producers to source locally rather than import.

Middle East & Africa

Country Metric (2025) Key Driver
Saudi Arabia 7.8% CAGR Vision 2030 tourism and hospitality
United Arab Emirates 19.4% share of region Hotel and airline catering
South Africa USD 1.6 Billion Established supermarket chains
Rest of Middle East & Africa 41.2% share of region Urbanization in Egypt and Nigeria


Gulf markets depend heavily on imports, though Saudi Arabia is encouraging domestic food manufacturing under its National Industrial Development and Logistics Program. Halal certification is a basic entry requirement. South Africa's chains, including Shoprite and Pick n Pay, provide the most developed retail freezer infrastructure on the continent.

Frozen Snacks Market By Region, 2025-2035

Frozen Snacks Market Segmentation

By Product Type

Segment Metric (2025) Primary Demand Driver
Potato-based Snacks 30.4% share QSR sides and home air-frying
Pizza Snacks USD 25.8 Billion Family snacking and game-day occasions
Meat-Based Snacks 17.1% share Protein-led snacking
Baked Snacks 5.9% CAGR Lower-fat positioning
Dairy-Based Snacks USD 9.4 Billion Cheese sticks and filled pastries
Plant-Based Snacks 6.55% CAGR Flexitarian demand
Others 4.6% share Ethnic and regional formats


In the Frozen Snacks Market, Potato-based Snacks lead because fries, wedges, and hash browns are cheap, familiar, and easy to cook, and potato supply is large and stable. Pizza Snacks and Meat-Based Snacks follow, driven by family and protein snacking. Plant-Based Snacks grow fastest as brands use legumes, vegetables, and grain proteins to match the taste and texture of meat-based options, supported by clean-label and animal-welfare concerns.

By Distribution Channel

Segment Metric (2025) Primary Demand Driver
Retail 58.9% share At-home consumption and promotions
— Supermarkets / Hypermarkets 58.2% share of retail Wide assortment and bulk packs
— Convenience / Grocery Stores 26.4% share of retail Impulse and single-serve buying
— Online Retail Stores 9.6% share of retail E-grocery and quick commerce
— Others 5.8% share of retail Specialty and club formats
Foodservice 7.03% CAGR Labor savings and menu standardization


Retail remains the largest channel in the Frozen Snacks Market, with Supermarkets / Hypermarkets offering broad ranges, promotions, and family packs that encourage stocking up. Convenience / Grocery Stores and Online Retail Stores add impulse and delivery-based buying. Foodservice grows fastest because restaurants, cafés, and institutional kitchens use pre-processed snacks to cut prep time, keep portions consistent, and limit spoilage.

Competitive Benchmarking

The Frozen Snacks Market is fragmented, with an estimated Herfindahl-Hirschman Index below 600 and the top five companies holding roughly 20–24% of global revenue. Large multinationals dominate potato and pizza formats, while regional players and private labels compete strongly in local and ethnic snacks.

Company Est. Revenue Share Range Key Offerings for Frozen Snacks Market Strategic Positioning
McCain Foods Limited ~5–7% Fries, wedges, appetizers, potato specialties Global leader in potato formats with broad QSR ties
Lamb Weston Holdings Inc. ~4–6% Par-fried potatoes, coated fries Foodservice-focused, restructuring for cost efficiency
Nestlé S.A. ~3–5% Hot Pockets, pizza snacks Portfolio shift toward protein and portion control
Conagra Brands Inc. ~3–5% Bagel bites alternatives, appetizers, Birds Eye snacks Strong U.S. retail freezer presence
General Mills Inc. ~2–4% Totino's pizza rolls, Pillsbury snacks Family snacking in North American retail
The Kraft Heinz Company ~2–4% Bagel Bites, Ore-Ida Brand-led retail positioning
Tyson Foods Inc. ~2–3% Breaded chicken snacks, Jimmy Dean Protein-based snacks across retail and foodservice
Nomad Foods Limited ~1.5–3% Birds Eye, Findus, Iglo snacks Europe's leading branded frozen player
Ajinomoto Co. Inc. ~1.5–3% Gyoza, dumplings, Asian appetizers Asian formats with U.S. expansion
J.R. Simplot Company ~1–2% Fries, potato specialties Integrated grower-processor
J&J Snack Foods Corp. ~1–2% Soft pretzels, churros Niche foodservice and retail snacks


Recent News & Developments

  • Lamb Weston (February 2023): Completed the purchase of the remaining stake in its European joint venture, Lamb Weston/Meijer, giving it full control of key Dutch and UK potato processing capacity [6]
  • Nestlé USA (May 2024): Launched Vital Pursuit, a frozen line with higher protein and fiber aimed at GLP-1 users, signaling a shift toward nutrition-led portion formats [8]
  • Lamb Weston (October 2024): Announced plant closures and an approximately 4% workforce cut, citing softer volumes and raw-material costs [7]
  • U.S. FDA (December 2024): Finalized the updated "healthy" claim rule with a February 2028 compliance date, triggering reformulation programs [9]
  • European Union (January 2025): Published the Packaging and Packaging Waste Regulation, requiring recyclable packaging by 2030 [11]
  • U.S. FDA (January 2025): Proposed mandatory front-of-package nutrition labeling covering sodium, saturated fat, and added sugar [10]
  • The Kraft Heinz Company (September 2025): Announced plans to split into two companies, a move that could reshape its frozen snack portfolio [20]

Frozen Snacks Market Report Scope

Parameter Details
Market Scope Global frozen snacks across product types, distribution channels, and five regions
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 5.86% (2026–2035)
Market Size Checkpoints USD 136.4 Billion (2025); USD 144.2 Billion (2026); USD 191.7 Billion (2031); USD 240.7 Billion (2035)
Fastest Growing Segments Plant-Based Snacks (product type); Foodservice (distribution channel); Asia-Pacific (region)
Companies Profiled McCain Foods, Lamb Weston, Nestlé, Conagra Brands, General Mills, Kraft Heinz, Tyson Foods, Nomad Foods, Ajinomoto, J.R. Simplot, J&J Snack Foods
Valuation Currency USD Billion

FAQs

What should investors watch most closely in the Frozen Snacks Market?
Potato contract pricing is the key margin signal. Processors negotiate annual grower contracts, so a poor European harvest can compress earnings for a full year [3].
How do buyers evaluate suppliers in the Frozen Snacks Market?
Large buyers prioritize hold-time performance, consistent cut size, and supply security across multiple plants. Food-safety certification under GFSI-benchmarked schemes such as BRCGS is usually a baseline requirement.
Which certifications matter for Gulf export?
Halal certification from an authority recognized by the destination country is mandatory. Saudi Arabia's SFDA also requires product registration before customs clearance.
Is co-manufacturing a viable entry route in the Frozen Snacks Market?
Yes, for new brands, it lowers capital risk. Co-packers with IQF and coating lines let startups test plant-based or regional formats before building dedicated capacity.
How does quick commerce affect pack design?
Dark stores have limited freezer space, so they favor compact, high-turnover multipacks. Brands increasingly create channel-specific pack sizes for these platforms.
What role do natural refrigerants play for producers?
CO2 and ammonia systems avoid future HFC phase-down costs under the Kigali Amendment [16]. Upfront costs are higher, but lower operating expenses improve long-term plant economics.
How are retailers using private label strategically?
Retailers use own-brand frozen snacks to anchor price perception and lift margins. Premium private-label tiers now compete directly with mid-priced national brands [18].
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of food regulatory databases, industry associations, market intelligence reports, and peer-reviewed food science publications. Key sources included the US Food & Drug Administration (FDA), US Department of Agriculture (USDA), European Food Safety Authority (EFSA), Food and Agriculture Organization of the United Nations (FAO), Codex Alimentarius Commission, National Frozen & Refrigerated Foods Association (NFRA), American Frozen Food Institute (AFFI), European Frozen Food Association (EFFA), Food Marketing Institute (FMI), National Restaurant Association (NRA), Centers for Disease Control and Prevention (CDC) National Health and Nutrition Examination Survey, Bureau of Labor Statistics Consumer Expenditure Surveys, Eurostat Food Consumption Database, and national food safety agencies from key markets. These sources were utilized to collect production statistics, retail volume data, cold chain logistics trends, consumer consumption patterns, and regulatory compliance requirements for frozen appetizers, pizza, handheld sandwiches/burritos, bakery snacks, and plant-based frozen alternatives.


Primary Research

Stakeholders from both the supply and demand sides of the frozen snacks value chain were involved in the primary study process to get both qualitative and quantitative information. Chief Executive Officers, Vice Presidents of Innovation and Product Development, supply chain directors, and category managers from frozen snack makers, co-packers, and cold storage operators were some of the supply-side sources. Demand-side sources included category buyers from grocery stores and convenience stores, procurement managers from foodservice distributors, supply chain leaders from quick-service restaurants (QSRs), and deli/ready-meal section managers from retail stores. Primary research confirmed the division of products into categories such as frozen appetizers, pizza, handheld snacks, and specialty bakery items; it also confirmed the timelines for new products; and it gathered information on how prices change, how to promote products, how freezer space is used, and the rate of private label penetration.

Primary Respondent Breakdown:

By Designation: C-level Executives (30%), Director Level (35%), Others (35%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and volume analysis across retail and foodservice channels. The methodology included:

Identification of 50+ key manufacturers and private label suppliers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across frozen appetizers/starters, pizza, handheld snacks (sandwiches/wraps/burritos), frozen bakery snacks, and meat/poultry/vegetarian snack categories

Analysis of reported and modeled annual revenues specific to frozen snack portfolios, including retail scanner data and foodservice distribution records

Coverage of manufacturers and brands representing 72-78% of global market share in 2024

Extrapolation using bottom-up (retail volume × ASP by country/region plus foodservice volume × wholesale price) and top-down (manufacturer revenue validation and trade association aggregation) approaches to derive segment-specific valuations across distribution channels (supermarkets/hypermarkets, convenience stores, online retail, foodservice)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















