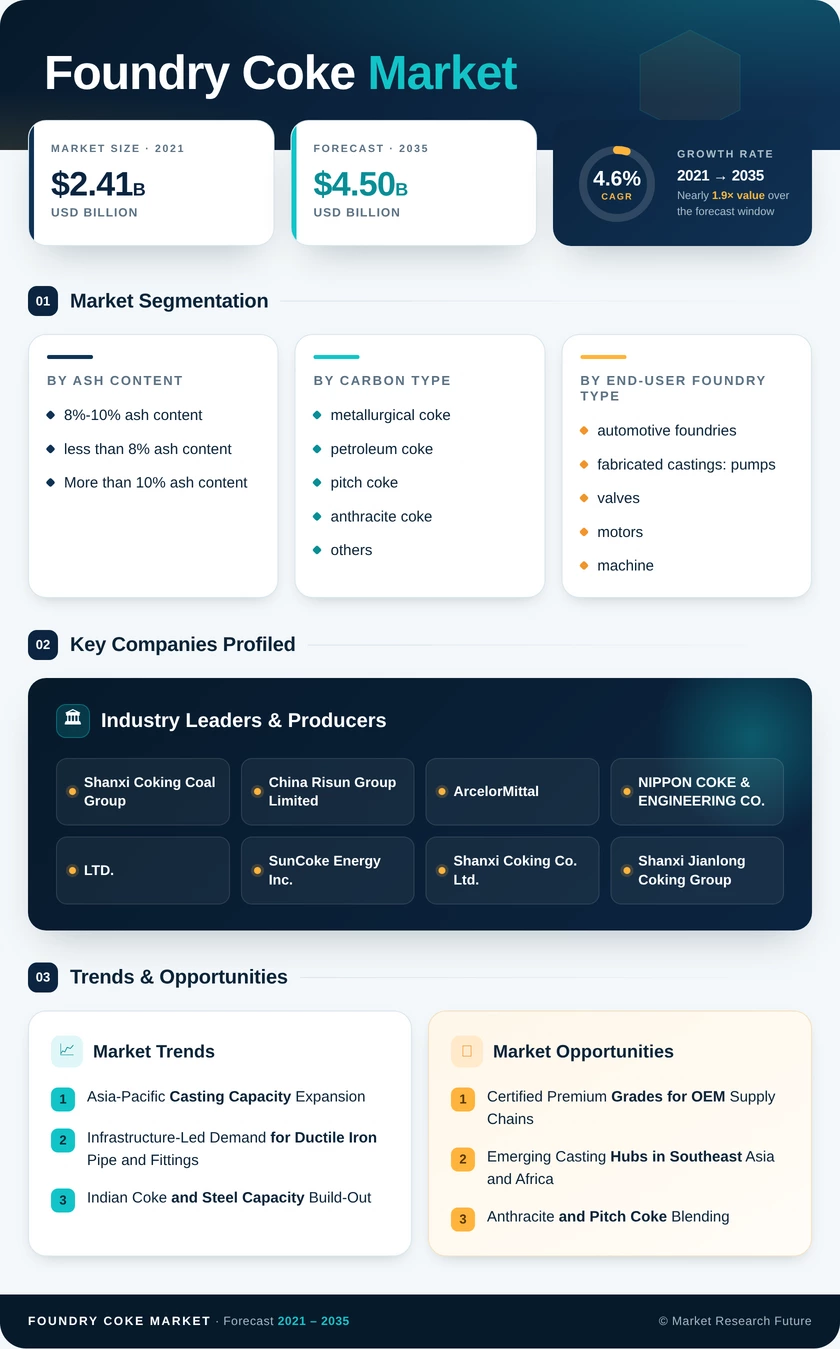
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Ash Content | 8%-10% ash content; less than 8% ash content; More than 10% ash content | 8%-10% ash content (47.0% share) | less than 8% ash content (5.1% CAGR) |
| By Carbon Type | metallurgical coke; petroleum coke; pitch coke; anthracite coke; others | metallurgical coke (63.7% share) | petroleum coke (5.2% CAGR) |
| By End-user Foundry Type | automotive foundries; fabricated castings: pumps, valves, motors; machine and tool manufacturing; aerospace and heavy equipment; other industrial foundries | automotive foundries (39.7% share) | aerospace and heavy equipment (4.9% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (58.4% share) | Asia-Pacific (58.4% share) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| 8%-10% ash content | Blended with premium grades to pass OEM audits at controlled cost |
| less than 8% ash content | Low-ash contracts spreading across automotive and aerospace foundries |
| More than 10% ash content | Retained by price-driven municipal and agricultural casters |
The 8%-10% ash content grade leads on volume because municipal and construction-equipment foundries accept its slag load in exchange for lower cost. The less than 8% ash content grade grows fastest, as automotive and aerospace casters link low ash to fewer inclusions and longer refractory life. The More than 10% ash content grade persists only where price outweighs defect risk.
| Sub-Segment | Key Trend |
|---|
| metallurgical coke | Remains the structural fuel for cupola beds |
| petroleum coke | Gains on carbon purity and cost where sulfur limits allow |
| pitch coke | Niche recarburizer for induction and aerospace melts |
| anthracite coke | Briquettes partly replace met coke to cut emissions |
| others | Semi-coke and blended lots tailored to furnace chemistry |
Metallurgical coke keeps the lead because its strength holds the cupola bed under load, a property cheaper carbons cannot fully match. The petroleum coke segment grows fastest as foundries with sulfur headroom exploit its high carbon content and lower price. Anthracite coke and pitch coke serve as targeted blend components rather than full substitutes.
| Sub-Segment | Key Trend |
|---|
| automotive foundries | Electrified and hybrid platforms still need ductile iron parts |
| fabricated castings | Pump, valve and motor castings tied to water and energy projects |
| machine and tool manufacturing | Heavy machine-tool beds and press frames |
| aerospace and heavy equipment | Aircraft and mining-equipment backlogs lift premium demand |
| other industrial foundries | Price-driven municipal and agricultural castings |
Automotive foundries remain the largest buyers because brake, suspension and housing parts stay in cast iron even on electrified platforms. The aerospace and heavy equipment segment grows fastest, driven by aircraft backlogs and mining-equipment orders that specify ash below 8%. Fabricated castings for pumps, valves and motors provide steady volume linked to infrastructure spending.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA