EV Charging Management Software Platform Market (2026 - 2035)

EV Charging Management Software Platform Market Research Report By Module (Operations Management, Energy Management, Billing and Payment Management, Analytics and Reporting, Customer and Driver Management, User Access Control, Others), By Deployment Type (Cloud-Based, On-Premise), By Charger Type (Level 1, Level 2, Level 3), By Charging Site (Public Charging Infrastructure, Private Charging Infrastructure), By End User (Charge Point Operators, Fleet Operators, Utilities and Energy Providers, Automotive OEMs, Retail and Hospitality Site Hosts) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/AT/11180-CR 179 Pages Shubham Munde, Swapnil Palwe Last Updated: September 15, 2026
EV Charging Management Software Platform Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)26.0%
2025 Market SizeUSD 2.58 Billion
2035 Market SizeUSD 26.04 Billion
Key Players
ChargePoint Holdings
Driivz
ABB E-mobility
Everon
EV Connect
AMPECO
Opportunities
  • Grid Services as a Second Revenue Line
  • Emerging-Market Leapfrogging
  • Data Monetisation and Site Intelligence

EV Charging Management Software Platform Market Summary

The EV Charging Management Software Platform Market reached USD 2.58 Billion in 2025 and enters the forecast window at USD 3.25 Billion in 2026, climbing to USD 26.04 Billion by 2035 at a 26.0% CAGR. Two catalysts anchor that trajectory. The U.S. National Electric Vehicle Infrastructure program committed USD 5 billion across five years to corridor charging, and the EU's Alternative Fuels Infrastructure Regulation set binding kilometre-interval targets along the TEN-T network [1][4]. Neither obligation can be met without backend orchestration.

Operators are retiring proprietary, charger-vendor-locked controllers and replacing them with protocol-agnostic cloud backends that speak OCPP 2.0.1 and OCPI. That shift matters commercially: the International Energy Agency estimates global public charging investment exceeded USD 26 billion in 2024, and roughly 6–8% of that capital now flows to software and integration rather than steel and silicon [1][3]. Legacy SCADA-style monitoring simply cannot handle dynamic pricing, roaming settlement, and depot scheduling in one stack.

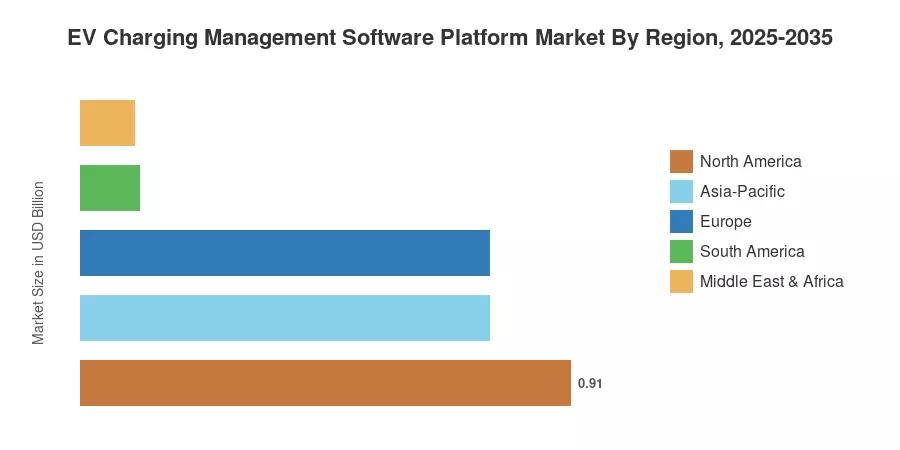
North America holds 35.2% of the EV Charging Management Software Platform Market on the strength of federal funding and dense fleet pilots. Asia-Pacific grows fastest at a 29.4% CAGR, powered by China's connector base and India's FAME-successor incentives. Europe follows North America at 29.4% share, where regulatory pressure — not subsidy — drives adoption. Expect the gap between these three blocs to narrow sharply after 2030 as the EV Charging Management Software Platform Market matures into a settlement and grid-services layer.


Key Report Takeaways

• By Module

  • Operations Management commanded 29.1% of the EV Charging Management Software Platform Market in 2025, reflecting its role as the mandatory first purchase for any network operator
  • Analytics and Reporting posts the fastest module growth at a 29.9% CAGR through 2035
  • Billing and Payment modules reach USD 4.76 Billion by 2035 as consumer-protection rules tighten

• By Deployment Type

  • Cloud-based deployment captured 68.1% share in 2025, and on-premise retention is now confined to utility and defence sites


• By Charger Type


  • Level 3 software workloads expand at a 30.0% CAGR, outpacing the wider EV Charging Management Software Platform Market


• By End user


  • Charge Point Operators held 44.3% share among end users, while Fleet Operators advanced at a 30.1% CAGR

• By Region

  • North America led the EV Charging Management Software Platform Market with 35.2% share in 2025
  • Asia-Pacific records a 29.4% CAGR, the fastest of any region
  • Europe generated USD 0.76 Billion in 2025 revenue, concentrated in Germany and the Nordics


Market Size and Forecast (2021–2035)

Estimates blend charger-installation telemetry from national registries, disclosed SaaS revenue from listed platform vendors, and a bottom-up connector-count model cross-checked against utility interconnection filings. Historical years reflect actual reported revenue; forecast years apply a declining-growth curve consistent with connector-base saturation in mature corridors.
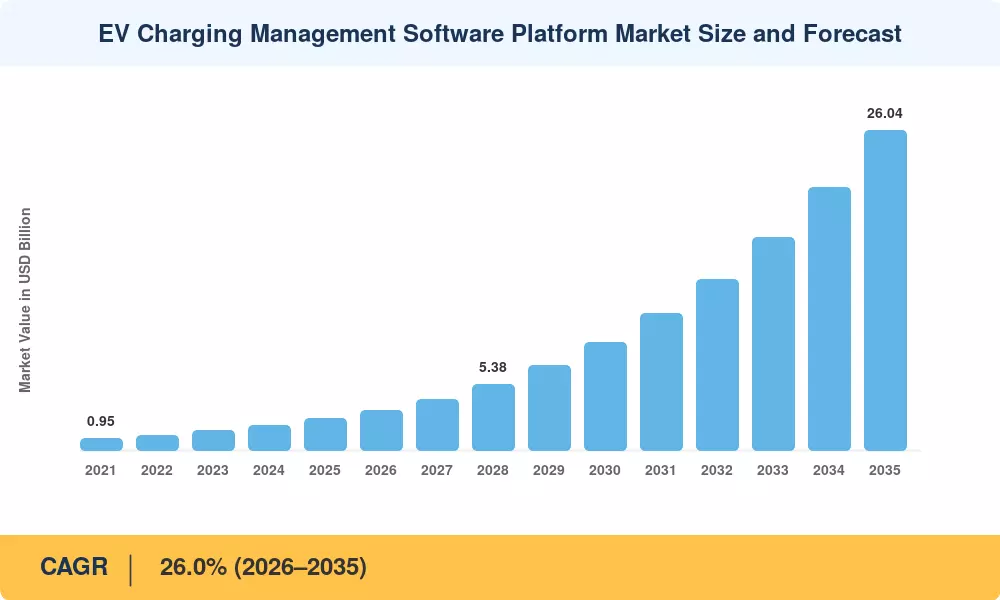
EV Charging Management Software Platform Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
National charging infrastructure funding programs +4.2 North America, Europe Medium-term (2–4 yr)
Corporate and municipal fleet electrification targets +3.8 Global Medium-term (2–4 yr)
Interoperability and roaming standardisation +3.1 Europe, North America Short-term (≤2 yr)
Grid-constrained sites requiring dynamic load management +2.9 Europe, Asia-Pacific Long-term (≥4 yr)
Payment transparency and consumer-protection rules +2.4 Europe, North America Short-term (≤2 yr)
Cloud migration among charge point operators +2.2 Global Medium-term (2–4 yr)
Vehicle-grid integration and bidirectional pilots +1.9 North America, Asia-Pacific Long-term (≥4 yr)


Public Funding Converts Into Software Obligations

There are conditions attached to every dollar of NEVI money. Spreadsheets are unable to meet the standards for awardees, which include maintaining five years of operating records, reporting uptime above 97%, and exposing data through standardized APIs [4]. The EV Charging Management Software Platform Market is now a procurement floor for state DOT tenders, according to the Federal Highway Administration's minimum criteria, which essentially put a software specification into a construction grant.


Fleet Electrification Shifts the Buyer Profile

Compared to public networks, depot operators make distinct purchases. Route-aware charge sequencing, demand-charge avoidance, and telematics reconciliation are more important to an 80-vehicle logistics yard than roaming. Tens of thousands of vehicles are forced into scheduled nighttime charging under California's Advanced Clean Fleets framework and similar EU corporate-fleet ideas, where a 15-minute dispatch error can result in peak demand costs at commercial tariffs of USD 400 [7][9].


Standards Compression Lowers Switching Costs

Adoption of OCPP 2.0.1 alongside OCPI 2.2.1 has made backend replacement genuinely feasible for the first time. The Open Charge Alliance reported certified product listings roughly doubling between 2023 and 2025 [5]. Lower switching friction cuts both ways: it accelerates displacement of incumbent controllers while compressing renewal pricing for platform vendors.


Restraints Impact Analysis


Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Charger reliability disputes eroding operator trust −2.6 North America Short-term (≤2 yr)
Fragmented protocol implementations and integration cost −2.2 Global Medium-term (2–4 yr)
Utility interconnection and capacity delays −1.9 North America, Europe Long-term (≥4 yr)
Platform commoditisation and margin compression −1.6 Europe Medium-term (2–4 yr)
Cybersecurity and data-protection compliance burden −1.3 Global Long-term (≥4 yr)


The Uptime Credibility Problem

Real-world session success rates in the 72–80% range, far below advertised availability, have been consistently reported in field trials of public fast charging in the United States [10]. Even when a payment terminal or connector latch is at fault, software is still held accountable. Procurement committees devalue uptime claims and postpone multi-year commitments until platforms can demonstrate diagnostic cause.


Integration Cost Outruns Licence Cost

Implementations of partial protocols are still common. Every hardware SKU requires custom compliance work because a charger promoting OCPP 1.6J might leave out reservation messages or smart-charging profiles. On heterogeneous estates, integration and testing typically cost 1.5–2.5 times the first-year licence fee. This hidden cost slows tenders and drives smaller operators toward single-vendor lock-in [5][15].


EV Charging Management Software Platform Market Opportunities

Grid Services as a Second Revenue Line

Aggregating flexible charging load into ancillary-service markets converts a cost centre into an earnings stream. PJM and National Grid ESO programs already accept aggregated demand response at sub-megawatt thresholds, and platforms that qualify assets automatically capture a share of settlement [3][14]. This is the clearest near-term margin expansion available to the EV Charging Management Software Platform Market.

Emerging-Market Leapfrogging

India, Indonesia and Brazil are building charging networks without legacy controller estates. Operators there adopt cloud-native, mobile-first backends from day one, often bundled with two- and three-wheeler swapping [2][18]. Vendors that price in local currency and support UPI-style instant payments will win share that incumbents cannot easily contest.

Data Monetisation and Site Intelligence

Session data reveals dwell time, vehicle mix and repeat-visit behaviour — inputs retail landlords, insurers and grid planners will pay for. Anonymised utilisation feeds already command subscription pricing in the USD 15,000–60,000 annual range from utility planning teams [17]. Consent architecture, not analytics capability, is the binding constraint.

Megawatt Charging for Heavy Duty

Truck corridors demand dispatch logic operating at millisecond granularity across battery buffers and on-site generation. Early MCS deployments in Germany and California suggest platform content per site runs 3–4× that of a passenger fast-charging hub, materially raising average contract value within the EV Charging Management Software Platform Market [8][19].

White-Label Backends for Utilities and OEMs

Automakers and distribution utilities increasingly want branded charging experiences without building software. Licensing a white-label backend shortens time to market from roughly 24 months to under nine, and it locks in multi-year renewals tied to vehicle platform cycles [12].


EV Charging Management Software Platform Market Future Outlook

Autonomous Operations Take Over Dispatch

Rule-based load balancing gives way to forecast-driven optimisation as sites add storage and on-site solar. A smart EV charging management platform will increasingly bid capacity into day-ahead markets without human approval, using price forecasts and vehicle-departure predictions. The IEA projects global EV electricity demand approaching 1,000 TWh by 2035, a volume no manual scheduling regime can absorb [1][14].

Platform Economics Bifurcate

Pricing splits along two axes. Public-network vendors defend per-connector monthly fees under commoditisation pressure, while depot and fleet vendors shift toward per-vehicle or outcome-linked terms tied to demand-charge savings. Expect blended gross margins to compress from the mid-70s toward the mid-60s as integration services grow as a revenue share [12].

The Heavy-Duty Supercycle

Trucking electrification arrives late but hits hard. BloombergNEF scenarios place medium- and heavy-duty electric vehicle sales above 20% of new units in leading markets by the mid-2030s [20]. Each depot represents multi-megawatt load, on-site storage, and grid-interactive obligations — the highest software content per site anywhere in the sector.

Reporting Becomes a Product Requirement

CSRD in Europe and comparable disclosure regimes elsewhere force fleet owners to report Scope 1 and Scope 2 emissions at asset granularity. The EV Charging Management Software Platform Market responds by embedding auditable carbon-intensity attribution per session, sourced from grid-mix APIs. Verification, not calculation, becomes the differentiator [13][17].


Regional Market Share Analysis

Region 2025 Metric Primary Investment Themes
North America 35.2% share Corridor funding, depot electrification, demand-charge management
Europe USD 0.76 Billion AFIR compliance, roaming settlement, payment transparency
Asia-Pacific 29.4% CAGR Connector scale, battery swapping, two-wheeler networks
South America USD 0.11 Billion Urban bus fleets, retail site hosting
Middle East & Africa 3.7% share Sovereign mobility programs, hospitality charging
Total USD 2.58 Billion —

Regional performance in the EV Charging Management Software Platform Market tracks policy design more closely than vehicle parc. Mandate-driven Europe converts regulation into software spend faster than subsidy-driven markets, while Asia-Pacific scales on sheer connector volume.


North America

Country Metric Key Driver
US 78.4% of region NEVI minimum standards and state DOT tenders
Canada 26.9% CAGR ZEV mandate and Natural Resources Canada funding
Mexico USD 0.04 Billion Cross-border logistics corridor charging


Federal obligation schedules dominate the North American picture. States must certify uptime and data-reporting compliance before reimbursement, which pushed platform procurement ahead of construction in several NEVI cohorts [4]. Utility demand charges add a second, quieter driver: in territories where commercial peak charges exceed USD 18/kW, load-management software pays for itself within a single billing year [9].

Europe

Country Metric Key Driver
Germany 22.6% of region Deutschlandnetz tender obligations
UK USD 0.16 Billion Public Charge Point Regulations 2023 reliability duties
France 25.8% CAGR ADVENIR programme and highway concession renewals
Italy 8.4% of region PNRR charging allocations
Spain 27.4% CAGR MOVES III extension
Nordic Countries 12.1% of region High EV penetration, mature roaming
Russia USD 0.02 Billion Limited domestic deployment
Rest of Europe 11.9% of region AFIR corridor coverage gaps


Regulation drives European demand. AFIR requires ad-hoc payment without subscription and per-kWh price display at new high-power points, while the UK's 2023 regulations impose a 99% reliability duty on rapid networks with financial penalties attached [6]. Compliance is a software problem, and operators have responded by replacing controllers rather than patching them.

Asia-Pacific

Country Metric Key Driver
China 48.3% of region Largest global connector base, provincial subsidies
India 33.6% CAGR PM E-DRIVE charging allocations
Japan USD 0.08 Billion CHAdeMO-to-CCS transition planning
South Korea 9.7% of region Mandatory apartment-block charging quotas
ASEAN 31.2% CAGR Two- and three-wheeler swapping networks
Rest of Asia-Pacific 6.4% of region Australian highway corridors


Scale defines the region's contribution to the EV Charging Management Software Platform Market. China alone operates several million public connectors, though domestic platform pricing sits well below Western benchmarks, muting revenue relative to volume [1]. India's trajectory looks different — greenfield networks, cloud-native from inception, with payment rails already digital.

South America

Country Metric Key Driver
Brazil 57.2% of region Electric bus procurement in São Paulo and Bogotá corridors
Argentina 27.1% CAGR Early utility pilot programmes
Rest of South America USD 0.02 Billion Chilean and Colombian fleet electrification


Transit agencies lead here rather than passenger networks. São Paulo's zero-emission bus commitments require depot software capable of guaranteeing morning state-of-charge across hundreds of vehicles on constrained feeders [18]. Currency volatility keeps contracts short and pricing local.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.8% of region EVIQ national network rollout
UAE 30.4% CAGR DEWA Green Charger expansion
South Africa USD 0.02 Billion Retail and hospitality site charging
Egypt 9.6% of region Nasr assembly and public fleet pilots
Rest of MEA 26.2% CAGR Sovereign mobility strategies


Sovereign programmes drive procurement across the region, which compresses vendor selection into a handful of large tenders. EVIQ's target of thousands of fast chargers by 2030 makes Saudi Arabia the single largest addressable opportunity, though localisation requirements favour vendors willing to establish in-kingdom data residency [19].


EV Charging Management Software Platform Market By Region, 2025-2035

EV Charging Management Software Platform Market Segmentation


By Module

Segment Metric Primary Demand Driver
Operations Management 29.1% share Mandatory monitoring and remote diagnostics
Energy Management 26.4% CAGR Demand-charge avoidance and grid constraints
Billing and Payment Management USD 4.76 Billion by 2035 Payment transparency regulation
Analytics and Reporting 29.9% CAGR Utilisation optimisation and ESG disclosure
Customer and Driver Management 11.6% share Loyalty, roaming and app experience
Others (Maintenance, Field Service) 6.1% share Uptime obligations under funding rules


Operations Management anchors the EV Charging Management Software Platform Market because nothing else can be deployed without it. Any CSMS charge point management system must first establish reliable connector state, firmware control and session authorisation; only then do energy and analytics layers become useful. That sequencing explains why the segment holds share despite the lowest growth rate in the dimension.

Analytics tells the opposite story. Attach rates sat near 30% in 2025 but rise steeply as operators discover that utilisation, not connector count, determines returns. Sites diagnosed through session-level analytics have shown throughput improvements of 12–18% within two quarters, largely by repricing idle fees and adjusting queue logic .

By Deployment Type

Segment Metric Primary Demand Driver
Cloud-Based 68.1% share Elastic scaling and rapid feature delivery
On-Premise 22.4% CAGR Utility and defence data-residency mandates


Cloud dominance in the EV Charging Management Software Platform Market reflects operator economics rather than technology preference. Networks add connectors in irregular bursts tied to funding cycles, and on-premise capacity planning cannot absorb that volatility affordably.

By Charger Type

Segment Metric Primary Demand Driver
Level 1 9.8% share Residential and light workplace charging
Level 2 49.6% share Workplace, multi-family, and destination sites
Level 3 30.0% CAGR Corridor fast charging and heavy-duty depots


Level 2 anchors installed-base counts, but Level 3 drives software complexity within the EV Charging Management Software Platform Market — thermal management, payment terminals, and grid coordination all scale with power.

By Charging Site

Segment Metric Primary Demand Driver
Public Charging Infrastructure 58.8% share Corridor mandates and retail site hosting
Private Charging Infrastructure 29.8% CAGR Fleet depots and workplace programmes


By End User

Segment Metric Primary Demand Driver
Charge Point Operators 44.3% share Network scale and roaming settlement
Fleet Operators 30.1% CAGR Depot scheduling and total-cost control
Utilities and Energy Providers 15.4% share Grid visibility and managed-charging programmes
Automotive OEMs USD 2.92 Billion by 2035 Branded charging experiences
Retail and Hospitality Site Hosts 9.4% share Dwell-time monetisation


Fleet operators represent the most valuable incremental buyer in the EV Charging Management Software Platform Market. Their willingness to pay tracks avoided cost — demand charges, driver idle time, missed routes — rather than per-connector list pricing, which supports materially higher contract values than public-network equivalents [7][12].


Competitive Benchmarking

Concentration sits in the medium band. Estimated HHI falls between 700 and 900, with the top five vendors holding roughly 30–34% of the EV Charging Management Software Platform Market. Fragmentation persists because regional roaming relationships and language-specific driver apps create defensible local positions that global scale does not automatically overcome. Consolidation has begun — hardware groups acquiring software specialists — but no vendor exceeds low double-digit share.

Company Est. Revenue Share Range Key Offerings for EV Charging Management Software Platform Market Strategic Positioning
ChargePoint Holdings ~8–11% Cloud network management, fleet depot suite, driver app Largest installed North American footprint
Driivz (Vontier) ~6–9% White-label backend, billing engine, grid integration Preferred OEM and utility licensing partner
ABB E-mobility (has·to·be) ~4–6% Charging backend, roaming hub, service management Hardware-software bundling at scale
Everon (formerly EVBox) ~4–6% Network management, load balancing, reimbursement Strong European multi-site presence
EV Connect (Schneider Electric) ~3–5% Open-protocol management, utility programme tooling Embedded in electrical infrastructure sales
AMPECO ~3–5% Modular white-label platform, API-first architecture Fast-growing challenger in EMEA and APAC
Virta ~3–5% Roaming, dynamic pricing, grid flexibility Nordic leader with flexibility monetisation
Siemens eMobility ~3–5% Depot management, microgrid orchestration Industrial and heavy-duty depot focus
Monta ~2–4% Operator portal, home and business charging High-velocity SMB and installer channel
Etrel (Landis+Gyr) ~2–4% Smart charging, metering integration Utility-grade metrology credibility
Last Mile Solutions ~2–4% Multi-tenant CPO and MSP backend Deep Benelux roaming relationships
Hubject ~2–4% Interoperability and Plug&Charge enablement Neutral roaming layer across networks


Recent News & Developments

  • ChargePoint (March 2024): Launched an eighth-generation architecture with modular power and expanded diagnostics APIs, signalling a pivot toward software-defined uptime guarantees [21]
  • Federal Highway Administration (January 2023): Finalised NEVI minimum standards mandating 97% uptime, standardised data reporting and open payment — effectively a national software specification [4]
  • Vontier / Driivz (September 2023): Expanded white-label licensing with a major European utility, validating the OEM-and-utility backend model described in Section 6.5 [22]
  • European Parliament (April 2023): Adopted AFIR with binding ad-hoc payment and price-transparency obligations from 2024, triggering the retrofit cycle visible in the 2027 forecast [6]
  • Schneider Electric / EV Connect (2023–2024): Integrated charging management into broader microgrid and energy-management portfolios, blurring the line between charging and building energy software [23]
  • Open Charge Alliance (June 2024): Released expanded OCPP 2.0.1 certification tooling, cutting conformance testing timelines for hardware vendors [5]
  • AMPECO (February 2025): Raised growth capital to expand across Asia-Pacific and Latin America, targeting greenfield operators without legacy controller estates [24]
  • UK Office for Zero Emission Vehicles (November 2024): Began enforcement reporting under the Public Charge Point Regulations, publishing operator-level reliability data for the first time [25]


EV Charging Management Software Platform Market Report Scope

Attribute Detail
Market Scope Software platforms for managing, monetising and optimising EV charging assets, including operations, energy, billing, analytics and driver management modules
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 26.0% (2026–2035)
Market Size Checkpoints USD 2.58 Billion (2025); USD 3.25 Billion (2026); USD 8.78 Billion (2030); USD 26.04 Billion (2035)
Fastest Growing Segments Analytics and Reporting (module); Level 3 (charger type); Fleet Operators (end user); Asia-Pacific (region)
Companies Profiled ChargePoint, Driivz, ABB E-mobility, Everon, EV Connect, AMPECO, Virta, Siemens eMobility, Monta, Etrel, Last Mile Solutions, Hubject
Valuation Currency USD Billion

FAQs

How should procurement teams evaluate vendors in the EV Charging Management Software Platform Market?
Weight open-protocol certification, roaming coverage, and contractual uptime remedies above feature counts. Request third-party OCPP 2.0.1 test-lab certificates and reference sites of comparable connector scale before shortlisting. [Ref 5]
What integration challenges most often derail deployments?
Legacy charger firmware implementing protocols only partially, combined with utility meter feeds arriving in non-standard formats. Budget six to nine months for hardware conformance testing before commercial launch. [Ref 15]
Is white-label licensing viable in the EV Charging Management Software Platform Market?
Yes, above roughly 5,000 connectors, where brand control and data ownership justify integration overhead. Below that threshold, multi-tenant subscription models deliver better unit economics. [Ref 12]
How do lenders and insurers assess platform risk?
Project finance now commonly requires escrowed source code and documented data-portability clauses. Lenders treat vendor lock-in as a refinancing risk on assets carrying ten-year depreciation schedules. [Ref 17]
Which emerging use cases will reshape the EV Charging Management Software Platform Market after 2030?
Megawatt charging for heavy trucks and battery-buffered sites demand millisecond-level dispatch. Depot platforms will also arbitrage stationary storage against wholesale prices. [Ref 8]
Which compliance credentials matter most in tenders?
ISO 27001, SOC 2 Type II, and OCPP Security Profile 3 have become standard European tender requirements. PCI DSS scope reduction matters wherever card readers sit at the charger. [Ref 13]
How do pricing models differ across the EV Charging Management Software Platform Market?
Per-connector monthly fees dominate public networks, while depot operators increasingly negotiate per-vehicle or per-kWh terms. Revenue-share structures appear mainly where the vendor also supplies hardware financing. [Ref 12]      
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, technology journals, and authoritative energy & transportation organizations. Key sources included the US Department of Energy (DOE) Alternative Fuels Data Center, International Energy Agency (IEA) Global EV Outlook, European Alternative Fuels Observatory (EAFO), Alternative Fuels Infrastructure Directive (AFID) Database, International Electrotechnical Commission (IEC) Standards, Institute of Electrical and Electronics Engineers (IEEE) Smart Grid Publications, National Renewable Energy Laboratory (NREL), California Energy Commission (CEC), European Commission Transport Research and Innovation Monitoring and Information System (TRIMIS), China Association of Automobile Manufacturers (CAAM), US Bureau of Transportation Statistics, International Council on Clean Transportation (ICCT), Office of Energy Efficiency & Renewable Energy (EERE), and national energy ministry reports from key markets. These sources were used to collect EV adoption statistics, charging infrastructure deployment data, regulatory compliance frameworks, grid integration studies, and technology landscape analysis for Level 1 & 2 charging, Level 3 fast charging, operations management systems, energy management modules, and billing/payment platforms.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Product Development, heads of Charging Network Operations, and commercial directors from EV charging software suppliers, Charge Point Operators (CPOs), and e-Mobility Service suppliers (eMSPs) were examples of supply-side sources. Fleet managers, sustainability officers, utility grid integration experts, and procurement leads from automakers, public transportation authority, retail chains, commercial real estate developers, and municipal transportation agencies were examples of demand-side suppliers. Market segmentation, software development roadmaps, network interoperability standards, dynamic pricing strategies, grid load management methods, and V2G integration timescales were all confirmed by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (30%), Others (30%)

By Region: North America (32%), Europe (28%), Asia-Pacific (35%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and charging point deployment analysis. The methodology included:

Identification of 55+ key software platform providers across North America, Europe, Asia-Pacific, and Latin America

Module mapping across Operations Management, Energy Management, Billing Management, and other functional categories

Analysis of reported and modeled annual revenues specific to EV charging management software portfolios

Coverage of platform providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (charging point volume × software licensing fees by region) and top-down (provider revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















