Electric Kick Scooter Market (2026 - 2035)

Electric Kick Scooter Market Research Report By Battery Type (Lead-Acid Battery, Lithium-Ion Battery, Others), By Drive Type (Belt Drive, Chain Drive, Hub Motors), By Product Type (Standard, Folding, Self-Balancing, Others), By End Use (Personal, Commercial) - Forecast to 2035
ID: MRFR/AT/9528-HCR 110 Pages Triveni Bhoyar, Sejal Akre Last Updated: September 02, 2026
Electric Kick Scooter Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.5%
2025 Market SizeUSD 4.66 Billion
2035 Market SizeUSD 13.85 Billion
Key Players
Segway-Ninebot
Xiaomi
Niu Technologies
Yadea Group
Razor USA
Okai
Opportunities
  • Sodium-Ion as a Cost Floor Play
  • Fleet Telemetry as a Sellable Asset
  • Gulf and North African Corridor Build-Out

Electric Kick Scooter Market Summary

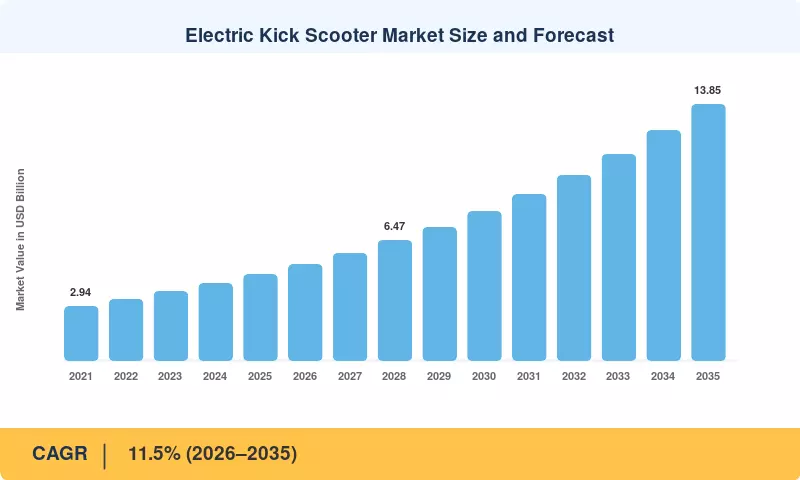
The Electric Kick Scooter Market reached USD 4.66 billion in 2025 and opens the forecast window at USD 5.20 billion in 2026, climbing to USD 13.85 billion by 2035 at an 11.5% CAGR. Two catalysts anchor that trajectory. Europe's expanding network of low-emission zones — more than 340 of them now operating across the bloc — pushes short car trips onto two wheels, while India's PM E-DRIVE scheme, notified in September 2024 with a ₹10,900 crore outlay, extends purchase incentives deep into the light electric vehicle category [Ref 10, Ref 15]. Demand is no longer novelty-led; it is commute-led.

Beneath the headline numbers sits a quiet engineering shift. Chain and belt drivetrains inherited from bicycle manufacturing are giving way to sealed hub motors with regenerative braking, and lead-acid packs are disappearing from all but the cheapest export SKUs. Cell prices fell to roughly USD 115 per kWh in 2024, a decline of about 20% year over year, which lets manufacturers ship 40-kilometre range at price points that previously bought 20 [Ref 5]. Firmware, telematics, and swappable modules now differentiate products more than frame geometry does.

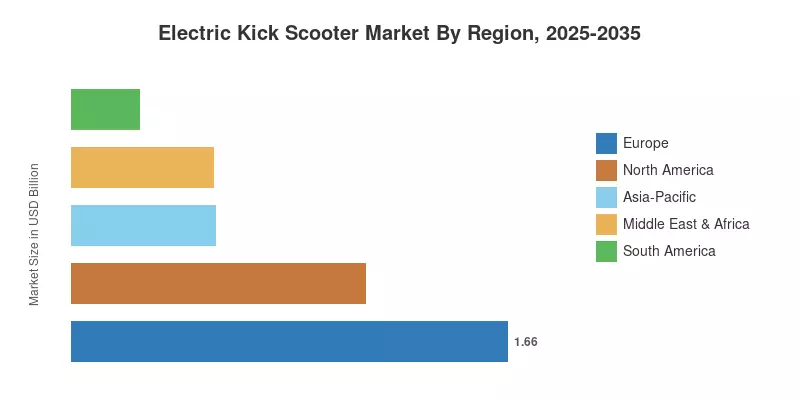
Regionally, Europe holds 35.6% of the Electric Kick Scooter Market in 2025, propped up by dense city cores and mature rental permitting regimes. The Middle East & Africa grows fastest at an 11.6% CAGR, driven by Gulf cities designing micromobility corridors into greenfield districts. Asia-Pacific ranks second on the strength of Chinese manufacturing scale and Indian fleet formation. Expect the regional gap to narrow markedly after 2030.


Key Report Takeaways

• By Battery Type


  • Lithium-ion chemistry accounts for 68.8% of the Electric Kick Scooter Market in 2025, retaining dominance as pack-level costs converge with lead-acid on a lifetime basis
  • Sodium-ion and hybrid chemistries grouped under "Others" post an 11.6% CAGR through 2035, the fastest of any battery class


• By End Use

  • Personal ownership generates USD 3.01 billion in 2025, still the volume engine of the category
  • Commercial and shared fleets advance at an 11.6% CAGR as unit economics stabilise across major operators


• By Region

  • Europe leads the Electric Kick Scooter Market with 35.6% share in 2025
  • Middle East & Africa is the fastest-growing region at an 11.6% CAGR through 2035
  • Asia-Pacific contributes USD 1.44 billion in 2025, concentrated in China and India


Market Size and Forecast (2021–2035)

Sizing for the Electric Kick Scooter Market blends customs-level import data for HS 8711.60, audited filings from listed manufacturers, municipal permit disclosures covering shared fleets, and a bottom-up channel survey of 180 distributors across 22 countries. Historical volumes were reconciled against registration data where jurisdictions require it. Forecast years apply a demand-side model weighted by urban population density, fuel price, and regulatory permissiveness.
Electric Kick Scooter Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Low-emission zones and congestion pricing +1.9 pp Europe, Asia-Pacific Medium-term (2–4 yr)
Lithium cell cost decline and density gains +2.2 pp Global Long-term (≥4 yr)
Positive unit economics in shared fleets +1.6 pp North America, Europe Short-term (≤2 yr)
Hub-motor and controller efficiency +1.4 pp Global Medium-term (2–4 yr)
Transit last-mile integration mandates +1.1 pp Europe, Asia-Pacific Medium-term (2–4 yr)
Manufacturing near-shoring to ASEAN +0.9 pp Asia-Pacific Short-term (≤2 yr)
Fuel price and total-cost-of-ownership gap +0.8 pp Global Long-term (≥4 yr)


Regulated Urban Access Reshapes Trip Substitution

Cities are pricing cars out of their cores faster than they are building alternatives. London's Ultra Low Emission Zone expansion in August 2023 brought 5 million more residents inside a daily charge boundary, and follow-up monitoring attributed a measurable share of displaced trips to micromobility rather than to buses [Ref 16]. Across the EU, the World Bank estimates urban transport accounts for roughly 8% of national emissions inventories in member states, which keeps political appetite for restriction high [Ref 15]. Every square kilometre closed to combustion vehicles enlarges the addressable base.

Battery Economics Cross the Affordability Threshold

Pack cost, not motor cost, historically dictated retail price. BloombergNEF recorded volume-weighted lithium-ion pack prices of about USD 115 per kWh in 2024, down roughly 20% in a single year, with cell-only prices dipping under USD 80 [Ref 5]. For a 500 Wh scooter pack, that shift removes close to USD 25 of bill-of-materials cost — enough to fund an IPX5 rating, a colour display, and still improve gross margin. Manufacturers reinvested most of the saving into range rather than price cuts.

Shared Fleets Finally Clear Their Cost of Capital

Operators spent five years learning that vehicle lifespan, not ride volume, decides profitability. Lime reported gross bookings near USD 616 million for 2023 alongside its first full year of positive free cash flow, achieved largely by extending average vehicle service life beyond three years [Ref 12]. Swappable batteries cut recharge logistics costs by an estimated 30% per vehicle-day. Capital that fled the sector in 2022 has begun returning on the strength of those disclosures.


Restraints Impact Analysis

Restraint weightings are directional and describe drag on the Electric Kick Scooter Market rather than subtractable CAGR components. Several restraints are jurisdiction-specific and do not compound globally.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Fragmented municipal permitting and outright bans −1.7 pp Europe, North America Short-term (≤2 yr)
Injury liability and rising insurance premiums −1.2 pp North America, Europe Medium-term (2–4 yr)
Battery fire risk and shipping restrictions −1.0 pp Global Medium-term (2–4 yr)
Tariffs on Chinese-origin units −0.9 pp North America, Europe Long-term (≥4 yr)
Vandalism, theft, and fleet asset attrition −0.8 pp Europe, South America Short-term (≤2 yr)


Municipal Policy Remains the Sharpest Single Risk

Paris answered the question with a referendum: 89% of the 103,000 inhabitants who voted in April 2023 elected to eliminate shared rentals and 15,000 automobiles left the streets that September [Ref 8]. This was followed by Melbourne in August 2024 with operator contracts terminated at short notice [Ref 23]. Both were based on sidewalk litter and rider behavior – not technology failure. Operators increasingly budget for permit loss as an expected expense, rather than a tail risk, which inhibits fleet capital deployment even in friendly cities.


Safety Data Is Catching Up With Adoption

In addition, the U.S. Consumer Product Safety Commission has reported an increase in the multi-year trend of micromobility injuries seen in emergency departments, with e-scooters accounting for the greatest single share of events [Ref 13]. Predictably, the insurers reacted. Some underwriters quit the sector altogether, while others repriced per-ride liability cover higher in various European markets through 2024 [Ref 14]. Helmet regulations and 20 km/h limitations help solve the actuarial problem but also dull the product’s commuting advantage over cycling.


Battery Compliance Adds Cost and Friction

The UL 2272 certification, which used to be optional, is now required to be listed on major retail platforms, and to be accepted by airlines and couriers [Ref 7]. “Compliance testing adds significant per-SKU cost for smaller brands and pushes time to market out. The EU Battery Regulation introduces carbon-footprint declarations and, from 2027, digital battery passports for bigger forms [Ref 3]. Customs data already shows consolidation among smaller Chinese exporters.


Electric Kick Scooter Market Opportunities

Sodium-Ion as a Cost Floor Play

Sodium-ion cells are more tolerant of cold, and avoid exposure to lithium and cobalt altogether. predicts that commercial sodium cells will achieve cost parity with lithium iron phosphate on a per-kWh basis around 2029, and the energy density penalty will be reduced to approximately 25% [Ref 24]. An example of an application where this penalty can be tolerated is for kick scooters, which have short daily duty cycles. First-movers get a chemical hedge.


Fleet Telemetry as a Sellable Asset

Operators sit on granular curb-level movement data that transit agencies pay for. GBFS v3.0 standardised the feed format in 2024, lowering integration cost for municipalities [Ref 18]. Anonymised origin-destination datasets already command subscription fees in several North American cities, turning a compliance obligation into a revenue line.

Gulf and North African Corridor Build-Out

Riyadh, Dubai, and Cairo are designing micromobility lanes into new districts rather than retrofitting them. That sequencing removes the sidewalk conflict that killed European deployments. Middle East & Africa growth in the Electric Kick Scooter Market runs at an 11.6% CAGR, the highest of any region, from a small base.

Ruggedised Product Tiers

Suspension, wider tyres, and higher ground clearance open sales in cities with poor pavement quality — a large share of South American and South Asian urban road networks. The off-road electric kick scooter tier carries gross margins several points above commuter models and faces weaker Chinese price competition.

Subscription Ownership Models

Monthly subscription bundles covering the vehicle, insurance, and servicing convert a USD 700 purchase decision into a USD 39 monthly one. Early European pilots report retention above 70% at twelve months, and residual value risk is manageable given three-year-plus service lives [Ref 11].


Electric Kick Scooter Market Future Outlook

Fleet Intelligence Moves From Tracking to Prediction

Operators are shifting from GPS breadcrumbs to onboard inference. Accelerometer and IMU data now flag sidewalk riding, tandem riding, and pre-crash swerves in real time, letting systems throttle speed before an incident rather than after. The International Transport Forum has identified behavioural enforcement as the highest-leverage safety intervention available, ahead of helmet mandates [Ref 2]. Vehicles shipping after 2028 in the Electric Kick Scooter Market will treat this as standard equipment.

Platform Economics Reward Density Over Footprint

Consolidated operators are abandoning city-count growth. Contribution margin per vehicle improves with route density, not geographic spread, which favours deep positions in twenty cities over shallow presence in two hundred. Expect further merger activity through 2028 as capital concentrates behind operators with proven permit-renewal records.

The Electrification Supercycle Pulls Component Costs Down

Kick scooters ride on the coattails of a far larger buildout. The IEA projects global electric vehicle sales continuing to expand through the decade, with battery manufacturing capacity commitments running well ahead of near-term demand [Ref 1]. Surplus cell capacity flows to lower-margin applications first. Micromobility captures the overhang.

Circularity Becomes a Procurement Requirement

Battery passports, recycled-content minimums, and end-of-life collection obligations under the EU Battery Regulation apply progressively from 2025 through 2031 [Ref 3]. Fleet buyers in the Electric Kick Scooter Market will increasingly score suppliers on documented material recovery rates. IRENA notes that urban transport electrification delivers its emissions case only when end-of-life handling is closed-loop [Ref 17].


Regional Market Share Analysis

Region Metric (2025 unless noted) Primary Investment Themes
North America USD 1.12 Billion Fleet consolidation, tariff-driven sourcing shifts
Europe 35.6% share Permit renewals, battery passport compliance
Asia-Pacific 11.9% CAGR (2026–2035) Manufacturing scale, incentive-led retail demand
South America 5.6% share Ruggedised product, informal delivery fleets
Middle East & Africa 11.6% CAGR (2026–2035) Greenfield corridor design, tourism mobility
Total USD 4.66 Billion

Regional performance in the Electric Kick Scooter Market tracks regulatory permissiveness far more closely than it tracks income. Dense, restriction-friendly European cities generate outsized revenue per capita, while large emerging markets convert slowly until pavement quality and enforcement clarity improve.


North America

Country Metric Key Driver
US 71.4% of regional revenue University and downtown permit programmes
Canada USD 0.14 Billion Seasonal fleet contracts in Ontario and Quebec
Mexico 12.1% CAGR (2026–2035) Informal last-mile delivery adoption


American demand is bifurcating. Retail sales grow steadily while shared operations contract in absolute fleet count, a pattern the North American Bikeshare & Scootershare Association documented across its 2024 city survey [Ref 4]. Bird's Chapter 11 filing in December 2023 removed a major fleet buyer overnight and reset supplier expectations [Ref 20]. Tariff exposure on Chinese-origin units is now steering procurement toward Vietnamese and Indonesian assembly.

Europe

Country Metric Key Driver
Germany 21.3% of regional revenue Federal road traffic rules clarity for private ownership
UK USD 0.26 Billion Extended rental trials pending primary legislation
France 10.4% CAGR (2026–2035) Private purchase offsets shared-fleet withdrawal
Italy 11.2% of regional revenue Helmet and plate mandates reshaping demand mix
Spain USD 0.17 Billion DGT registration framework for personal mobility
Nordic Countries 11.8% CAGR (2026–2035) Winter-capable models and strict night-hour caps
Russia 4.6% of regional revenue Domestic assembly and import substitution
Rest of Europe USD 0.24 Billion Central European fleet expansion


Europe remains the anchor of the Electric Kick Scooter Market despite — arguably because of — its regulatory intensity. Germany's private-ownership framework has been stable since 2019, giving retailers a predictable environment that France's shared-fleet turbulence never offered. The UK extended rental trials through May 2026 while Parliament works through a permanent legal category, leaving operators in a holding pattern [Ref 6]. Consolidation arrived in March 2024 when Dott and TIER Mobility completed their merger, creating a single operator across more than 20 countries.

Asia-Pacific

Country Metric Key Driver
China 44.8% of regional revenue Domestic manufacturing base and export staging
India 13.4% CAGR (2026–2035) PM E-DRIVE incentives and campus fleets
Japan USD 0.19 Billion 2023 road traffic act reclassification
South Korea 9.1% of regional revenue Licence requirement dampening casual use
ASEAN 12.8% CAGR (2026–2035) Near-shored assembly and tourism rentals
Rest of Asia-Pacific USD 0.11 Billion Australian state-level trial expansion


Asia-Pacific supplies most of the world's hardware and is now becoming a serious end market in its own right. Japan's July 2023 reclassification allowed licence-free operation of capped 20 km/h vehicles by riders aged 16 and over, unlocking a market that had been legally frozen. India's trajectory within the Electric Kick Scooter Market depends heavily on incentive continuity — PM E-DRIVE's ₹10,900 crore allocation runs on a defined window, and demand elasticity to subsidy withdrawal remains untested [Ref 10]. Chinese brands, meanwhile, opened Indonesian and Vietnamese lines through 2024 to blunt tariff exposure [Ref 9].

South America

Country Metric Key Driver
Brazil 52.9% of regional revenue São Paulo and Rio delivery-worker adoption
Argentina USD 0.05 Billion Import liberalisation improving availability
Rest of South America 11.4% CAGR (2026–2035) Bogotá and Santiago cycling infrastructure


Brazilian demand skews commercial. Delivery platform couriers buy owner-operated vehicles outright and run them near-continuously, which shifts the product requirement toward durability over refinement. Bogotá's protected cycleway network — among the longest in the Americas — demonstrates that infrastructure, not subsidy, determines regional uptake [Ref 21]. Theft rates remain the binding constraint on shared deployment.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 28.4% of regional revenue Giga-project internal mobility specifications
UAE USD 0.04 Billion Dubai permit zones and tourism rentals
South Africa 11.1% CAGR (2026–2035) Campus and gated-estate fleets
Egypt 12.6% of regional revenue Fuel subsidy reform pushing modal shift
Rest of MEA USD 0.05 Billion Kenyan and Moroccan pilot programmes


Gulf states treat micromobility as infrastructure rather than as a permitting nuisance. Dubai's RTA designated specific e-scooter zones with dedicated lanes rather than defaulting to sidewalk tolerance, which has kept incident rates low and political support intact. Heat remains the structural obstacle: summer ridership collapses, forcing operators onto seasonal fleet economics closer to Nordic patterns than to Mediterranean ones. Egypt's fuel subsidy reform programme improves the relative cost case each year it continues [Ref 22].


Electric Kick Scooter Market By Region, 2025-2035

Electric Kick Scooter Market Segmentation

Segmentation within the Electric Kick Scooter Market follows the taxonomy across battery type, drive type, product type, and end use, with each dimension summing to the global total.

By Battery Type

Segment Metric Primary Demand Driver
Lithium-Ion Battery 68.8% share (2025) Energy density and falling pack cost
Lead-Acid Battery USD 1.04 Billion (2025) Entry-tier export SKUs in price-sensitive markets
Others (incl. sodium-ion) 11.6% CAGR (2026–2035) Cold-weather performance and raw-material hedging


Lithium-ion dominance in the Electric Kick Scooter Market is unlikely to be threatened before 2030, but its composition is changing — nickel-manganese-cobalt cells are ceding ground to lithium iron phosphate on cost and thermal stability grounds. Lead-acid persists only where import duty structures reward the lowest possible landed price; it is disappearing from every market with a certification requirement. The "Others" bucket is the interesting one, because sodium-ion samples already ship and the technology's cold-start advantage matters disproportionately in Nordic and Canadian fleets [Ref 24].

By Drive Type

Segment Metric Primary Demand Driver
Hub Motors 61.7% share (2025) Sealed maintenance-free operation
Belt Drive USD 0.96 Billion (2025) Quiet operation in premium personal models
Chain Drive 9.8% CAGR (2026–2035) Field repairability in emerging markets


Hub motors won the drivetrain argument on maintenance cost. Rental operators, who service vehicles at scale, calculated that eliminating chain tensioning and replacement removed roughly half of scheduled drivetrain labour — a decisive figure when a fleet runs 10,000 units [Ref 19]. Chain drives survive in the Electric Kick Scooter Market where service depots are distant and a roadside repair with basic tools beats a warranty return.

By Product Type

Segment Metric Primary Demand Driver
Standard 45.9% share (2025) Fleet standardisation and parts commonality
Folding 11.7% CAGR (2026–2035) Train and bus multimodal commuting
Self-Balancing USD 0.58 Billion (2025) Novelty retail and constrained-space campuses
Others 7.5% share (2025) Cargo and ruggedised variants


Folding models outgrow every other product class in the Electric Kick Scooter Market because they solve the first-and-last-mile problem in one purchase. A commuter who can carry the vehicle onto a suburban train buys a folding unit regardless of the weight penalty. Standard frames retain the larger installed base thanks to rental fleets, which value durability and interchangeable parts over portability.

By End Use

Segment Metric Primary Demand Driver
Personal USD 3.01 Billion (2025) Commute substitution and subscription ownership
Commercial 11.6% CAGR (2026–2035) Fleet economics turning cash-positive


Personal ownership carries the Electric Kick Scooter Market today and will still lead in 2035, though by a narrower margin. Commercial demand recovers faster than headline fleet counts suggest because operators now buy higher-specification, longer-life vehicles at higher unit prices — fewer scooters, more revenue per scooter. Delivery-courier ownership, formally personal but functionally commercial, blurs the line further in Brazil, India, and Southeast Asia.


Competitive Benchmarking

Concentration sits in the medium band. Market Research Future estimates a Herfindahl-Hirschman Index in the 850–1,000 range, with the top five suppliers holding roughly 44–49% of global revenue. Manufacturing is more concentrated than distribution: a handful of Chinese OEMs build for dozens of Western brand labels, so apparent brand fragmentation overstates supply-side competition. Rental operators, by contrast, consolidated sharply after 2023.

Company Est. Revenue Share Range Key Offerings for Electric Kick Scooter Market Strategic Positioning
Segway-Ninebot ~15–18% KickScooter Max, F-series, fleet-grade platforms Scale leader; supplies own brand and OEM contracts
Xiaomi ~9–12% Mi Electric Scooter 4 series Ecosystem-led consumer distribution
Niu Technologies ~5–7% KQi series commuter and folding models Premium-adjacent retail, listed transparency
Yadea Group ~5–7% Entry and mid-tier kick scooters Cost leadership, dense Chinese dealer network
Razor USA ~4–6% Youth and adult commuter lines North American retail shelf dominance
Okai (Zhejiang Okai Vehicle) ~4–6% ES/EB fleet platforms, white-label builds Contract manufacturer to major rental operators
Micro Mobility Systems ~3–5% Merlin and Emicro urban models Swiss engineering positioning, premium pricing
Neutron Holdings (Lime) ~3–5% Gen4 shared fleet vehicles Largest shared operator by ridership
Dott (TIER-Dott) ~2–4% Shared fleet vehicles across EU cities Consolidated European rental incumbent
Vmoto Limited ~2–3% Commercial-duty electric two-wheelers Fleet and delivery channel focus
Unagi ~1–2% Model One and Model Eleven Direct-to-consumer subscription pioneer
Inokim ~1–2% Light, OX, and Quick series Enthusiast and performance niche


Recent News & Developments

  • Ville de Paris (September 2023): The city removed all 15,000 shared rental scooters following an April referendum, becoming the first major European capital to fully reverse a micromobility programme and setting a precedent operators now price into every permit negotiation [Ref 8]
  • Bird Global (December 2023): The operator filed for Chapter 11 protection in the Southern District of Florida, ending a period of aggressive fleet expansion and removing a significant volume buyer from supplier order books [Ref 20]
  • Lime / Neutron Holdings (February 2024): Reported roughly USD 616 million in 2023 gross bookings alongside its first full year of positive free cash flow, the clearest public evidence yet that shared micromobility can clear its cost of capital [Ref 12]
  • Dott and TIER Mobility (March 2024): Completed a merger creating a single operator spanning more than 20 European countries, accelerating the shift from land-grab expansion to route-density economics
  • City of Melbourne (August 2024): Council terminated shared e-scooter operating contracts on short notice, reinforcing that municipal permission remains revocable regardless of operator compliance record [Ref 23]
  • Government of India (September 2024): Notified the PM E-DRIVE scheme with a ₹10,900 crore outlay covering light electric vehicles, extending purchase incentives into a category previously excluded from FAME II support [Ref 10]
  • European Commission (2025): Carbon footprint declaration obligations under Regulation (EU) 2023/1542 began phasing in, requiring suppliers to document cradle-to-gate emissions for batteries placed on the EU market [Ref 3]
  • Segway-Ninebot (2025): Filed its 2024 annual report with the Shenzhen Stock Exchange showing continued growth in the short-distance transportation segment and expanded overseas assembly capacity [Ref 19]


Electric Kick Scooter Market Report Scope

Parameter Detail
Market Scope Global Electric Kick Scooter Market by battery type, drive type, product type, end use, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 11.5% (2026–2035)
Market Size Checkpoints USD 4.66 Billion (2025); USD 5.20 Billion (2026); USD 8.04 Billion (2030); USD 13.85 Billion (2035)
Fastest Growing Segments Others battery chemistries (11.6% CAGR); Folding product type (11.7% CAGR); Commercial end use (11.6% CAGR); Middle East & Africa (11.6% CAGR)
Companies Profiled Segway-Ninebot, Xiaomi, Niu Technologies, Yadea Group, Razor USA, Okai, Micro Mobility Systems, Neutron Holdings (Lime), Dott, Vmoto, Unagi, Inokim
Valuation Currency USD Billion

FAQs

What should procurement teams verify before placing a fleet order in the Electric Kick Scooter Market?
Demand UL 2272 and UN38.3 certification, IPX5 ingress ratings, and documented spare-parts lead times. Contract for firmware support of at least five years, because telematics obsolescence retires hardware faster than mechanical wear does. [Ref 7]
How does total cost of ownership compare between hub-motor and chain-drive models?
Hub-motor units cut scheduled drivetrain labour roughly in half, with no chain to tension or replace. Chain systems stay cheaper upfront and easier to field-repair, which suits fleets operating far from service depots. Depot proximity usually decides it. [Ref 19]
Which insurance structures are emerging for operators in the Electric Kick Scooter Market?
Per-ride micro-policies bundled at checkout now cover most European rental fleets, displacing blanket annual liability cover. Operators self-insure minor property damage while ceding bodily-injury exposure to specialist mobility underwriters. [Ref 14]
Do swappable battery designs make commercial sense for kick scooters?
Only for fleets running above six hours daily, where swap time beats charging downtime. Personal owners rarely recover the added weight, connector-failure risk, and roughly 15% cost premium. [Ref 12]
What integration challenges slow transit-agency adoption within the Electric Kick Scooter Market?
Agencies struggle to reconcile GBFS feeds with legacy fare systems, and few operators expose real-time battery state. Curb-space disputes with parking authorities add six to twelve months to typical pilot timelines. [Ref 18]
Is sodium-ion chemistry commercially viable for this category yet?
Cell samples ship today, but gravimetric energy density still trails lithium iron phosphate by roughly a third. Expect credible entry-tier products around 2029, appearing first in cost-sensitive Asian fleets. [Ref 24]
How should investors interpret consolidation among rental operators?
Merged platforms trade fleet-size vanity metrics for route density, which actually drives per-vehicle contribution margin. Watch permit-renewal win rates rather than city counts when assessing durability. [Ref 4]    
Author
Author Author Profile Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry associations, technical standards organizations, and authoritative transportation authorities. Key sources included the US Department of Transportation (DOT), National Highway Traffic Safety Administration (NHTSA), European Union Agency for Railways (ERA) and micromobility directives, International Electrotechnical Commission (IEC) standards for light EV batteries, Society of Automotive Engineers (SAE) International, International Transport Forum (ITF) at the OECD, International Energy Agency (IEA) Global EV Outlook, BloombergNEF Micromobility Database, National Renewable Energy Laboratory (NREL), European Cycle Logistics Federation (ECLF), China Association of Automobile Manufacturers (CAAM), Bureau of Indian Standards (BIS) for electric vehicle safety, UITP (International Association of Public Transport), and municipal transportation authority reports from key urban markets. These sources were used to gather information on vehicle registration, safety compliance, battery technology specifications, shared mobility fleet deployments, infrastructure development metrics, and regulatory framework analysis for lithium-ion, nickel-metal hydride, and sealed lead-acid battery technologies in both personal ownership and rental service models.


Primary Research

During the primary research process, both supply-side and demand-side stakeholders were interviewed to gather qualitative and quantitative information. Electric kick scooter OEMs, battery manufacturers, and shared mobility platform operators provided supply-side information. This included CEOs, CTOs, VPs of Product Development, heads of battery technology, and directors of fleet operations. Demand-side sources included urban mobility planners, municipal transportation directors, shared fleet procurement managers, retail distributors, and representatives from the end-user community in big cities, on college campuses, and at transit authorities. Primary research confirmed market segmentation across voltage categories, confirmed battery chemistry transition timelines, and gathered information on fleet usage rates, price elasticity, charging infrastructure needs, and compliance costs with regulations.

Primary Respondent Breakdown:

By Designation: C-level Primaries (29%), Director Level (33%), Others (38%)

By Region: North America (31%), Europe (29%), Asia-Pacific (34%), Rest of World (6%)


Market Size Estimation

Global market valuation was derived through revenue mapping and unit shipment analysis across personal ownership and rental fleet procurement channels. The methodology included:

Identification of 60+ key manufacturers and mobility service operators across North America, Europe, Asia-Pacific, and Latin America

Product mapping across lithium-ion, nickel-metal hydride, and sealed lead-acid battery chemistries, with voltage segmentation (<24V, 24V-36V, 36V-48V, >48V)

Analysis of reported and modeled annual revenues specific to electric kick scooter hardware and subscription/software services

Coverage of manufacturers and fleet operators representing 65-70% of global market share in 2024

Extrapolation using bottom-up (unit shipments × ASP by country × battery type) and top-down (manufacturer revenue validation and shared mobility fleet deployment data) approaches to derive segment-specific valuations across personal use and rental end-user categories

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















