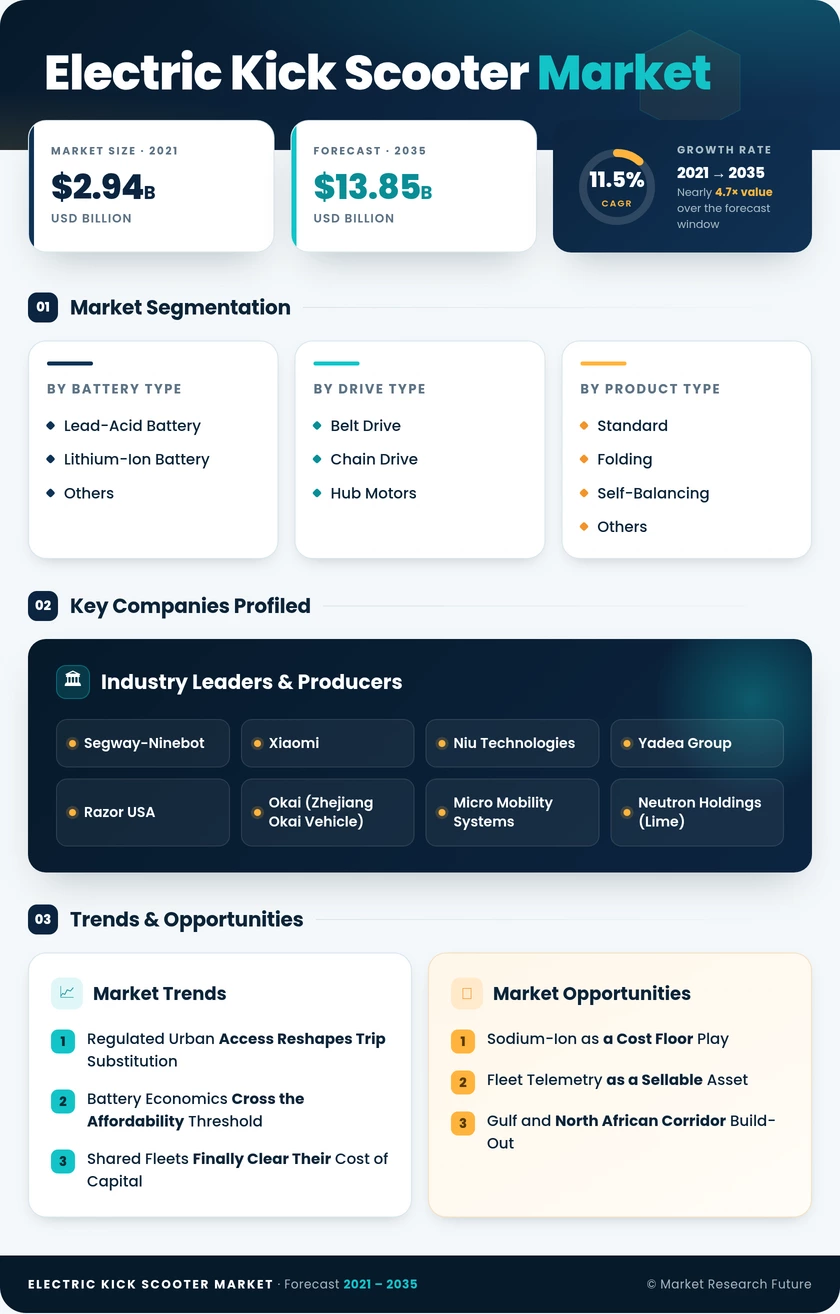
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Battery Type | Lead-Acid Battery, Lithium-Ion Battery, Others | Lithium-Ion Battery | Others |
| By Drive Type | Belt Drive, Chain Drive, Hub Motors | Hub Motors | Hub Motors |
| By Product Type | Standard, Folding, Self-Balancing, Others | Standard | Folding |
| By End Use | Personal, Commercial | Personal | Commercial |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Europe | Middle East & Africa |
Market Segmentation Overview
By Battery Type
| Sub-Segment | Key Trend |
| Lead-Acid Battery | Retreating to entry-tier export SKUs where duty structures reward lowest landed cost |
| Lithium-Ion Battery | Internal shift from nickel-manganese-cobalt toward lithium iron phosphate on cost and thermal stability |
| Others | Sodium-ion sampling for cold-climate fleets; raw-material hedging against lithium price volatility |
Chemistry choice is becoming a supply-chain decision rather than an engineering one. Buyers increasingly weigh cell origin, recycled-content documentation, and carbon footprint declarations alongside energy density, a direct consequence of EU battery rules phasing in through 2031.
By Drive Type
| Sub-Segment | Key Trend |
| Belt Drive | Retained in premium personal models for quiet, low-vibration operation |
| Chain Drive | Persisting where field repairability outweighs maintenance frequency |
| Hub Motors | Standard across shared fleets; regenerative braking now common at mid-tier price points |
Drivetrain selection now maps almost perfectly onto service-network density. Where depots are close and labour is expensive, sealed hub motors win; where riders self-service, exposed chains survive.
By Product Type
| Sub-Segment | Key Trend |
| Standard | Fleet standardisation and parts commonality keep the installed base large |
| Folding | Multimodal commuting drives the fastest growth of any product class |
| Self-Balancing | Confined to novelty retail and constrained-space campus deployments |
| Others | Cargo variants and ruggedised builds for poor-pavement urban networks |
Portability has overtaken raw performance as the primary retail purchase driver. Weight reduction of even two kilograms materially changes whether a commuter will carry a vehicle up a station staircase, and manufacturers are optimising frames accordingly.
By End Use
| Sub-Segment | Key Trend |
| Personal | Subscription bundles converting outright purchase into monthly commitment |
| Commercial | Fewer but higher-specification vehicles as operators optimise for service life |
End-use boundaries are blurring in emerging markets, where delivery couriers purchase nominally personal vehicles and run them on near-continuous commercial duty cycles. Warranty design has not yet caught up with that reality.
By Geography
| Sub-Segment | Key Trend |
| North America | Retail growth alongside shared fleet contraction; tariff-driven sourcing shifts |
| Europe | Permit renewal risk balanced against the deepest installed base and strictest compliance regime |
| Asia-Pacific | Manufacturing scale converting into genuine domestic demand, led by India and Japan |
| South America | Commercial courier adoption outpacing recreational use |
| Middle East & Africa | Greenfield corridor design avoiding the sidewalk conflicts that constrained Europe |
Geographic performance correlates with regulatory clarity more than with income level. Markets that defined a legal vehicle class early — Germany, Japan, the UAE — show smoother adoption curves than wealthier markets still legislating by pilot programme.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA