Defense Electronics Market (2026 - 2035)

Defense Electronics Market Size, Share, Industry Trend & Analysis Research Report By System Type (Radar and Multi-Function Sensors, Electronic Warfare Systems, C4ISR and Tactical Communications, Optronics and EO/IR Sensors, Others), By Platform (Airborne, Land, Naval, Space), By Component (Hardware, Software), By Fit (Line-Fit, Retrofit), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/AD/10857-HCR 128 Pages Abbas Raut, Swapnil Palwe Last Updated: October 01, 2026
Defense Electronics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.0%
2025 Market SizeUSD 189.9 Billion
2035 Market SizeUSD 340.1 Billion
Key Players
RTX Corporation
Lockheed Martin Corporation
Northrop Grumman Corporation
BAE Systems plc
L3Harris Technologies, Inc.
Thales Group
Opportunities
  • Modular Retrofit Kits for Legacy Fleets
  • Localization Partnerships in Emerging Markets
  • Software Licensing and Mission Data Services

Defense Electronics Market Summary

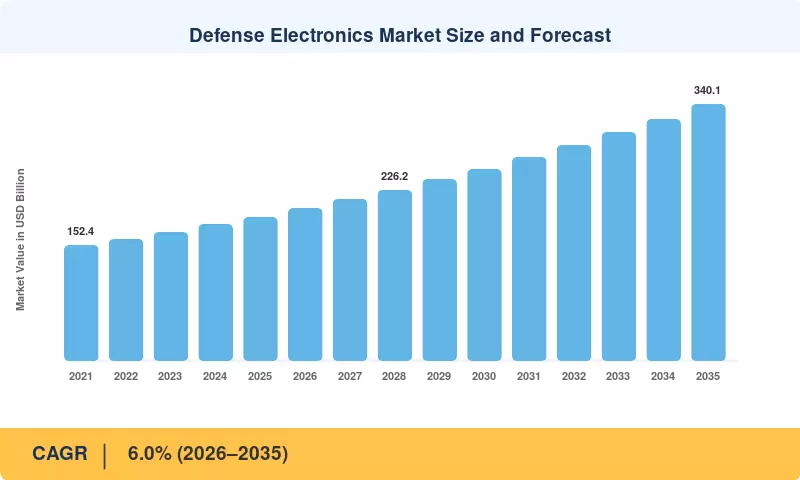
The Defense Electronics Market was valued at USD 189.9 Billion in 2025 and is projected to grow from USD 201.3 Billion in 2026 to USD 340.1 Billion by 2035, a CAGR of 6.0% over 2026–2035. Two catalysts anchor this path. Global military expenditure rose 9.4% to USD 2,718 billion in 2024, the steepest annual increase since the end of the Cold War [1], and NATO allies agreed at The Hague in June 2025 to raise defense and security spending toward 5% of GDP by 2035 [3]. Electronics take a growing share of each budget because sensors, processors and networks now determine a platform's combat value.

Legacy mechanically scanned radars, federated avionics boxes and narrowband radios are being replaced by gallium nitride (GaN) active electronically scanned arrays, open-standard VPX processing and software-defined waveforms. The U.S. Department of Defense requested USD 849.8 billion for FY2025, including about USD 1.8 billion for artificial intelligence [2]. The CHIPS and Science Act committed USD 52.7 Billion to domestic semiconductor manufacturing, research and workforce programs that trusted defense suppliers increasingly draw on [10]. Value is shifting from bespoke hardware toward reusable software and data.

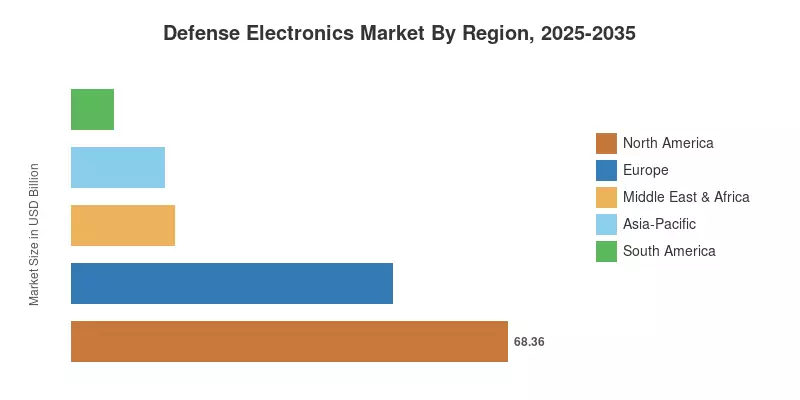
North America holds the largest position with a 36.0% share in 2025, anchored by U.S. procurement of fighter, missile-defense and space sensors. Asia-Pacific is the fastest-growing region at a 7.7% CAGR as Japan, India, South Korea and Australia accelerate modernization. Europe ranks second at USD 50.3 billion, lifted by stock replenishment and joint procurement under the European Defence Fund [18]. Over the next decade, the Defense Electronics Market will increasingly reward suppliers whose electronics can be refreshed faster than the platforms that carry them.

Key Report Takeaways

• By System Type

  • Radar and Multi-Function Sensors led with a 31.6% share of the Defense Electronics Market in 2025.
  • Electronic Warfare Systems are forecast to expand at an 8.7% CAGR through 2035, the fastest among system types.
  • C4ISR and Tactical Communications generated USD 43.1 billion in 2025.

• By Platform

  • Airborne platforms accounted for 47.1% of 2025 revenue.
  • Space platforms post the fastest platform growth at a 7.2% CAGR.

• By Component

  • Hardware held a 69.4% share in 2025.
  • Software grows at a 6.7% CAGR as mission functions move to containerized applications.

• By Fit

  • Line-Fit installations captured 65.8% of 2025 revenue.
  • Retrofit demand advances at a 7.1% CAGR within the Defense Electronics Market.

• By Region

  • North America dominated with a 36.0% share in 2025.
  • Asia-Pacific records the fastest regional growth at a 7.7% CAGR.
  • Europe represented USD 50.3 billion in 2025.

Market Size and Forecast (2021–2035)

Market Research Future sized the Defense Electronics Market through a bottom-up build of platform procurement and upgrade budgets, cross-checked against defense ministry appropriations, prime-contractor segment disclosures and international spending data [1][2]. Values for 2021–2024 are historical, 2025 is the base year, and 2026–2035 are forecasts. Growth slowed in 2022 as component shortages delayed deliveries, then spiked in 2023 when European replenishment orders and U.S. supplemental appropriations converted into backlog.
Defense Electronics Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Record military spending and NATO budget commitments +1.2% Global; strongest in Europe and North America Medium-term (2–4 yr)
Multi-domain operations and networked kill chains +1.0% North America, Europe Long-term (≥4 yr)
GaN AESA radar upgrade cycles +0.9% Global Short-term (≤2 yr)
Proliferated space architectures +0.7% North America Medium-term (2–4 yr)
Asia-Pacific modernization programs +0.8% Asia-Pacific Long-term (≥4 yr)
Semiconductor localization incentives +0.5% North America, Europe Long-term (≥4 yr)
Counter-UAS and spectrum warfare lessons from Ukraine +0.8% Europe, Middle East Short-term (≤2 yr)


Record Military Spending and NATO Budget Commitments

World military expenditure reached USD 2,718 billion in 2024, rising in every region for the tenth consecutive year [1]. NATO's Hague commitment sets a target of 3.5% of GDP for core defense plus 1.5% for resilience and infrastructure by 2035 [3]. Because modern procurement allocates a larger portion of platform cost to sensors, mission computers and datalinks, incremental budget growth flows disproportionately to electronics suppliers, particularly in European states that were spending well under 2% of GDP a decade ago.

Multi-Domain Operations and Networked Kill Chains

The Pentagon's Joint All-Domain Command and Control strategy, published in March 2022, calls for connecting sensors and shooters across every service [4]. The FY2024 budget request earmarked about USD 1.4 billion for combined JADC2 efforts [2]. Each connection requires gateways, secure radios, edge processors and data fusion software. European and Indo-Pacific allies are adopting similar doctrines, which widens demand for interoperable waveforms and cross-domain security appliances well beyond U.S. programs.

GaN AESA Radar Upgrade Cycles

Gallium nitride transistors deliver roughly five times the power density of gallium arsenide, letting designers extend range or shrink apertures [5]. RTX's Lower Tier Air and Missile Defense Sensor, a GaN-based 360-degree radar replacing legacy Patriot sensors, moved into low-rate production after successful U.S. Army testing. Similar replacement cycles are underway for fighter fire-control radars and naval surveillance arrays, compressing upgrade timelines into the next two years.

Proliferated Space Architectures

The U.S. Space Force requested USD 29.4 billion for FY2025 [2], and the Space Development Agency is fielding hundreds of low-Earth-orbit satellites across its Transport and Tracking layers [6]. Each satellite needs radiation-tolerant processors, optical crosslinks and infrared payloads produced at volumes unusual for space hardware. This shift from a few exquisite satellites to proliferated constellations turns space electronics into a repeat-production business.

Asia-Pacific Modernization Programs

Japan's Defense Buildup Program allocates ¥43 trillion over FY2023–FY2027, with major spending on stand-off missiles, integrated air defense and space domain awareness [8]. India set its FY2025–26 defense budget at ₹6.81 lakh crore and reserved 75% of modernization capital for domestic industry [9]. Both programs emphasize sensor fusion and indigenous production, drawing international suppliers into joint ventures and technology-transfer arrangements.

Semiconductor Localization Incentives

Of the CHIPS and Science Act's USD 52.7 billion, USD 39 billion supports manufacturing incentives, several awards of which include trusted-foundry capacity for defense microelectronics [10]. The European Chips Act aims to mobilize €43 billion in public and private investment [11]. Localized supply of RF, mixed-signal and advanced-packaging capability lowers qualification risk for defense programs and supports multi-decade sustainment of fielded electronics.

Counter-UAS and Spectrum Warfare Lessons from Ukraine

RUSI estimated that Ukraine was losing roughly 10,000 drones per month in 2023, largely to Russian jamming [7]. That experience pushed NATO armies to buy counter-UAS sensors, direction finders and portable jammers on accelerated timelines. The U.S. Replicator initiative, launched in August 2023 with about USD 1 billion across FY2024–FY2025, adds demand for low-cost datalinks and resilient navigation [19].

Restraints Impact Analysis

The following estimates are directional and show approximate negative pressure on the Defense Electronics Market CAGR. They are not additive and may partly offset one another as governments respond with policy fixes.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Critical mineral export controls on gallium and germanium −0.6% Global Medium-term (2–4 yr)
Program cost overruns and schedule slips −0.5% North America Short-term (≤2 yr)
Cybersecurity compliance burden for suppliers −0.3% North America Short-term (≤2 yr)
Export control and technology-transfer friction −0.4% Global Long-term (≥4 yr)
Shortage of RF and microelectronics engineers −0.3% North America, Europe Long-term (≥4 yr)


Critical Mineral Export Controls on Gallium and Germanium

In August 2023, China implemented export licensing for germanium and gallium, and in December 2024, sales to the US were prohibited [13]. Approximately 98% of the primary gallium used in GaN radar and jammer amplifiers comes from China. Production ramps could be slowed until Western recycling and refining infrastructure comes up due to price increases and delays in qualifying alternative sources.


Program Cost Overruns and Schedule Slips

GAO has reported F-35 Block 4 modernization costs of roughly USD 16.5 billion and years of schedule slippage [14]. Technology Refresh 3 software problems led the program to withhold aircraft deliveries for about a year before resuming in July 2024 [23]. Overruns of this scale consume modernization budgets and push other electronics upgrades to the right.

Cybersecurity Compliance Burden for Suppliers

The Cybersecurity Maturity Model Certification program rule took effect in December 2024, with a three-year phased rollout into contracts [15]. Small sub-tier suppliers must fund third-party assessments, system hardening and documentation before bidding. Some are expected to exit the defense supply base, narrowing sourcing options for specialized RF and embedded components.

Export Control and Technology-Transfer Friction

International Traffic in Arms Regulations licensing adds months to cross-border programs [16]. The AUKUS exemption effective September 2024 eased transfers among the United States, UK and Australia, but most other partners still face case-by-case reviews. Buyers in the Gulf and Asia increasingly weigh ITAR exposure when choosing suppliers, which fragments potential scale for U.S. firms.

Shortage of RF and Microelectronics Engineers

By 2030, the Semiconductor Industry Association predicts that over 67,000 of the 115,000 new semiconductor jobs in the United States may remain unfilled [17]. Commercial chipmakers and defense electronics compete for the same expertise in RF, packaging, and firmware, and hiring cycles are prolonged by security clearance requirements. The gap restricts the speed at which suppliers can turn backlogs into deliveries.


Defense Electronics Market Opportunities

The Defense Electronics Market offers five opportunity areas where technology, policy and geography align for suppliers over the forecast period.

Modular Retrofit Kits for Legacy Fleets

Modular Open Systems Approach requirements codified in 10 U.S.C. § 4401 favor standardized interfaces that allow sensors and processors to be inserted into aircraft, ships and vehicles already in service. Kit-based AESA and self-protection upgrades, certified once and reused across multiple operators, let suppliers scale sales without new platform starts. Budget-constrained air forces in Eastern Europe and Southeast Asia are prime buyers.

Localization Partnerships in Emerging Markets

The General Authority for Military Industries in Saudi Arabia aims to localize over 50% of military investment by 2030, up from less than 20% in 2023 [20]. Parallel demand is produced by India's reserved domestic purchase budget. In both sectors, where the amount of electronics content per program is rapidly increasing, suppliers who provide co-production, local assembly, and depot maintenance can secure long-term positions.


Software Licensing and Mission Data Services

Applications and hardware are kept apart by open processing backplanes, which allow for ongoing income from threat libraries, mission data files, and automatic target recognition updates. Instead of pricing these as one-time supplies, suppliers can price them as subscriptions linked to threat refresh periods. Vendors benefit from steady margins and a long-term partnership during the platform's life, while operators benefit from quicker updates.


Radiation-Tolerant Electronics for Proliferated Constellations

Proliferated low-Earth-orbit architectures require thousands of rad-tolerant processors, power units and optical terminals [6]. Commercial-grade parts with system-level mitigation are displacing costly rad-hard components in many roles. Mid-tier suppliers with automotive-style production discipline can capture volume that traditional space primes cannot serve efficiently.

Layered Counter-UAS Solutions

Low-cost drone threats have created demand for layered detection, classification and defeat systems at bases, borders and critical infrastructure. Replicator funding of about USD 1 billion signals sustained U.S. interest [19], and European ministries are buying similar layers after Ukraine. Integrators combining passive RF sensing, compact radars and directed jamming can serve both military and homeland security buyers.

Defense Electronics Market Future Outlook

Four themes will shape the Defense Electronics Market over the next decade.

AI at the Tactical Edge

Radars, jammers, and seekers are examples of how artificial intelligence is evolving from HQ analytics. About USD 1.8 billion was sought for AI in the U.S. FY2025 budget [2], and similar programs are being funded by affiliated ministries. Onboard classifiers will frequently detect emitters and targets without a data link by the early 2030s, increasing the need for reliable training data and low-power accelerators.

Software-Defined Platform Economics

Upgrades will be funded more frequently than new platforms thanks to NATO's pledge to core defense spending of 3.5% of GDP by 2035 [3]. Open architectures move the battle from box design to algorithm performance by allowing operators to purchase capability as software advances. A greater percentage of lifecycle value will be captured by suppliers who own developer ecosystems and reference designs.


Space and Hypersonic Defense

Missile warning and tracking from orbit, combined with ground and naval interceptors, forms the backbone of hypersonic defense. Space Force funding of USD 29.4 billion requested for FY2025 [2] underpins steady satellite production. High-temperature electronics, thermal management and 3D packaging for hypersonic vehicles will remain specialized, high-margin niches.

Sovereign Supply Chains and Efficient Design

Export controls on critical minerals [13] and the USD 39 billion in CHIPS manufacturing incentives [10] are pushing governments toward allied sourcing of chips, substrates and rare materials. Energy efficiency also matters, since lower power draw reduces cooling needs and extends endurance for dismounted soldiers and unmanned systems. Supply-chain transparency will become a routine bid requirement.

Regional Market Share Analysis

Region Key Metric (one per region) Primary Investment Themes
North America 36.0% share (2025) Space sensors, missile defense, fighter upgrades
Europe USD 50.3 Billion (2025) Stock replenishment, air defense, joint procurement
Asia-Pacific 7.7% CAGR (2026–2035) Maritime surveillance, indigenous production
South America 3.5% share (2025) Border monitoring, fighter modernization
Middle East & Africa USD 16.2 Billion (2025) Air and missile defense, localization
Total USD 189.9 Billion (2025) —

Regional demand in the Defense Electronics Market reflects each area's budget trajectory, threat environment and industrial base. North America leads in value, while Asia-Pacific grows fastest.


North America

Country Key Metric (one per country) Key Driver
US 88.5% share of region (2025) Space, missile defense and fighter electronics
Canada 5.9% CAGR (2026–2035) NORAD modernization and over-the-horizon radar
Mexico USD 1.4 Billion (2025) Border surveillance and maritime patrol

U.S. demand rests on the FY2025 request of USD 849.8 Billion, with priority lines for missile warning, hypersonic defense and next-generation air dominance [2]. Canada committed C$38.6 billion over 20 years to NORAD modernization, including over-the-horizon radar. Mexico's spending remains modest and focused on surveillance aircraft and border sensors.


Europe

Country Key Metric (one per country) Key Driver
Germany USD 8.6 Billion (2025) Special fund spending on air defense
UK 18.2% share of region (2025) GCAP and naval sensor programs
France 6.4% CAGR (2026–2035) Military programming law and Rafale upgrades
Italy 9.8% share of region (2025) Naval radar and GCAP participation
Spain USD 3.2 Billion (2025) Eurofighter and FCAS commitments
Nordic Countries 7.3% CAGR (2026–2035) Northern-flank air defense
Russia 15.0% share of region (2025) Domestic wartime production
Rest of Europe 6.8% CAGR (2026–2035) Eastern European replenishment

Europe's ReArm Europe plan, presented in March 2025, aims to mobilize up to €800 billion, including €150 billion in SAFE loans for joint procurement [12]. Germany's €100 billion special fund continues to finance air defense and F-35 integration, while the UK committed to 2.5% of GDP by 2027. Nordic states are investing heavily in integrated air defense along NATO's northern flank.


Asia-Pacific

Country Key Metric (one per country) Key Driver
China 38.5% share of region (2025) Naval and air force modernization
India 8.9% CAGR (2026–2035) Indigenous production mandates
Japan USD 7.3 Billion (2025) Integrated air and missile defense
South Korea 11.0% share of region (2025) KF-21 and export programs
ASEAN 8.1% CAGR (2026–2035) Maritime domain awareness
Rest of Asia-Pacific USD 5.9 Billion (2025) AUKUS-linked Australian programs

China raised its 2025 defense budget by 7.2% to about ¥1.78 trillion, prompting counter-investment across the region. Japan's ¥43 trillion buildup [8] and India's domestic procurement reservation [9] drive large sensor and communications orders. South Korea's KF-21 program fields an indigenous AESA radar, and AUKUS strengthens Australia's undersea and electronic capabilities.


South America

Country Key Metric (one per country) Key Driver
Brazil 52.0% share of region (2025) Gripen E and SISFRON
Argentina 4.6% CAGR (2026–2035) F-16 acquisition and sustainment
Rest of South America USD 2.3 Billion (2025) Maritime and border surveillance

Brazil leads regional demand through Gripen E integration and the SISFRON border monitoring system. Argentina agreed in April 2024 to acquire 24 F-16s from Denmark, creating avionics and sustainment demand. Other countries prioritize maritime patrol and anti-trafficking surveillance within tight budgets.


Middle East & Africa

Country Key Metric (one per country) Key Driver
Saudi Arabia USD 5.2 Billion (2025) Vision 2030 localization
UAE 18.5% share of region (2025) EDGE Group and air defense
South Africa 4.9% CAGR (2026–2035) Sustainment and export electronics
Egypt 9.0% share of region (2025) Fighter and naval acquisitions
Rest of MEA 7.0% CAGR (2026–2035) Israeli missile defense programs

Gulf states continue to buy layered air and missile defense while demanding local content under national programs [20]. The UAE's EDGE Group has built domestic electronics and drone capabilities since 2019. Israel's Iron Dome, David's Sling and Arrow systems sustain high sensor demand, and Egypt remains a major buyer of fighters and naval platforms.


Defense Electronics Market By Region, 2025-2035

Defense Electronics Market Segmentation

By System Type

Within the Defense Electronics Market, Radar and Multi-Function Sensors lead with a 31.6% share, sustained by fire-control and early-warning replacements. Electronic Warfare Systems grow fastest at an 8.7% CAGR as forces field cognitive jammers and self-protection pods. C4ISR and Tactical Communications, worth USD 43.1 billion, benefit from mesh networking demands. Optronics and EO/IR Sensors hold a 12.0% share on the strength of GPS-denied navigation, while Others grow at a 5.1% CAGR.

Segment Key Metric (one per segment) Primary Demand Driver
Radar and Multi-Function Sensors 31.6% share (2025) GaN AESA replacement cycles
Electronic Warfare Systems 8.7% CAGR (2026–2035) Cognitive jamming and self-protection
C4ISR and Tactical Communications USD 43.1 Billion (2025) Multi-domain networking
Optronics and EO/IR Sensors 12.0% share (2025) Passive targeting and navigation
Others 5.1% CAGR (2026–2035) Mission computers and navigation


By Platform

Airborne platforms account for 47.1% of the Defense Electronics Market, driven by fighter, tanker and unmanned aircraft programs rich in sensors. Space is the fastest-growing platform at a 7.2% CAGR as proliferated constellations enter production. Land systems, valued at USD 45.6 billion, regain priority through counter-UAS and air-defense investment in Eastern Europe, while Naval platforms hold a 19.5% share supported by surface combatant radar retrofits.

Segment Key Metric (one per segment) Primary Demand Driver
Airborne 47.1% share (2025) Fighter and unmanned aircraft programs
Land USD 45.6 Billion (2025) Counter-UAS and ground air defense
Naval 19.5% share (2025) Surface combatant sensor upgrades
Space 7.2% CAGR (2026–2035) Proliferated satellite constellations


By Component

Hardware remains the core of the Defense Electronics Market with a 69.4% share, reflecting the cost of RF front ends, processors, displays and ruggedized enclosures. Software is the faster-growing component at a 6.7% CAGR as mission functions move to containerized applications on standard processing blades. Recurring license and update revenue makes software-heavy vendors increasingly attractive to buyers and investors alike.

Segment Key Metric (one per segment) Primary Demand Driver
Hardware 69.4% share (2025) RF, processing and packaging content
Software 6.7% CAGR (2026–2035) Containerized mission applications


By Fit

Line-Fit installations lead the Defense Electronics Market with a 65.8% share, since new fighters, frigates and satellites embed current electronics from the start. Retrofit is the fastest-growing fit at a 7.1% CAGR because budget ceilings encourage life extension of existing fleets. Standardized backplanes shorten integration, allowing upgrades within routine depot cycles rather than dedicated modification programs.

Segment Key Metric (one per segment) Primary Demand Driver
Line-Fit 65.8% share (2025) New-build fighter and ship programs
Retrofit 7.1% CAGR (2026–2035) Legacy fleet life extension


Competitive Benchmarking

The Defense Electronics Market shows medium concentration, with an estimated HHI of 500–700 and the top five suppliers holding roughly 38–44% of revenue. U.S. primes dominate large integrated programs, European champions lead in their home markets, and specialized mid-tier firms compete on open-architecture subsystems and retrofit kits. Vertical integration into semiconductors and space payloads is the prevailing strategic pattern.

Company Est. Revenue Share Range Key Offerings for Defense Electronics Market Strategic Positioning
RTX Corporation ~9–12% GaN radars, missile seekers, jammers Air and missile defense leader
Lockheed Martin Corporation ~8–11% Fighter mission systems, space sensors Platform-integrated electronics
Northrop Grumman Corporation ~7–10% AESA radars, space payloads, C4ISR Space and sensor specialist
BAE Systems plc ~6–9% Self-protection suites, space electronics Transatlantic electronics house
L3Harris Technologies, Inc. ~6–8% Tactical radios, ISR, space sensors Communications and space focus
Thales Group ~4–6% Naval radars, secure communications European multi-domain supplier
Leonardo S.p.A. ~3–5% Airborne radars, avionics, EO systems European airborne leader
General Dynamics Corporation ~3–5% Mission IT, networking, C4 systems Integration and networks
Elbit Systems Ltd. ~2–4% EO/IR, self-protection, C4I Combat-proven export supplier
Saab AB ~1–3% Surveillance radars, self-protection Nordic sensor specialist
Hensoldt AG ~1–2% Radars, optronics, spectrum dominance German sensor pure-play


Recent News & Developments

Recent developments shaping the Defense Electronics Market include consolidation, policy shifts and supply-chain actions.

  • L3Harris Technologies (July 2023): Completed its USD 4.7 billion acquisition of Aerojet Rocketdyne, deepening vertical integration across missile propulsion and electronics. [21]
  • U.S. Department of Defense (August 2023): Launched the Replicator initiative to field thousands of attritable autonomous systems, creating demand for low-cost sensors and datalinks. [19]
  • BAE Systems (February 2024): Closed its USD 5.55 billion acquisition of Ball Aerospace, adding spacecraft, antenna and mission-payload capabilities. [22]
  • Lockheed Martin (July 2024): Resumed F-35 deliveries with Technology Refresh 3 hardware after a year-long hold, restoring a major electronics revenue stream. [23]
  • U.S. Department of Defense (October 2024): Published the CMMC program final rule, effective December 2024, setting cybersecurity requirements for suppliers. [15]
  • China MOFCOM (December 2024): Banned exports of gallium, germanium and antimony to the United States, pressuring GaN supply chains. [13]
  • European Commission (March 2025): Presented ReArm Europe, aiming to mobilize up to €800 billion for defense, including €150 billion in SAFE loans. [12]
  • NATO (June 2025): Allies agreed at The Hague to raise defense and security spending toward 5% of GDP by 2035. [3]

Defense Electronics Market Report Scope

Parameter Details
Market Scope Global Defense Electronics Market by System Type, Platform, Component, Fit and Region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.0% (2026–2035)
Market Size checkpoints 2025: USD 189.9 Billion; 2026: USD 201.3 Billion; 2030: USD 254.1 Billion; 2035: USD 340.1 Billion
Fastest Growing Segments Electronic Warfare Systems (8.7% CAGR); Space (7.2% CAGR); Retrofit (7.1% CAGR); Asia-Pacific (7.7% CAGR)
Companies Profiled RTX, Lockheed Martin, Northrop Grumman, BAE Systems, L3Harris, Thales, Leonardo, General Dynamics, Elbit Systems, Saab, Hensoldt
Valuation Currency USD Billion

FAQs

How should investors assess software-centric suppliers in the Defense Electronics Market?
Focus on recurring license and sustainment revenue, which carries higher margins than one-time hardware deliveries. Check whether the supplier owns its intellectual property, since government data-rights clauses determine who captures future upgrade revenue.
Which contracting vehicles move fastest in Defense Electronics Market procurement?
Other Transaction agreements let the Pentagon prototype electronics outside full FAR rules, often within a year [24]. Successful prototypes can transition directly to follow-on production without a new competition.
How do ITAR-free designs affect competitiveness in the Defense Electronics Market?
European and Israeli suppliers market ITAR-free subsystems to buyers avoiding U.S. re-export approvals [16]. Any ITAR-controlled part inside the system, however, reimposes U.S. licensing through the see-through rule.
Why do new radar programs favor gallium nitride over gallium arsenide?
GaN transistors handle higher voltages and deliver several times the power density, extending detection range from the same aperture. They also tolerate higher temperatures, reducing cooling loads on weight-constrained aircraft.
What slows integration of third-party applications onto open architectures?
Certification is the bottleneck, because each application needs cybersecurity accreditation and, for flight systems, airworthiness review. Vendors that pre-qualify software against SOSA or FACE conformance shorten this cycle considerably.
How does commercial technology reach defense electronics programs?
The Defense Innovation Unit's Commercial Solutions Openings award prototype agreements to non-traditional vendors, frequently within 60 to 90 days [24]. Commercial AI chips and satellite imaging have entered service this way.
Which test standards govern rugged defense electronics?
Most programs require MIL-STD-810H for environmental stress and MIL-STD-461G for electromagnetic interference [25]. Qualification can add six to twelve months to a schedule, so suppliers reuse pre-qualified modules wherever possible.
Author
Author Author Profile Abbas Raut LinkedIn Research Analyst
Abbas Raut is a Senior Research Analyst with 5+ years of experience delivering data-driven insights and strategic recommendations across the Automotive and Aerospace & Defense sectors. He specializes in emerging technologies, industry value chains, and global market dynamics shaping the future of mobility and defense. In automotive, Abbas has led studies on EVs, charging stations, BMS, superchargers, and more, guiding stakeholders through electrification and regulatory shifts. In Aerospace & Defense, he has analyzed markets for military electronics, drones, radars, and electronic warfare solutions, supporting procurement and investment strategies. With expertise in market sizing, forecasting, benchmarking, and technology adoption, Abbas is known for transforming complex datasets into actionable insights that drive strategy, innovation, and growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of defense procurement databases, military technology journals, defense policy publications, and authoritative aerospace & defense organizations. Key sources included the US Department of Defense (DoD), Defense Advanced Research Projects Agency (DARPA), North Atlantic Treaty Organization (NATO) Standardization Office, European Defence Agency (EDA), UK Ministry of Defence (MOD), French Ministry of Armed Forces, German Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support (BAAINBw), Japan Ministry of Defense, Indian Ministry of Defence, Australian Department of Defence, Israel Ministry of Defense, Swedish Defence Materiel Administration (FMV), US Defense Security Cooperation Agency (DSCA), Stockholm International Peace Research Institute (SIPRI), Jane's Defence Intelligence, Teal Group, Aerospace Industries Association (AIA), Association of the United States Army (AUSA), National Defense Industrial Association (NDIA), European Defence Industries Group, US Government Accountability Office (GAO) Defense Reports, Congressional Research Service (CRS), and national defense budget reports from key markets. These sources were used to collect procurement statistics, contract award data, technology readiness levels, defense spending trends, regulatory compliance requirements, and competitive landscape analysis for radar systems, electronic warfare systems, communication systems, C4ISR systems, and other defense electronics technologies.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Defense electronics manufacturers, system integrators, and subsystem suppliers included CEOs, VPs of Engineering, chief technology officers, program directors, business development leaders, and regulatory compliance officers as supply-side sources. The demand-side sources included program managers from defense ministries, military procurement officers, chief information officers from armed forces, defense attachés, fleet commanders, and operations leaders from air force, naval, and army divisions in NATO and allied nations. The primary research validated market segmentation, confirmed technology development roadmaps, and collected insights on procurement cycles, offset agreement structures, interoperability standards, and modernization priorities.


Primary Respondent Breakdown

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (40%), Europe (30%), Asia-Pacific (22%), Rest of World (8%)


Market Size Estimation

Global market valuation was derived through contract value analysis and defense budget allocation modeling. The methodology included:

Identification of 60+ key defense contractors and electronics specialists across North America, Europe, Asia-Pacific, Middle East, and Latin America

Product mapping across radar systems, electronic warfare/countermeasures, military communications, C4ISR, electro-optics/infrared systems, and other defense electronics categories

Analysis of reported and modeled annual revenues specific to defense electronics portfolios

Coverage of manufacturers representing

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Aircraft MRO Market
Case Study
Aerospace & Defense
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















