Deep Tech Market Summary
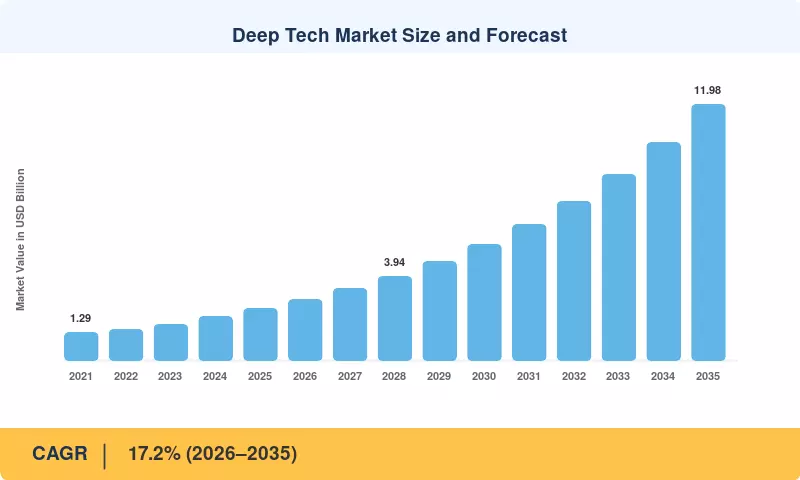
The Deep Tech Market was valued at USD 2.45 Billion in 2025 and is projected to grow from USD 2.87 Billion in 2026 to USD 11.98 Billion by 2035, a CAGR of 17.2% over the 2026–2035 forecast period. Two public programs anchor the trajectory. The US CHIPS and Science Act committed USD 52.7 billion to domestic semiconductor manufacturing and research [1], and the European Chips Act aims to mobilize EUR 43 billion in public and private capital [2]. Both programs lower the cost of the hardware layer that AI, quantum, and robotics ventures rely on, and they draw private co-investment into earlier funding rounds.
The technology base is changing quickly. Rules-based enterprise software, classical high-performance computing, and manual laboratory trial-and-error are giving way to foundation models, quantum processors, and AI-guided discovery platforms. US private AI investment reached USD 109.1 billion in 2024, according to the Stanford AI Index [3]. Much of that capital now flows to frontier technology startups, which turn research breakthroughs into licensable platforms rather than one-off projects.
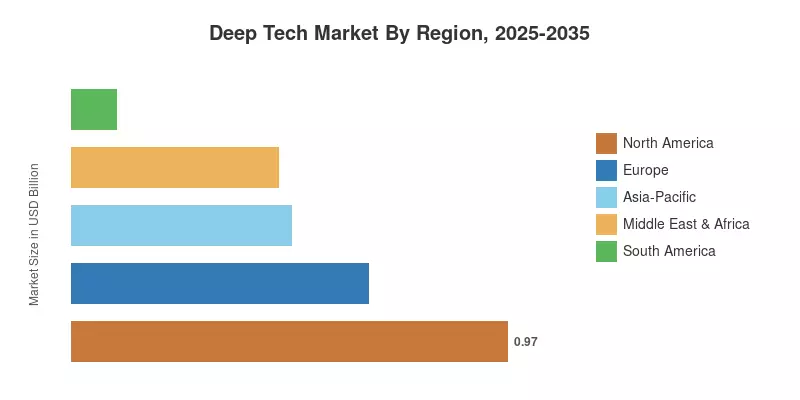
North America leads the Deep Tech Market with a 39.5% share, supported by hyperscaler capital and defense procurement. Asia-Pacific is the fastest-growing region at a 20.1% CAGR, driven by sovereign AI and quantum missions in India, China, Japan, and South Korea. Europe ranks second with a 27.0% share, backed by the European Innovation Council and national quantum strategies. Over the next decade, the balance of spending should shift from pure AI toward quantum and bio-convergence platforms.
Key Report Takeaways
• By Technology
- Artificial Intelligence holds a 34.5% share of the Deep Tech Market, reflecting mature cloud deployment and sovereign AI mandates
- Quantum Computing is the fastest-growing technology at a 21.1% CAGR as error-corrected hardware reaches industrial pilots
• By Funding Stage
- Series A-Series B rounds capture 50.6% of capital, reflecting investor preference for validated prototypes
- Seed/Pre-seed funding is expanding at a 21.5% CAGR, supported by grant leverage and specialist funds
• By Application
- Data Analytics and Optimization accounts for 24.9% of revenue, supported by established AI pipelines in finance and logistics
- Industrial Automation grows at a 20.3% CAGR as foundation models coordinate multi-robot production cells
• By End-User Industry
- IT and Telecom leads the Deep Tech Market with a 23.0% share on the back of 5G-cloud and AI silicon demand
- Healthcare and Life Sciences posts a 19.8% CAGR through 2035 on imaging AI and drug discovery adoption
• By Region
- North America holds a 39.5% share, anchored by federal research programs and hyperscaler spending
- Asia-Pacific expands at a 20.1% CAGR, led by India's national AI and quantum missions
- Europe secures a 27.0% share through coordinated EU and national funding instruments
Market Size and Forecast (2021–2035)
Market sizing combines bottom-up revenue mapping of commercial AI, quantum, robotics, advanced materials, and synthetic biology vendors with top-down reconciliation against venture funding databases, public R&D budgets, and company disclosures. Historical values for 2021–2024 are based on reported revenue and funding data. The forecast applies technology-specific adoption curves weighted by regional policy intensity. All values are in USD Billion at constant exchange rates.





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



