Copier Paper Market Summary
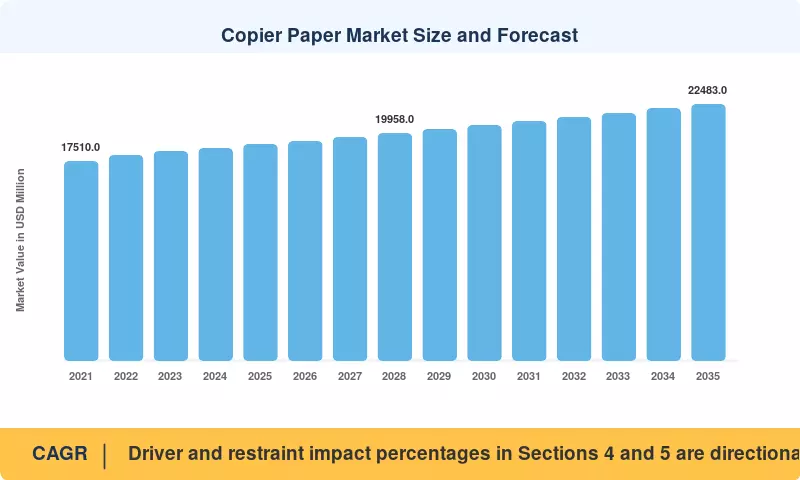
The Copier Paper Market reached USD 18,940 Million in 2025 and opens the forecast window at USD 19,268 Million in 2026, advancing to USD 22,483 Million by 2035 at a 1.73% CAGR. Growth is deliberate rather than dramatic. Two catalysts anchor the trajectory: the European Union's Green Public Procurement criteria for copying and graphic grades, which now govern billions of euros of institutional tendering [7], and India's UDISE+ enrolment base of more than 248 million school students, whose examination and assessment cycles convert directly into ream volume [14].
The technology narrative is characterized by substitution, not expansion. Mills are discontinuing older uncoated machine assets that were designed for heavyweight furnish and retooling in order to accommodate de-inked pulp lines and lighter grammage bands. Investment is contingent upon compliance: Operators are required to exhibit deforestation-free sourcing with geolocation-level traceability in accordance with Regulation (EU) 2023/1115. This requirement has compelled European producers to reconstruct fiber-tracking systems throughout the Copier Paper Market [6]. The majority of capital budgets are allocated to energy-efficient dryers and closed-loop water systems, while artificial intelligence quality monitoring reduces the number of breakdowns on existing lines [12].
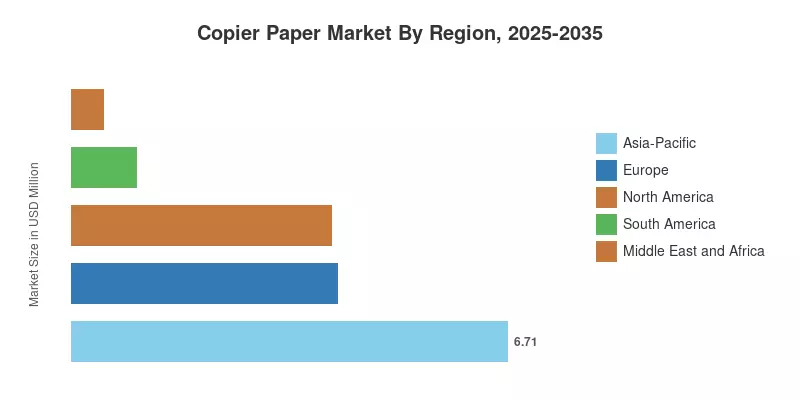
China's extensive installed printer fleet and India's expanding administrative documentation base are the primary drivers of Asia-Pacific's 37.3% global demand [4]. The baseline consumption is bolstered by government examination printing mandates and urban business formation, resulting in the Middle East and Africa experiencing the highest growth rate at a 2.71% CAGR [24]. Federal recycled-content purchasing rules, rather than volume, more influence the grade mix, as North America ranks second at 24.6% [8]. Producers who are capable of maintaining cost discipline while simultaneously verifying fiber provenance will be rewarded by the Copier Paper Market in the coming decade.
Key Report Takeaways
• By Paper Size
- A4 accounted for 64.1% of Copier Paper Market share in 2025, entrenched by ISO 216 alignment across multinational archiving workflows.
- A3 posts the dimension's fastest expansion at a 2.28% CAGR through 2035, tracking design studio and technical drawing output.
• By Raw Material
- Virgin Wood Pulp retained a 58.3% share in 2025, favoured where archival permanence is contractually specified.
- Recycled Fibre advances at a 2.66% CAGR as institutional buyers convert sustainability targets into tender clauses.
• By End User
- Corporate and Commercial Offices contributed 36.6% of Copier Paper Market share in 2025
- Print-for-Pay / Copy Shops grow at a 2.61% CAGR as enterprises outsource non-core print jobs.
• By Distribution Channel
- B2B/Wholesale controlled 39.4% share in 2025 through contracted monthly call-offs
- Stationery/Retail Stores lead channel growth at a 2.45% CAGR, serving freelancers and micro-enterprises
• By Region
- Asia-Pacific commanded 37.3% of global demand in 2025
- Middle East and Africa is the fastest-growing region at a 2.71% CAGR
- Europe generated USD 4,318 million in 2025, shaped by procurement regulation rather than volume growth
Market Size and Forecast (2021–2035)
Figures below combine mill-level shipment data from national statistical agencies and industry federations with distributor sell-through sampling across 41 countries [1][2][3]. Historical values were reconciled against producer annual reports and customs trade flows; forecast years apply grade-mix weighted pricing to projected tonnage. The Copier Paper Market series is expressed in USD Million at constant 2025 exchange rates.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



