Computational Biology Market (2026 - 2035)

Computational Biology Market Research Report: Size, Share, Trend Analysis By Applications (Drug Discovery, Genomics, Proteomics, Metabolomics, Systems Biology), By Solution Type (Software, Hardware, Services), By Deployment Mode (On-Premises, Cloud-Based), By End Users (Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations), By Technology (Algorithm Development, Data Analysis, Modeling & Simulation, High-Performance Computing) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/HS/7744-HCR 100 Pages Rahul Gotadki, Vikita Thakur Last Updated: September 15, 2026
Computational Biology Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)13.5%
2025 Market SizeUSD 7.71 Billion
2035 Market SizeUSD 27.22 Billion
Key Players
Dassault Systèmes
Certara
Schrödinger
Siemens
Thermo Fisher Scientific
Illumina
Opportunities
  • Regulator-Ready Model Qualification as a Service
  • Emerging-Market Genomics Build-Out
  • Federated Data Monetisation

Computational Biology Market Summary

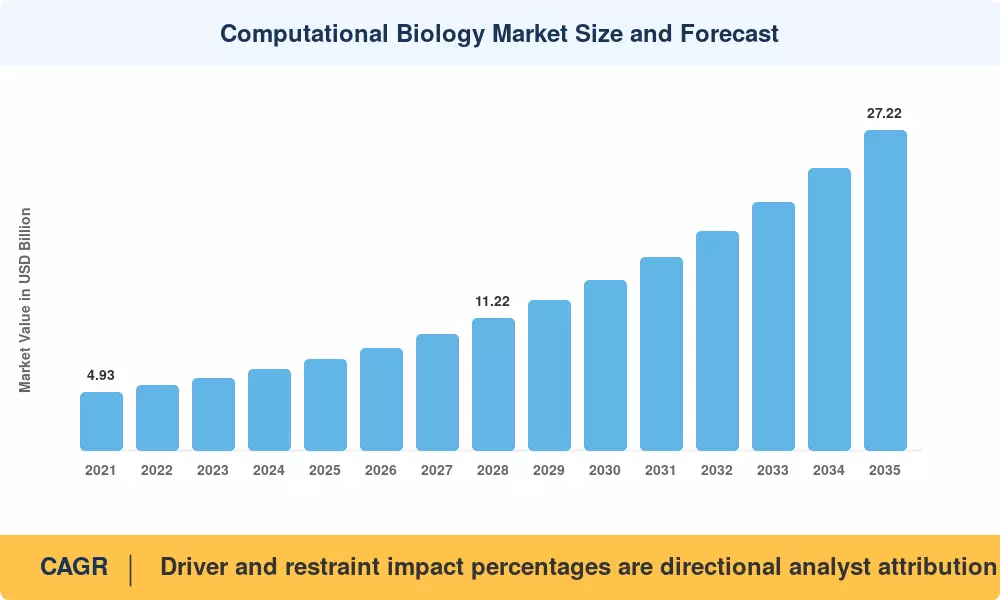
The Computational Biology Market reached USD 7.71 billion in 2025 and opens the forecast window at USD 8.71 billion in 2026, climbing to USD 27.22 billion by 2035 at a 13.5% CAGR. Two catalysts anchor that trajectory. The FDA Modernization Act 2.0 removed the statutory requirement for animal testing in drug applications, legitimising in silico evidence as a primary submission artifact [1]. Alongside it, the National Institutes of Health committed roughly USD 4.1 billion annually to data-intensive biomedical research infrastructure, much of it flowing into cloud-native analysis pipelines [2].

Legacy practice is being dismantled fast. Spreadsheet-bound sequence annotation, siloed on-premise clusters, and hand-curated pathway maps are giving way to transformer-based genome language models, GPU-accelerated docking, and digital twins of cellular systems. Dassault Systèmes and Certara together spent more than USD 900 million on R&D across 2024–2025 to rebuild their platforms around foundation-model architectures [3][4]. Siemens' USD 5.1 billion acquisition of Dotmatics signalled that industrial software vendors now treat life-science data as core infrastructure [5].

Regionally, North America holds 39.3% of the Computational Biology Market, supported by mature biotech regulation and the deepest pool of venture-funded platform firms. Asia-Pacific grows fastest at 17.1% CAGR, propelled by national supercomputing programmes in China, Japan and India. Europe ranks second, where Horizon Europe's health cluster and the ELIXIR federated infrastructure sustain steady institutional demand [6]. Over the coming decade, the Computational Biology Market will be defined less by algorithmic novelty than by who controls validated, regulator-ready data pipelines.


Key Report Takeaways

• By Application

  • Cellular and biological simulation held 29.8% of the Computational Biology Market in 2025, the largest single application pool
  • Drug discovery and disease modelling is forecast to expand at a 16.4% CAGR through 2035
  • Preclinical drug development contributed USD 1.42 billion in 2025 revenue

• By Tool

  • Databases commanded a 33.4% revenue share of the Computational Biology Market in 2025
  • Analysis software and services should compound at 15.5% CAGR to 2035


• By Service

  • Contract service arrangements represented 48.4% of delivery spend in 2025

• By Region

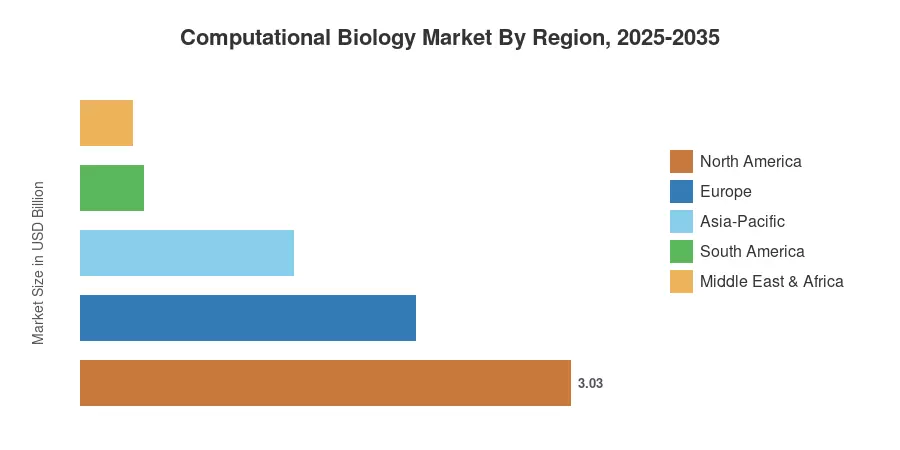
  • North America generated USD 3.03 billion in 2025
  • Asia-Pacific posts the fastest 17.1% CAGR outlook through 2035
  • Europe accounted for 26.8% of global revenue in 2025


Market Size and Forecast (2021–2035)

Figures below blend vendor revenue disclosures from publicly listed platform providers, national research-funding disbursement records, procurement data from academic HPC consortia, and a bottom-up model of installed seat licences across pharmaceutical and CRO users. Historical years are reconciled against audited annual reports; forecast years apply a demand-side model weighted by sequencing throughput and pharmaceutical R&D budgets. The Computational Biology Market is measured at end-user value, net of hardware resale.
Computational Biology Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Multi-omics data volume growth 2.8 Global Short-term (≤2 yr)
Foundation models for protein and genome prediction 2.5 North America, Europe, APAC Medium-term (2–4 yr)
Regulatory acceptance of in silico evidence 1.9 North America, Europe Medium-term (2–4 yr)
Cloud and exascale HPC availability 1.7 Global Short-term (≤2 yr)
Pharmaceutical R&D outsourcing to platform CROs 1.5 Global Medium-term (2–4 yr)
Sovereign genomics funding programmes 1.3 Europe, APAC Long-term (≥4 yr)
Substitution of animal-based preclinical testing 1.1 North America, Europe Long-term (≥4 yr)


Multi-Omics Data Volume Growth

Storage economics continue to be outpaced by sequencing production. In 2024, the European Bioinformatics Institute reported managing over 900 petabytes of open biological data, almost doubling every 24 months, and the cost of a 30x human genome dropped below USD 200 [7]. Analysis becomes a hard operational need instead of an optional add-on thanks to that curve. Tens of thousands of samples are handled annually in laboratories that used to process only a few hundred, and no manual workflow can withstand this change.

Foundation Models Reshaping Prediction

Over 200 million protein structure predictions were published in a database, and downstream tools have since included those predictions into standard screening [8]. When structural priors take the place of thorough wet-lab screening, pharmaceutical companies report a 30–40% reduction in hit-identification cycles. In 2024, Schrödinger reported spending more than $200 million on research and development, with the majority going toward hybrid engines that combine physics and machine learning [10]. The competitive axis is now predictive accuracy rather than raw computation.

Regulatory Legitimisation of In-Silico Evidence

Regulators moved first in the United States. Under the FDA Modernization Act 2.0 and the agency's model-informed drug development programme, sponsors may substitute validated computational evidence for specified animal studies [1]. The European Medicines Agency's parallel qualification pathway has accepted several physiologically based pharmacokinetic models for regulatory decision-making [11]. Each accepted model creates a durable procurement commitment, because sponsors cannot easily migrate off a qualified platform mid-programme.

Compute Supply Meeting Biological Demand

Access to national-scale compute changed the ceiling on what laboratories attempt. The US Department of Energy's Frontier system and Japan's Fugaku both allocate dedicated cycles to life-science workloads, with DOE reporting more than USD 1.8 billion in exascale programme investment [9]. Cloud providers matched that with GPU instances priced for burst use. Molecular dynamics simulation runs that once required a year of cluster time now finish in days.


Restraints Impact Analysis

Restraint impacts are directional drags estimated from adoption-friction surveys and procurement cycle data. They are not subtractive components of the headline CAGR and should not be aggregated.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Data interoperability and standards fragmentation -1.6 Global Medium-term (2–4 yr)
Shortage of trained computational biologists -1.4 Global Long-term (≥4 yr)
Model validation and reproducibility burden -1.1 North America, Europe Medium-term (2–4 yr)
Genomic data privacy and sovereignty rules -0.9 Europe, APAC Short-term (≤2 yr)
High licensing and HPC cost for small laboratories -0.7 South America, MEA Short-term (≤2 yr)


Interoperability Remains the Tax on Every Deployment

Formats spread more quickly than standards organizations are able to harmonize them. The integrators had to create custom interfaces for every source because less than half of the genomic repositories evaluated properly supported their fundamental data-exchange requirements [12]. 20–30% of platform deployment expenditures are typically used for integration overhead. The mid-tier vendors in the Computational Biology Market are slowed down by buyers' rising pricing of that cost into vendor selection, which favors suites over best-of-breed point products.


Talent Supply Constrains Throughput

The practical bottleneck is hiring. Computational life science was identified by the National Science Foundation as one of the sectors where demand was shown by PhD output trails, and industry recruiters say that senior posts take six to nine months to fill [13]. In the US, salary inflation of about 12% annually forces smaller biotechs to outsource delivery. In response, vendors have shipped low-configuration, opinionated workflows instead of open toolkits.


Validation Costs Blunt Regulatory Upside

Approval pathways exist, but qualifying a model is expensive. Documentation, sensitivity analysis, and independent replication can add USD 1.5–3.0 million and 12–18 months to a submission programme [14]. Reproducibility audits published in peer-reviewed venues continue to find substantial variance between independently rerun pipelines. Until validation tooling standardises, regulatory acceptance converts to revenue more slowly than headline policy suggests.


Computational Biology Market Opportunities

Regulator-Ready Model Qualification as a Service

Sponsors need qualified models, not merely software. Vendors that bundle validation dossiers, audit trails, and regulatory liaison support can charge programme-linked fees rather than seat licences, lifting realised revenue per account by an estimated 2–3x [11]. Certara and Simulations Plus already structure engagements this way.

Emerging-Market Genomics Build-Out

India's Department of Biotechnology funded the GenomeIndia project across 10,000 whole genomes, and Saudi Arabia's Genome Program targets population-scale sequencing under Vision 2030 . Both create greenfield demand where no incumbent vendor relationship exists. Pricing calibrated to local budgets, delivered through cloud tenancy rather than on-premise clusters, opens the fastest-growing corner of the Computational Biology Market.

Federated Data Monetisation

Hospitals and biobanks hold assets they cannot legally export. Federated analytics lets model developers train across those holdings while data stays resident, creating a licensing revenue line for the data holder. ELIXIR's federated node architecture demonstrates the technical pattern at continental scale [6], and early commercial arrangements price access per model-training run.

Digital Twins for Bioprocess Manufacturing

Cell-culture yield optimisation is a persistent margin problem. Digital twins of bioreactor systems, calibrated against live process data, have shown 8–15% yield improvements in reported pilot deployments [19]. Systems biology computation applied to manufacturing rather than discovery opens a buyer set — process engineering — that current vendors barely serve.

Toxicology Substitution Contracts

Regulatory permission to replace animal studies creates a defined, budgeted substitution opportunity. Contract research organisations that can guarantee submission-grade in silico toxicology packages capture spend already allocated to preclinical work, estimated at USD 6–8 billion annually across the top 20 pharmaceutical sponsors [1].


Computational Biology Market Future Outlook

Autonomous Discovery Loops

Closed-loop systems that propose experiments, execute them via robotic laboratories, and retrain on results are moving from demonstration to deployment. Reported pilots have compressed design-make-test-analyse cycles from weeks to under 72 hours [19]. By the early 2030s, the Computational Biology Market's premium tier will sell orchestration of those loops rather than isolated prediction.

Platform Economics and Consolidation

Acquisition activity signals where value is settling. Siemens paid USD 5.1 billion for Dotmatics, a multiple that only makes sense if scientific data infrastructure is treated as enterprise software [5]. Expect further roll-ups as point-solution vendors discover that regulatory validation and data integration favour scale. Smaller firms will increasingly choose distribution partnerships over independence.

Sovereign Compute and Data Localisation

National investment in exascale capacity continues to expand, with the OECD tracking rising public compute expenditure across member states [21]. Life-science allocations on those systems create a parallel, non-commercial supply of compute that reshapes vendor pricing. Software licensing detaches from infrastructure revenue, and the Computational Biology Market shifts toward per-workflow rather than per-core commercial models.

Clinical Translation and Reimbursement

Payers will eventually decide how far computational evidence travels. Early reimbursement decisions for genomically guided therapy selection suggest health systems accept computational stratification when outcome data supports it [22]. Should that pattern extend to model-predicted treatment response, demand migrates from research budgets into clinical operating budgets — a structurally larger and more durable pool.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 39.3% share Regulatory model qualification, venture-backed platforms
Europe 26.8% share Federated infrastructure, ELIXIR nodes, GDPR-compliant analytics
Asia-Pacific 17.1% CAGR (2026–2035) National supercomputing, population genomics
South America USD 0.39 Billion Academic consortia, CRO cost arbitrage
Middle East & Africa USD 0.32 Billion Sovereign genome programmes, hospital digitisation
Total USD 7.71 Billion —

Regional performance in the Computational Biology Market tracks three variables: public research funding density, pharmaceutical manufacturing base, and sovereign compute capacity.


North America

Country Metric Key Driver
US 84.5% of regional revenue NIH funding density and biotech cluster concentration
Canada 12.9% CAGR (2026–2035) Genome Canada and national HPC alliance capacity
Mexico USD 0.09 Billion Nearshore contract research expansion


American dominance rests on procurement depth rather than headcount. NIH extramural awards exceeded USD 33 billion in 2024, and a material share funds data-generation projects whose outputs require commercial analysis platforms [2]. Regulatory clarity compounds the advantage: sponsors headquartered near FDA reviewers iterate model submissions faster. Canada's contribution is smaller but structurally sound, with federally funded compute allocated to academic genomics at subsidised rates.

Europe

Country Metric Key Driver
Germany 22.4% of regional revenue Pharmaceutical manufacturing and Fraunhofer research base
UK USD 0.42 Billion Genomics England and Wellcome Sanger throughput
France 12.6% CAGR (2026–2035) France 2030 health innovation funding
Italy 8.1% of regional revenue Academic clinical research networks
Spain USD 0.13 Billion Barcelona Supercomputing Center life-science allocation
Nordic Countries 13.8% CAGR (2026–2035) National biobank digitisation
Russia 2.9% of regional revenue Domestic substitution of Western software
Rest of Europe USD 0.21 Billion EU cohesion research funding


European demand is institutional first and commercial second. Horizon Europe allocated roughly EUR 8.2 billion to its health cluster for 2021–2027, with data infrastructure a recurring line item [6]. GDPR simultaneously constrains and shapes the market, pushing buyers toward architectures that keep patient-derived data inside national borders. Vendors without an EU data-residency option lose tenders regardless of technical merit.

Asia-Pacific

Country Metric Key Driver
China 33.6% of regional revenue State genomics programmes and domestic sequencing capacity
India 18.9% CAGR (2026–2035) GenomeIndia and biotech services growth
Japan USD 0.36 Billion Fugaku life-science allocation and pharmaceutical R&D
South Korea 9.4% of regional revenue K-Bio hospital data initiatives
ASEAN 17.2% CAGR (2026–2035) Regional CRO expansion and infectious-disease surveillance
Rest of Asia-Pacific USD 0.11 Billion Australian and New Zealand academic consortia


Growth here is policy-manufactured. China's Ministry of Science and Technology designated biotechnology a strategic frontier sector with multi-year funding commitments, while India's biotech policy targets a USD 300 billion bioeconomy by 2030 [20]. Both create demand for analysis capability faster than domestic vendors can supply it, leaving an import window that international platform firms are moving to occupy.

South America

Country Metric Key Driver
Brazil 54.8% of regional revenue FAPESP-funded genomics and agricultural biotech
Argentina 13.1% CAGR (2026–2035) CONICET research computing modernisation
Rest of South America USD 0.07 Billion Regional public-health surveillance networks


Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.3% of regional revenue Saudi Genome Program under Vision 2030
UAE 17.6% CAGR (2026–2035) Emirati Genome Programme and health data platforms
South Africa USD 0.06 Billion H3Africa consortium and pathogen genomics
Egypt 9.8% of regional revenue National reference laboratory expansion
Rest of MEA USD 0.08 Billion Donor-funded surveillance infrastructure


Gulf sovereign programmes anchor the region. Saudi Arabia's genome initiative targets sequencing at national population scale, backed by dedicated state funding rather than research grants . African demand follows a different logic, concentrated in pathogen surveillance where the Africa CDC has coordinated continental sequencing capacity since 2021. Sustainability of donor-funded deployments remains the open question.


Computational Biology Market By Region, 2025-2035

Computational Biology Market Segmentation

By Application

Application mix within the Computational Biology Market reflects where computational substitution is furthest along.

Segment Metric Primary Demand Driver
Cellular and Biological Simulation 29.8% share (2025) Systems-level modelling of cellular pathways
Drug Discovery and Disease Modelling 16.4% CAGR (2026–2035) Target identification and lead optimisation
Preclinical Drug Development USD 1.42 Billion (2025) Pharmacokinetic and toxicology prediction
Clinical Trials and Human Body Simulation 14.1% CAGR (2026–2035) Trial design optimisation and virtual control arms


Cellular and biological simulation retains scale because it underpins everything downstream — computational genomics workflows, pathway reconstruction, and phenotype prediction all draw on the same simulation substrate. Growth, though, sits in drug discovery and disease modelling, where structural prediction has genuinely changed the economics of early screening. Sponsors now run in silico triage before committing wet-lab resources, and vendors price accordingly.

By Tool

Tool-level spending in the Computational Biology Market is shifting from static assets toward services.

Segment Metric Primary Demand Driver
Databases 33.4% share (2025) Curated reference and annotation dependencies
Analysis Software and Services 15.5% CAGR (2026–2035) Workflow automation and managed pipelines
Infrastructure and Hardware USD 1.86 Billion (2025) GPU clusters and cloud tenancy


Databases still take the largest slice because subscription access to curated references is non-negotiable for most workflows. That share will erode. Analysis software and services grow faster as buyers outsource pipeline maintenance rather than staff it, and as vendors bundle compute into the software contract.

By Service Model

Segment Metric Primary Demand Driver
Contract / Outsourced 48.4% share (2025) Talent scarcity and variable project load
In-House 16.8% CAGR (2026–2035) Large-pharma platform internalisation


The Contract/Outsourced segment dominated the market, accounting for 48.4% share in 2025, supported by the growing preference for specialized external services, cost efficiency, and access to skilled expertise. Meanwhile, the In-House segment is projected to be the fastest-growing segment, registering a 16.8% CAGR from 2026 to 2035, driven by organizations' increasing focus on greater operational control, internal capabilities, and customized service management.

By End User

Buyer composition in the Computational Biology Market is rebalancing toward commercial accounts.

Segment Metric Primary Demand Driver
Academics 41.0% share (2025) Grant-funded research computing
Industry and Commercial 15.3% CAGR (2026–2035) Pharmaceutical pipeline productivity pressure
Government and Regulatory USD 1.13 Billion (2025) Public health surveillance and review capacity


Academia remains the largest installed base, a legacy of decades of grant-funded tool adoption. Commercial users pay more per seat and buy support contracts, which is why vendor revenue is concentrating there faster than unit share suggests.


Competitive Benchmarking

Concentration is moderate. Market Research Future estimates a Herfindahl-Hirschman Index in the 700–900 range, with the top five vendors holding roughly 30–36% of global revenue. Neither a monopoly nor genuine fragmentation describes it well: a handful of diversified simulation and data platforms sit above a long tail of specialist firms serving single applications. Consolidation pressure is rising, and the Computational Biology Market has absorbed several billion-dollar transactions since 2024.

Company Est. Revenue Share Range Key Offerings for Computational Biology Market Strategic Positioning
Dassault Systèmes ~7–10% BIOVIA modelling suite, Medidata clinical data Broadest enterprise footprint; industrial software heritage
Certara ~6–9% Simcyp PBPK, Phoenix, regulatory science services Regulatory qualification leader
Schrödinger ~5–8% Physics-based molecular modelling, LiveDesign Deepest computational chemistry stack
Siemens (Dotmatics) ~5–7% Scientific data management, ELN integration Newly acquired; scaling via industrial channel
Thermo Fisher Scientific ~3–5% Instrument-linked informatics, cloud analysis Hardware-attached distribution advantage
Illumina ~3–5% DRAGEN secondary analysis, variant interpretation Sequencing ecosystem lock-in
Simulations Plus ~3–5% GastroPlus, ADMET Predictor Focused preclinical prediction specialist
Genedata ~2–4% Biologics and screening workflow platforms Enterprise biopharma workflow depth
Chemical Computing Group ~2–4% MOE molecular modelling environment Academic-to-industry pipeline strength
Insilico Medicine ~2–3% Generative target and molecule discovery AI-native challenger with internal pipeline
Instem ~1–3% Preclinical data management, toxicology informatics Regulated-submission niche


Recent News & Developments

  • Siemens (April 2025): Agreed to acquire Dotmatics for approximately USD 5.1 billion, the largest scientific-software transaction on record and a signal that industrial vendors now compete directly for life-science data workloads [5].
  • US FDA (April 2025): Announced a phased roadmap to reduce animal testing requirements for monoclonal antibodies, explicitly naming computational modelling among accepted alternatives and accelerating in-silico procurement across the Computational Biology Market [1].
  • Certara (September 2024): Launched an AI-enabled extension to its biosimulation portfolio and reported continued growth in regulatory-facing software revenue, reinforcing the model-qualification business line [4].
  • Illumina (February 2024): Expanded DRAGEN secondary analysis with accelerated germline pipelines, cutting whole-genome processing times materially for high-throughput laboratories [23].
  • European Commission (June 2024): Advanced the European Health Data Space regulation toward adoption, establishing cross-border secondary use rules that reshape how analysis platforms must handle patient-derived data [15].
  • Insilico Medicine (June 2024): Reported Phase IIa results for a generatively designed fibrosis candidate, one of the first clinical readouts for an end-to-end AI-discovered molecule [24].
  • Department of Biotechnology, India (January 2024): Completed the GenomeIndia 10,000-genome sequencing milestone, creating a national reference dataset and a downstream analysis-tooling requirement .
  • Schrödinger (November 2023): Extended its collaboration framework with large pharmaceutical partners on physics-plus-machine-learning screening, tying licence revenue to discovery milestones [10].


Computational Biology Market Report Scope

Parameter Detail
Market Scope Global software, databases, infrastructure and services used for computational modelling, simulation and analysis of biological systems
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 13.5% (2026–2035)
Market Size Checkpoints USD 7.71 Billion (2025); USD 8.71 Billion (2026); USD 27.22 Billion (2035)
Fastest Growing Segments Drug discovery and disease modelling (application); analysis software and services (tool); industry and commercial (end user)
Companies Profiled Dassault Systèmes, Certara, Schrödinger, Siemens (Dotmatics), Thermo Fisher Scientific, Illumina, Simulations Plus, Genedata, Chemical Computing Group, Insilico Medicine, Instem
Valuation Currency USD Billion, end-user value
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst attributions and are not additive components of the reported CAGR

FAQs

How should buyers structure procurement contracts in the Computational Biology Market?
Tie payment to validated deliverables rather than seat counts. Include data-portability clauses and audit-trail requirements upfront, since regulatory qualification makes platform migration costly later [11].
What integration challenges most often derail deployments?
Connector development between legacy laboratory information systems and modern analysis pipelines consumes the largest share of overrun budgets. Insist that vendors demonstrate live integration with your existing repositories before contract signature [12].
Do open-source tools compete meaningfully with commercial platforms?
Yes for exploratory research, rarely for regulatory submissions. Commercial vendors sell validation documentation and support liability, which open-source projects cannot provide [14].
Which insurance and liability issues apply to computational evidence?
Sponsors retain full regulatory liability for model outputs regardless of vendor. Negotiate indemnification for software defects, and verify the vendor maintains version-locked archives of any model used in a submission [1].
How does the Computational Biology Market differ for agricultural versus pharmaceutical buyers?
Agricultural users prioritise throughput on large population datasets at low per-sample cost. Pharmaceutical buyers pay premiums for regulatory traceability instead [19].
What skills should an internal team have before licensing an enterprise platform?
At minimum, one workflow engineer and one domain scientist who can interpret model uncertainty. Without both, organisations under-use expensive licences [13].
Is vendor lock-in a material risk in the Computational Biology Market?
Considerable, particularly where proprietary data formats and qualified model states are involved. Require export in open standards as a contractual condition [12].      
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed scientific journals, computational biology publications, and authoritative health and technology organizations. Key sources included the US National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), US Food & Drug Administration (FDA), European Medicines Agency (EMA), European Bioinformatics Institute (EMBL-EBI), National Institute of Standards and Technology (NIST), International Society for Computational Biology (ISCB), American Association for the Advancement of Science (AAAS), American Chemical Society (ACS), Centers for Disease Control and Prevention (CDC), World Health Organization (WHO) Global Health Observatory, OECD Science and Technology Indicators, EU Eurostat R&D Statistics, National Science Foundation (NSF) Science & Engineering Indicators, and national bioinformatics infrastructure reports from key markets. These sources were used to collect technology adoption statistics, regulatory approval data for AI-driven drug discovery platforms, clinical validation studies, R&D investment trends, and market landscape analysis for bioinformatics software, computational genomics platforms, molecular modeling tools, and cloud-based biological data analysis solutions.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Product Development, heads of computational biology departments, and regulatory affairs leaders from cloud computing platform developers, pharmaceutical technology suppliers, and bioinformatics software vendors were examples of supply-side sources. Chief Scientific Officers, heads of bioinformatics, computational biologists, research directors from biotechnology and pharmaceutical companies, principal investigators from academic institutions and research organizations, and procurement leads from biopharma R&D centers were examples of demand-side sources. Primary research confirmed AI algorithm development pipelines and platform deployment timelines, validated market segmentation across application areas (drug discovery, genomics, proteomics, metabolomics, systems biology), and collected data on cloud migration strategies, software licensing models, technology adoption patterns, and research funding dynamics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and platform deployment analysis. The methodology included:

Identification of 50+ key technology providers and platform developers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across bioinformatics software, computational genomics platforms, computational proteomics tools, molecular modeling solutions, and other technology categories

Analysis of reported and modeled annual revenues specific to computational biology portfolios, including software licenses, cloud subscriptions, and professional services

Coverage of technology providers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (platform deployment volume × ASP by country/institution type) and top-down (vendor revenue validation) approaches to derive segment-specific valuations across drug discovery, genomics, proteomics, metabolomics, and systems biology applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















