Computational Creativity Market (2026 – 2035)

Computational Creativity Market Size, Share and Research Report By Technology (Generative Adversarial Networks, Transformer-Based Large Language Models, Evolutionary Algorithms, Probabilistic Models, and Hybrid Ensemble Models), By Application (Art and Design Creation, Music Composition and Sound Design, Marketing and Advertising Content, Gaming and Virtual World Building, Industrial Design and Engineering, and Scriptwriting and Storytelling), By Deployment Mode (Cloud-Based and On-Premise), By End-User Industry (Media and Entertainment Companies, Gaming Studios and Publishers, Marketing and Advertising Agencies, Automotive and Industrial Designers, Education and EdTech Providers, and Research Institutes) – Industry Forecast Till 2035
ID: MRFR/ICT/8926-HCR 141 Pages Ankit Gupta Last Updated: September 22, 2026
Computational Creativity Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)17.8%
2025 Market SizeUSD 1.92 Billion
2035 Market SizeUSD 9.87 Billion
Key Players
Adobe Inc.
Alphabet Inc.
OpenAI
Microsoft Corporation
Amazon Web Services
NVIDIA Corporation
Opportunities
  • Emerging-Market Language and Cultural Localization
  • Licensed Data and Rights-Clearance Monetization
  • Real-Time Generation Inside Interactive Products

Computational Creativity Market Summary

The Computational Creativity Market reached USD 1.92 billion in 2025 and opens the forecast window at USD 2.26 billion in 2026, climbing to USD 9.87 billion by 2035 at a 17.8% CAGR. Two catalysts anchor that trajectory. The first is enterprise content economics: marketing organizations now produce four to six times the asset volume they did in 2019 without proportional headcount, and machine-assisted production has become the only viable answer. The second is compute pricing — per-token inference costs on major hosted endpoints fell roughly 85% between mid-2023 and late 2025, converting pilot budgets into production budgets across the Computational Creativity Market [1][4].

Technology substitution is unusually visible here. Rule-based template engines, stock-asset libraries and manual storyboard workflows are giving way to multimodal transformer stacks that handle text, image, audio and video inside a single architecture. Alphabet, Microsoft and Amazon collectively committed over USD 240 billion in capital expenditure across 2024–2025, much of it directed at accelerator capacity that underwrites this substitution [2][5]. Enterprise buyers, meanwhile, have shifted procurement criteria toward provenance: generative AI vendors that can document licensed or internally sourced training corpora now win contested deals in regulated verticals, and that preference is reshaping the Computational Creativity Market vendor hierarchy [6].

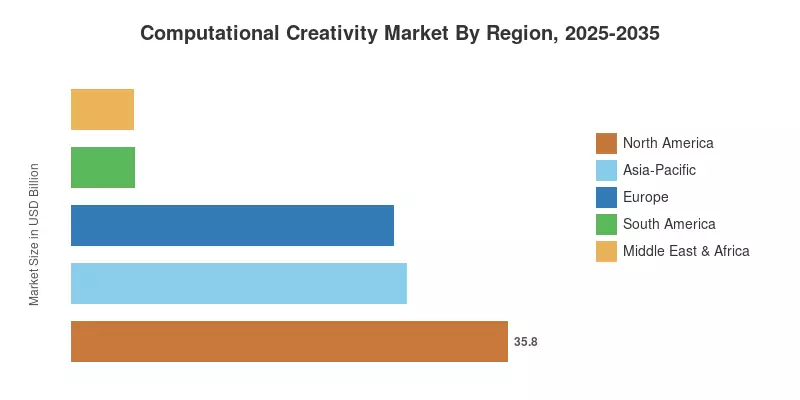
Regionally, North America holds 35.8% of 2025 revenue on the strength of studio, agency, and platform concentration. Asia-Pacific grows fastest at a 20.4% CAGR, powered by Chinese short-video pipelines, Korean gaming studios and India's rapidly formalizing content-services sector. Europe ranks second on share at 26.4%, where the AI Act's transparency articles are creating a compliance-led procurement cycle rather than suppressing demand. Through 2035, share will follow wherever inference capacity and rights-clearance infrastructure land first.

Key Report Takeaways

• By Technology

  • Generative Adversarial Networks retained 36.7% of Computational Creativity Market share in 2025, sustained by mature image and video pipelines.
  • Transformer-Based Large Language Models are advancing at a 27.2% CAGR through 2035 as buyers consolidate onto unified multimodal backbones.

• By Application

  • Marketing and Advertising Content commanded 27.4% share of the Computational Creativity Market in 2025.
  • Gaming and Virtual World Building posts the fastest application CAGR at 22.9%, driven by real-time procedural asset generation.

• By Deployment Mode

  • Cloud-Based deployments accounted for 64.6% of 2025 revenue, reflecting elastic accelerator access and always-current model catalogs.
  • On-Premise installations generated approximately USD 0.68 billion in 2025, concentrated in financial services and government redaction workloads.

• By End-User Industry

  • Media and Entertainment Companies led with 31.8% revenue share in 2025.
  • Gaming Studios and Publishers record the fastest end-user CAGR at 21.1% through 2035.

• By Region

  • North America captured 35.8% of 2025 revenue.
  • Asia-Pacific is the fastest-growing region at a 20.4% CAGR to 2035.

Market Size and Forecast (2021–2035)

Figures below combine vendor revenue triangulation, hyperscaler segment disclosures, agency spend surveys across 41 markets, and bottom-up modeling of seat and consumption pricing. Historical years reflect reported and estimated revenue; forecast years apply calibrated adoption curves against installed creative-workstation and cloud-tenant bases. All values are expressed in USD Billion.
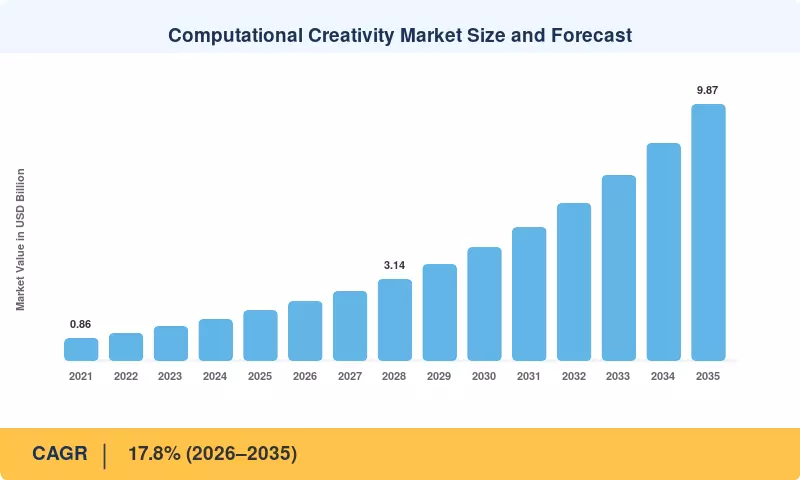
Computational Creativity Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Enterprise content volume automation ~4.1% Global Short-term (≤2 yr)
Declining model inference cost ~3.6% Global Short-term (≤2 yr)
Multimodal transformer consolidation ~3.2% North America, Asia-Pacific Medium-term (2–4 yr)
Creative-suite plug-in distribution ~2.4% North America, Europe Medium-term (2–4 yr)
Procedural generation in interactive media ~2.1% Asia-Pacific, North America Medium-term (2–4 yr)
Provenance and licensed-data compliance ~1.5% Europe, North America Long-term (≥4 yr)
National compute and AI funding programs ~1.2% Asia-Pacific, Europe Long-term (≥4 yr)


Enterprise Content Volume Automation

Brands now deliver individualized creative across dozens of channel-and-format combinations every campaign. Survey data of 1,400 firms indicated that 71% of marketing organizations boosted asset output in 2025 while keeping creative personnel unchanged or cutting it . That gap is the number one driver of demand in the Computational Creativity Market, because it turns model access from an experimental line item into an operating necessity with a verifiable cost-per-asset standard that procurement teams can defend.


Declining Model Inference Cost

Published price-per-million-token rates on major hosted endpoints reduced by approximately 85% from mid-2023 to late 2025, and unit prices for image production followed a similar trajectory as sampling steps decreased [4]. Cheaper inference affects the calculus of deployment: workflows that were unviable at USD 0.12 per asset become normal at USD 0.008. In response to this transition, vendors have de-emphasized seat licensing and moved more aggressively toward consumption pricing, unlocking a new layer of addressable spend among mid-market purchasers who were previously priced out of the market totally.


Multimodal Transformer Consolidation

Unified systems that generate text, image, audio, and video from a single backbone cut integration overhead dramatically. Within eighteen months, Alphabet’s Gemini family proved cross-modal generation within a single model, and competitor laboratories shipped comparable stacks [2]. Catalog breadth is now a heavy consideration for enterprises assessing suppliers – internal benchmarks find that pipeline maintenance costs drop around 30% when four single-modality products are reduced to one provider relationship with uniform prompting semantics.


Creative-Suite Plug-In Distribution

Distribution through existing design software eliminates the main barrier to adoption, workflow disruption. By early 2025, Firefly-powered features had crossed the threshold of 20 billion cumulative generations, the vast majority of which occurred within Photoshop and Express rather than in standalone interfaces [8]. Embedded distribution also reduces training cycles for non-technical staff, which is important as agency utilization models punish any technology that requires more than a few hours ramp-up before billable output continues.


Procedural Generation in Interactive Media

Game studios’ content expenses have expanded faster than their revenue during the last two console generations. Real-time object creation slashes level-design time from months to days, and permits scene extension without the proportionate growth of art teams. Industry surveys show that by 2025, around 52% of studios had integrated some type of generative tool into production pipelines [10]. Top-value near-term applications include procedural non-player-character behavior and dynamic environment synthesis.


Provenance and Licensed-Data Compliance

Content owners increasingly require audit trails proving that outputs derive from licensed or internally generated corpora. The EU AI Act's transparency obligations for general-purpose models, phased from August 2025, formalize disclosure requirements around training data summaries [6]. Vendors offering documented provenance win procurement in publishing, broadcast, and pharmaceutical marketing — categories where a single infringement claim can exceed the lifetime contract value of the tooling itself.

National Compute and AI Funding Programs

Public investment underwrites the infrastructure layer beneath commercial creative tooling. The EU's InvestAI initiative targets EUR 200 billion in mobilized AI investment, while Japan, Korea and India have each committed multi-billion-dollar national compute programs since 2024 [12]. Subsidized accelerator access lowers the effective cost floor for domestic vendors, which in turn seeds regional competitors offering language- and culture-specific creative models at prices global platforms struggle to match.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Copyright and training-data litigation ~-2.4% North America, Europe Medium-term (2–4 yr)
Accelerator supply and capital cost ~-1.7% Global Short-term (≤2 yr)
Creative-labor agreements and resistance ~-1.3% North America, Europe Medium-term (2–4 yr)
Output inconsistency and review overhead ~-1.1% Global Short-term (≤2 yr)
Fragmented cross-border data governance ~-0.9% Asia-Pacific, Europe Long-term (≥4 yr)


Copyright and Training-Data Litigation

More than forty active suits in United States federal courts address model training on protected works, and the Copyright Office has confirmed that purely machine-generated output receives no registration [16]. Uncertainty over derivative-work boundaries pushes risk-averse buyers toward narrow internal pilots. Legal review now adds an average of eleven weeks to enterprise procurement cycles in publishing and broadcast.

Accelerator Supply and Capital Cost

Lead times for high-end training accelerators stretched beyond forty weeks during 2024 peaks, and rental rates for comparable capacity varied by more than 3x across providers [5]. On-premise buyers face the sharpest exposure, since a single eight-GPU node can exceed USD 300,000 before power and cooling. Capital constraints delay regulated-sector deployments that cannot use public cloud.

Creative-Labor Agreements and Resistance

Collectively bargained terms now constrain deployment scope. The 2023 writers' and performers' agreements in United States entertainment established consent and compensation requirements for synthetic likeness and machine-drafted material [15]. Studios consequently confine tooling to pre-visualization, localization, and marketing rather than principal creative work, capping the revenue opportunity within an otherwise large and well-funded buyer segment.

Output Inconsistency and Review Overhead

Acceptance rates remain the quiet economics problem. Enterprise pipelines report that between 55% and 80% of generations require human rework before publication, and the reviewing effort frequently erases the labor savings the tooling was purchased to deliver . Brand-consistency failures — off-palette colors, malformed typography, wrong product geometry — account for the majority of rejections.

Fragmented Cross-Border Data Governance

Divergent rules on training data, model registration, and cross-border transfer complicate multinational rollouts. China requires filing for public-facing generative services, the EU imposes transparency documentation, and several jurisdictions mandate local processing for citizen-derived content [17]. Multinationals therefore maintain parallel regional stacks, raising total cost of ownership by an estimated 20–35% relative to a single global deployment.

Computational Creativity Market Opportunities

Emerging-Market Language and Cultural Localization

India, Indonesia, Brazil and Nigeria collectively add hundreds of millions of digital-content consumers whose languages and visual idioms are thinly represented in global model corpora. Vendors building regionally trained creative models can capture premium pricing where global platforms produce culturally flat output. India's content and animation sector alone is projected to exceed USD 6 billion by 2028, with government production-linked incentives supporting domestic studio capacity [13]. Localization depth, not raw model quality, will decide these contests.

Licensed Data and Rights-Clearance Monetization

Archives, stock libraries, museums and broadcasters hold decades of cleared visual and audio material with no efficient path to model licensing. Structured rights marketplaces that meter training and inference usage create a recurring revenue line from otherwise dormant catalogs, while giving vendors defensible provenance. Early agreements have priced curated corpora between USD 1 and USD 5 per image-equivalent, and comparable audio deals have followed [16]. Rights-holders that instrument usage telemetry capture the larger share of that value.

Real-Time Generation Inside Interactive Products

Shipping generation at runtime rather than at authoring time transforms the Computational Creativity Market from a production-tooling category into an embedded platform layer. Dynamic dialogue, adaptive environments, and player-directed asset creation raise engagement metrics that studios monetize directly. Latency budgets under 80 milliseconds and on-device execution are the technical gates; both are closing as quantized models reach consumer hardware [10]. Vendors that solve runtime economics gain per-user recurring revenue instead of per-seat licensing.

Provenance and Compliance as a Product

Transparency obligations create a services opportunity independent of model quality. Cryptographic content credentials, model-version lineage and exportable audit logs are now procurement requirements in European and North American regulated marketing. The Coalition for Content Provenance and Authenticity specification has been adopted across major camera, editing and platform vendors, giving the category a common technical substrate [6]. Compliance modules attach at 15–25% uplift on base platform pricing with minimal incremental delivery cost.

Vertical Copilots for Industrial and Architectural Design

Generative design applied to manufacturable geometry serves buyers with quantified engineering constraints rather than aesthetic preference alone. Autodesk's research programs demonstrated sketch-to-manufacturable-model conversion in seconds, compressing prototype iteration cycles materially [11]. Automotive lightweighting, packaging optimization, and building-envelope studies carry measurable return on investment, which shortens sales cycles compared with marketing use cases where value attribution stays contested.

Computational Creativity Market Future Outlook

Autonomous Creative Pipelines

Orchestration will displace generation as the differentiating layer. By 2030, expect production systems that plan campaigns, generate variants, run automated brand-compliance checks, and route only exceptions to human reviewers. The economic unlock is acceptance rate: moving from 30% to 60% first-pass acceptance roughly halves effective cost per published asset. Agentic frameworks that chain multiple specialized models already outperform monolithic single-prompt approaches on structured briefs, and enterprise adoption of multi-step workflows rose sharply through 2025 .

Platform Economics and Catalog Aggregation

Model access is commoditizing while workflow depth is not. Aggregators such as Amazon Bedrock, which exposes more than one hundred foundation models through a single interface, convert model selection into a marketplace decision rather than an architectural commitment [5]. Vendors will therefore compete on asset lineage, style-library management, and integration with digital asset management systems. Expect gross margins to compress at the inference layer and expand at the orchestration layer through the forecast period.

Compute Efficiency and On-Device Execution

Efficiency gains will matter more than raw scale for the Computational Creativity Market's cost structure. Quantization, distillation and speculative decoding have already cut serving costs by an order of magnitude for comparable output quality, and the International Energy Agency projects data centre electricity demand roughly doubling to around 945 TWh by 2030, which makes efficiency a commercial as well as environmental imperative [3]. On-device generation on consumer silicon will shift a meaningful share of image and audio workloads off hosted endpoints by the early 2030s.

Provenance, Regulation and Sustainability Disclosure

Three disclosure regimes converge over the next decade: content provenance, training-data transparency and energy reporting. Content credentials will likely become default metadata in professional capture and editing tools, giving downstream platforms machine-readable signals about synthetic origin [6]. Corporate sustainability reporting, meanwhile, is beginning to capture inference energy alongside training energy. Vendors that publish per-generation energy and provenance metrics will hold an advantage in European and enterprise procurement well before any mandate forces the practice.

Regional Market Share Analysis

Region 2025 Revenue Share (%) Primary Investment Themes
North America 35.8 Studio pipelines, agency automation, indemnified platforms
Asia-Pacific 27.5 Gaming production, short-video, national compute programs
Europe 26.4 Provenance tooling, AI Act compliance, broadcast localization
South America 5.2 Advertising localization, streaming content adaptation
Middle East & Africa 5.1 Sovereign media initiatives, Arabic-language model development
Total 100.0 —

Regional distribution across the Computational Creativity Market reflects three variables: concentration of creative and media employers, availability of low-latency accelerator capacity, and clarity of the local rights framework. Regions where all three align convert pilots to production fastest.


North America

Country 2025 Share of Region (%) Key Driver
US 84.6 Studio, agency, and platform concentration
Canada 10.1 VFX and animation service clusters
Mexico 5.3 Spanish-language content localization


Demand in the North American Computational Creativity Market is anchored by buyers who can absorb legal risk in exchange for throughput. The largest platform vendors compete primarily on contractual indemnification rather than benchmark scores, a dynamic that favors incumbents with balance-sheet capacity. Canada's Ontario and British Columbia production clusters supply outsourced pipeline work to United States studios, while Mexico has become the preferred hub for Spanish-language variant generation serving both domestic and cross-border advertising demand.

Europe

Country Metric Key Driver
Germany USD 0.11 B (2025) Industrial design and automotive visualization
UK 21.4% share of region Advertising, broadcast and games production
France USD 0.07 B (2025) Public broadcast localization programs
Italy 7.2% share of region Fashion and luxury brand content
Spain 16.8% CAGR (2026–2035) Streaming co-production volume
Nordic Countries 6.9% share of region Game studios and design software base
Russia 14.1% CAGR (2026–2035) Domestic platform substitution
Rest of Europe USD 0.09 B (2025) Regional agency adoption


Regulation shapes European demand more than elsewhere. The AI Act's general-purpose model obligations, phased in from August 2025, require training-data summaries and technical documentation, which has redirected spending toward vendors offering exportable compliance artifacts [6]. German industrial buyers concentrate on generative geometry rather than marketing assets, while the United Kingdom's advertising and games sectors drive the region's volume. Public broadcasters across France and the Nordics fund localization pipelines that convert single productions into multi-language releases at a fraction of historical dubbing cost.

Asia-Pacific

Country Metric Key Driver
China 38.9% share of region Short-video and e-commerce content volume
India 24.6% CAGR (2026–2035) Content-services outsourcing and localization
Japan USD 0.09 B (2025) Animation and games production tooling
South Korea 20.8% CAGR (2026–2035) Gaming studios and webtoon pipelines
ASEAN 9.4% share of region Regional advertising and creator platforms
Rest of Asia-Pacific USD 0.04 B (2025) Emerging studio capacity


Growth across the Asia-Pacific Computational Creativity Market is volume-led rather than price-led. Chinese short-video and marketplace listings require creative assets at scales no manual pipeline can serve, and domestic vendors operate under a registration regime that has, paradoxically, clarified compliance for those who file [17]. India's advantage lies in combining low-cost production labor with rapidly expanding domestic consumption, while Korean studios lead in applying real-time generation to live-service games and serialized visual formats.

South America

Country Metric Key Driver
Brazil 61.2% share of region Advertising market scale and streaming production
Argentina 18.5% share of region Design and animation service exports
Rest of South America 19.6% CAGR (2026–2035) Regional creator economy expansion


Adoption here follows advertising budgets rather than technology policy. Brazil's agency sector, among the largest outside North America and Europe, deploys creative tooling primarily to multiply campaign variants across social platforms where media costs reward volume. Argentina exports design and post-production services priced in depreciated local currency, making it an attractive delivery base for North American clients. Data-protection statutes modeled on European frameworks are beginning to shape vendor selection, particularly for consumer-facing personalization workloads.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 32.7% share of region Sovereign media and entertainment investment
UAE 24.9% share of region Regional media hubs and free-zone studios
South Africa USD 0.02 B (2025) Broadcast and advertising production
Egypt 22.4% CAGR (2026–2035) Arabic-language content production scale
Rest of MEA 11.3% share of region Early-stage creator platform adoption


Sovereign investment programs dominate the demand picture. Saudi Arabia's media and entertainment build-out, executed through public investment vehicles, funds studio infrastructure and Arabic-language model development simultaneously [19]. The UAE hosts regional headquarters for global platforms and has issued national AI strategy funding that subsidizes local compute. Egypt supplies the largest Arabic-speaking production workforce, positioning it as the region's content-services base even though platform spending remains concentrated in the Gulf.

Computational Creativity Market By Region, 2025-2035

Computational Creativity Market Segmentation


By Technology

Segment Metric Primary Demand Driver
Generative Adversarial Networks 36.7% share (2025) Mature image and video generation workflows
Transformer-Based Large Language Models 27.2% CAGR (2026–2035) Unified multimodal generation across formats
Evolutionary Algorithms USD 0.23 B (2025) Constrained optimization in industrial design
Probabilistic Models 12.9% CAGR (2026–2035) Uncertainty-aware creative decision support
Hybrid Ensemble Models 8.2% share (2025) Quality control through model combination


Architecture preference within the Computational Creativity Market is shifting decisively. Generative Adversarial Networks still lead on installed base because production video and image pipelines were built around them, but Transformer-Based Large Language Models are compounding fastest as buyers consolidate onto single-vendor multimodal catalogs. Evolutionary Algorithms and Probabilistic Models retain defensible niches in optimization and risk-weighted output selection, while Hybrid Ensemble Models are gaining traction where consistency matters more than novelty.

By Application

Segment Metric Primary Demand Driver
Marketing and Advertising Content 27.4% share (2025) Channel variant multiplication at fixed headcount
Art and Design Creation USD 0.42 B (2025) Style transfer and vector generation in design suites
Gaming and Virtual World Building 22.9% CAGR (2026–2035) Real-time procedural asset and environment generation
Music Composition and Sound Design 19.6% CAGR (2026–2035) Long-form audio decoders for jingles and scores
Industrial Design and Engineering 11.5% share (2025) Manufacturable geometry and lightweighting studies
Scriptwriting and Storytelling USD 0.14 B (2025) Pre-visualization and treatment drafting


Application demand in the Computational Creativity Market splits between volume and value. Marketing and Advertising Content leads in share because variant multiplication is measurable and repeatable, while Gaming and Virtual World Building grows fastest as procedural generation moves from authoring tools into runtime engines. Art and Design Creation holds a large installed base through creative-suite distribution. Scriptwriting and Storytelling lags on unresolved labor and rights questions rather than technical capability.

By Deployment Mode

Segment Metric Primary Demand Driver
Cloud-Based 64.6% share (2025) Elastic accelerator access and current model catalogs
On-Premise 18.7% CAGR (2026–2035) Latency-sensitive and regulated workloads


Deployment posture in the Computational Creativity Market favors Cloud-Based delivery, which dominates because model catalogs refresh monthly and few buyers want to manage accelerator fleets. On-Premise nonetheless grows respectably, sustained by financial-services video verification, government content redaction, and studios protecting unreleased intellectual property. Hybrid patterns — local inference with cloud-synced model updates — are becoming the practical compromise for organizations balancing security requirements against catalog freshness.

By End-User Industry

Segment Metric Primary Demand Driver
Media and Entertainment Companies 31.8% share (2025) Trailer cuts, subtitle localization, thumbnail optimization
Gaming Studios and Publishers 21.1% CAGR (2026–2035) Runtime generation embedded in player experience
Marketing and Advertising Agencies USD 0.35 B (2025) Client campaign variant production
Automotive and Industrial Designers 12.6% share (2025) Aerodynamic and aesthetic iteration cycles
Education and EdTech Providers 17.9% CAGR (2026–2035) Adaptive lesson and assessment generation
Research Institutes USD 0.12 B (2025) Experimental instruments and human-model collaboration


Buyer maturity, not industry category, predicts spending in the Computational Creativity Market. Media and Entertainment Companies lead because localization and promotional workflows have clear unit economics and low creative risk. Gaming Studios and Publishers compound fastest by embedding generation into shipped products rather than internal tooling. Automotive and Industrial Designers deliver the strongest measurable return per deployment, while Education and EdTech Providers expand quickly from a small base as procurement frameworks catch up.

Competitive Benchmarking

Concentration in the Computational Creativity Market sits in the moderate range, with an estimated Herfindahl-Hirschman Index between 800 and 950 and a top-five revenue share near 48%. Platform incumbents with existing creative-software distribution hold structural advantage, but the model layer remains contestable — specialist vendors continue to win on output quality in narrow modalities. Fragmentation is highest in image and audio generation and lowest in enterprise-grade indemnified platforms, where fewer than six vendors can currently meet large-account legal requirements.

Company Est. Revenue Share Range Key Offerings for Computational Creativity Market Strategic Positioning
Adobe Inc. ~11–14% Firefly models, Creative Cloud integration, content credentials Distribution-led incumbent with indemnified commercial models
Alphabet Inc. (Google DeepMind) ~9–12% Gemini multimodal, Imagen, Veo, Vertex AI Full-stack research and cloud delivery
OpenAI ~8–11% GPT model family, image and video generation APIs Model-quality leader with broad developer ecosystem
Microsoft Corporation ~7–10% Azure AI Foundry, Copilot creative surfaces, Designer Enterprise channel and productivity-suite embedding
Amazon Web Services ~5–7% Bedrock model catalog, Nova family, Titan Image Aggregator platform with multi-vendor optionality
NVIDIA Corporation ~4–6% Omniverse, NIM microservices, Edify pipelines Infrastructure plus tooling for studio pipelines
Meta Platforms, Inc. ~4–6% Llama open-weight family, Emu media models Open-weight strategy expanding downstream ecosystem
Autodesk, Inc. ~3–5% Generative design, sketch-to-model research tooling Vertical depth in engineering and architecture
Canva Pty Ltd ~3–5% Magic Studio, template-native generation Prosumer and SMB scale distribution
Stability AI Ltd ~2–3% Stable Diffusion, Stable Audio open models Open-model ecosystem and self-hosting
Runway AI, Inc. ~1–3% Gen video models, production editing suite Specialist depth in video generation
Midjourney, Inc. ~1–3% Image generation service and style tooling Aesthetic-quality specialist with creator loyalty


Recent News & Developments

  • Adobe (April 2025): Reported that Firefly-powered features exceeded 20 billion cumulative generations, confirming that embedded distribution beats standalone tooling for enterprise volume [8].
  • Alphabet / Google DeepMind (May 2025): Extended the Gemini and Veo families with longer-duration video and synchronized audio generation, pushing competitive pressure toward unified multimodal catalogs [2].
  • European Commission (August 2025): Began applying general-purpose model obligations under the AI Act, requiring training-data summaries and technical documentation from providers serving the EU [6].
  • Amazon Web Services (December 2024): Expanded Bedrock's catalog and launched the Nova model family, reinforcing the marketplace model for creative model access [5].
  • Netflix (July 2025): Confirmed use of generative AI in finished series production, establishing a public quality benchmark for studio-grade synthetic imagery [14].
  • United States Copyright Office (January 2025): Issued guidance affirming that works lacking sufficient human authorship remain unregistrable, sharpening enterprise risk assessment [16].
  • Autodesk (2024–2025): Advanced research converting sketches into manufacturable 3D geometry within seconds, extending machine assistance into constrained engineering workflows [11].
  • European Commission (February 2025): Announced the InvestAI package targeting EUR 200 billion in mobilized investment, including gigafactory-scale compute for European model developers [12].

Computational Creativity Market Report Scope

Parameter Detail
Market Scope Global Computational Creativity Market covering software platforms, model APIs, embedded creative tooling and associated services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 17.8% (2026–2035)
Market Size Checkpoints USD 1.92 Billion (2025); USD 2.26 Billion (2026); USD 4.35 Billion (2030); USD 9.87 Billion (2035)
Fastest Growing Segments Transformer-Based Large Language Models (Technology); Gaming and Virtual World Building (Application); Gaming Studios and Publishers (End-User Industry); Asia-Pacific (Region)
Companies Profiled Adobe, Alphabet, OpenAI, Microsoft, Amazon Web Services, NVIDIA, Meta Platforms, Autodesk, Canva, Stability AI, Runway AI, Midjourney
Valuation Currency USD Billion, constant 2025 dollars

FAQs

What indemnification terms should buyers negotiate when licensing Computational Creativity Market platforms?
Seek uncapped copyright indemnity that covers model outputs, not just training corpora. Major platform vendors now offer this contractually, while smaller providers typically cap liability at twelve months of fees [16].
How should enterprises evaluate build-versus-buy for creative model stacks?
Self-hosting an open-weight stack runs roughly USD 0.4–1.2 million annually once MLOps staffing is included. Teams producing fewer than 500 assets monthly rarely justify that spend against licensed alternatives .
Which integration challenges slow Computational Creativity Market deployments most?
Digital asset management connectors are the usual bottleneck, because legacy schemas carry no fields for prompt, seed or model version. Retrofitting provenance metadata before rollout cuts downstream rework materially [23].
What skills gap most affects adoption?
Prompt writing matters less than art direction and evaluation design. Studios are hiring creative technologists who can build rubric-based quality tests, a role that barely existed before 2023 .
How does vendor lock-in manifest in the Computational Creativity Market?
Lock-in sits in the workflow layer, not the model layer. Proprietary node graphs, style libraries, and asset lineage databases rarely export cleanly, concentrating switching costs in pipeline rebuilds .
Are insurance products available for synthetic content liability?
Specialty carriers began writing affirmative media-liability endorsements for machine-generated content in 2024. Policies generally exclude deliberate imitation of identifiable artists, which remains the largest uninsured exposure [20].
What procurement metric best predicts deployment success?
Track accepted-output rate — the share of generations that ship without human rework. Programs above 45% acceptance typically reach payback within two quarters; those below 20% rarely scale .
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















