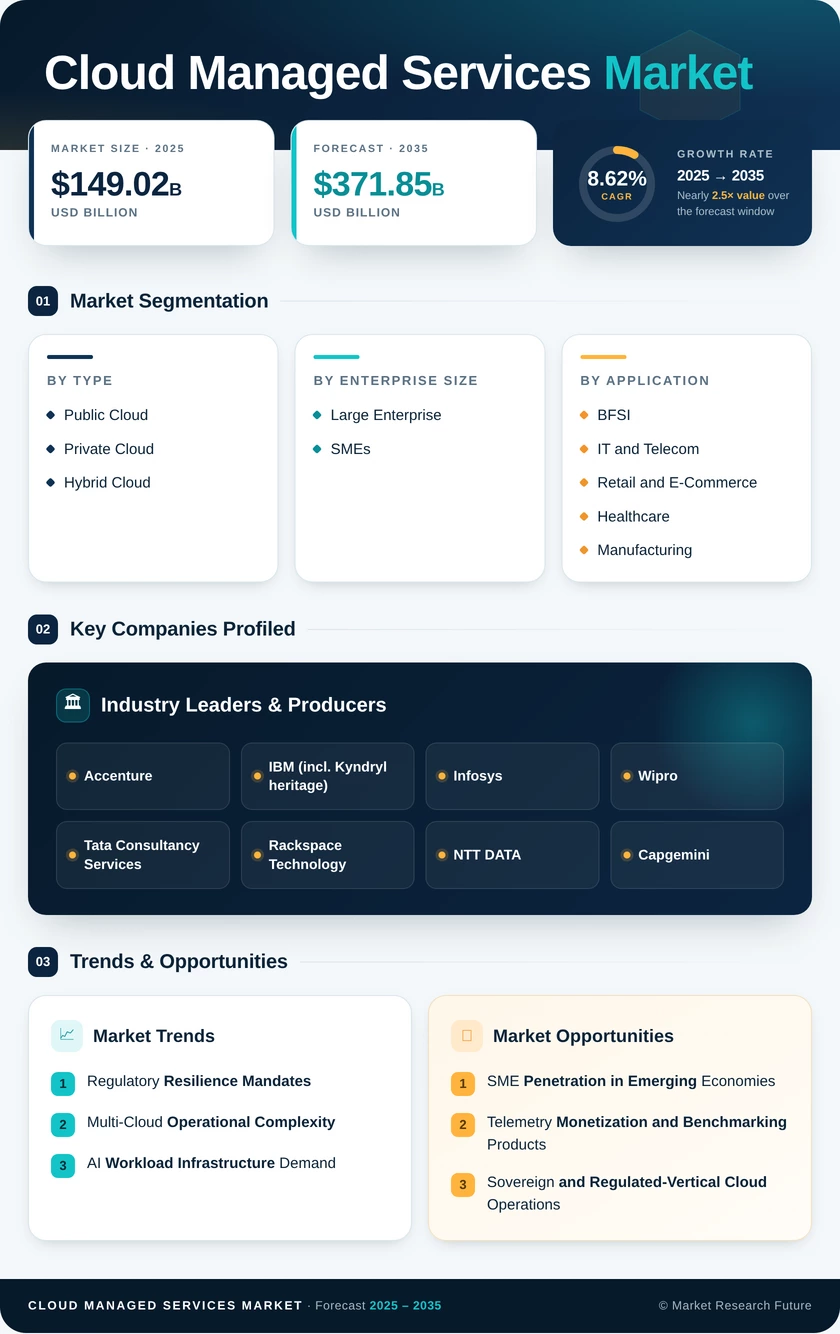
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Service Type | Managed Infrastructure Services; Managed Network Services; Managed Security Services; Managed Mobility Services; Other Service Types | Managed Infrastructure Services | Managed Security Services |
| By Deployment Type | Public Cloud; Private Cloud; Hybrid Cloud | Public Cloud | Hybrid Cloud |
| By Enterprise Size | Large Enterprise; SMEs | Large Enterprise | SMEs |
| By End User Industry | BFSI; IT and Telecom; Retail and E-Commerce; Healthcare; Manufacturing; Other End Users | BFSI | Retail and E-Commerce |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Service Type
| Sub-Segment | Key Trend |
| Managed Infrastructure Services | Consolidation of compute, storage and identity operations under single control planes |
| Managed Network Services | SD-WAN and cloud interconnect management absorbed into cloud operations scope |
| Managed Security Services | Shift of breach liability to contracted operators with 24/7 detection duties |
| Managed Mobility Services | Endpoint and device fleet operations converging with zero-trust access policy |
| Other Service Types | Application, database and data-pipeline operations moving up the value stack |
Service-type demand is migrating upward. Infrastructure work remains the revenue anchor, but growth now concentrates where accountability sits — security and application operations — because those are the areas boards cannot delegate internally without staffing they cannot hire.
By Deployment Type
| Sub-Segment | Key Trend |
| Public Cloud | Hyperscaler-native tooling raises the baseline, pushing providers toward multi-platform value |
| Private Cloud | Sustained by residency, latency, and regulated-workload requirements |
| Hybrid Cloud | Fastest growth as enterprises accept permanent estate coexistence |
Hybrid is not a transitional state anymore. Most large enterprises now plan for indefinite coexistence between on-premises and public estates, and the operational seam between them is where technical difficulty and pricing power concentrate.
By Enterprise Size
| Sub-Segment | Key Trend |
| Large Enterprise | Multi-region governance, consolidated vendor panels, outcome-based contracting |
| SMEs | Packaged low-touch tiers with automated onboarding open volume channels |
Large enterprises supply the revenue base while SMEs supply the growth rate. Serving the latter profitably requires standardization that most incumbent providers have not yet industrialised, leaving room for platform-native challengers.
By End User Industry
| Sub-Segment | Key Trend |
| BFSI | Resilience regulation converts governance overhead into contracted service scope |
| IT and Telecom | Network function virtualization and edge estate management expand scope |
| Retail and E-Commerce | Seasonal elasticity choreography outsourced rather than staffed year-round |
| Healthcare | Clinical data compliance drives private and hybrid deployment preference |
| Manufacturing | Industrial IoT pipelines require OT-aware, passive monitoring approaches |
| Other End Users | Public sector and education adopt framework-based procurement models |
Vertical specialization is now the primary differentiator. Providers who understand a sector's regulatory calendar and data model win renewals at materially higher rates than generalists competing on availability metrics alone.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA