Cloud Managed Services Market (2026 - 2035)

Cloud Managed Services Market Size, Share and Research Report By Margin Compression from Automation, By Data Sovereignty Fragmentation, By In-House Platform Team Insourcing, By Hyperscaler First-Party Service Expansion, By SLA Attribution Disputes and By Regional (North America, Europe, South America, South Africa, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/4068-HCR 100 Pages Ankit Gupta Last Updated: September 15, 2026
Cloud Managed Services Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.62%
2025 Market SizeUSD 149.02 Billion
2035 Market SizeUSD 371.85 Billion
Key Players
Accenture
IBM
Infosys
Wipro
Tata Consultancy Services
Rackspace Technology
Opportunities
  • SME Penetration in Emerging Economies
  • Telemetry Monetization and Benchmarking Products
  • Sovereign and Regulated-Vertical Cloud Operations

Cloud Managed Services Market Summary


The Cloud Managed Services Market closed 2025 at USD 149.02 billion and enters the forecast window at USD 161.83 billion in 2026, climbing to USD 371.85 billion by 2035 at an 8.62% CAGR. Two catalysts anchor that trajectory. The U.S. Federal Risk and Authorization Management Program (FedRAMP) modernization roadmap, formalized in 2024, pushed agencies toward authorized third-party operators [1]. In parallel, the European Union's Digital Operational Resilience Act (DORA), applicable from January 2025, made continuous third-party ICT oversight a legal obligation for roughly 22,000 financial entities [2]. Both moves converted managed cloud from a cost lever into a compliance instrument, and the Cloud Managed Services Market absorbed that shift quickly.

Underneath the headline number sits a replacement cycle. Enterprises are retiring on-premises virtualization estates, ticket-driven NOC models and manual patch cycles, swapping them for policy-as-code control planes, AIOps-driven remediation and FinOps telemetry. pegged worldwide IT services spending above USD 1.6 trillion in 2025, with outsourced cloud operations the fastest-moving line item [3]. The Cloud Managed Services Market captures the operational tail of that migration rather than the raw compute bill.

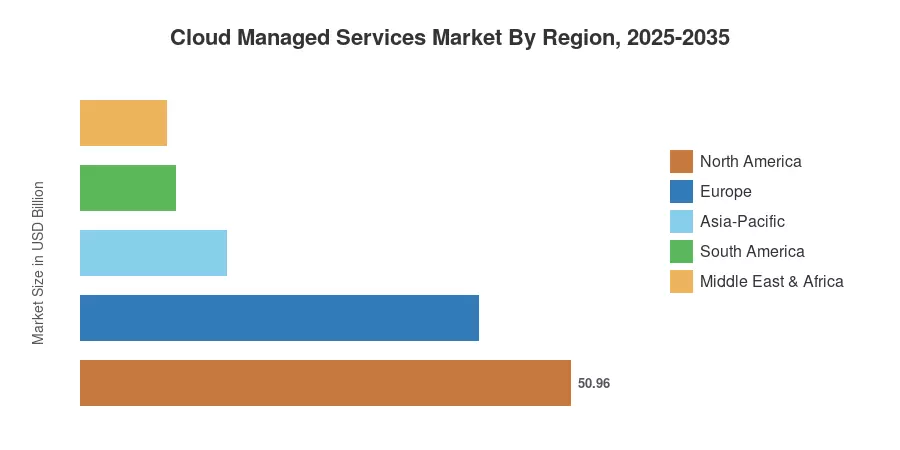
Regionally, North America held 34.2% of 2025 spending, supported by hyperscaler proximity and mature contracting norms. Asia-Pacific runs fastest at 10.21% CAGR, lifted by India's Digital India stack and ASEAN data-residency rules. Europe sits second at 27.8% share, where sovereign cloud mandates rather than cost arbitrage set the agenda. The next decade will reward providers who can prove regulatory depth, not just uptime.


Key Report Takeaways

• By Technology

  • Managed infrastructure services led the Cloud Managed Services Market with 34.15% revenue share in 2025
  • Managed security services expand at 11.42% CAGR through 2035 as breach liability shifts to operators
  • Hybrid cloud deployment posts a 12.31% CAGR, the fastest of any deployment model

• By Sector

  • BFSI accounted for 29.21% of 2025 revenue, driven by resilience mandates
  • Retail and e-commerce workloads grow at 10.87% CAGR to 2035
  • Large enterprises contributed USD 88.98 billion in 2025 spending

• By Region

  • North America commanded 34.2% of the Cloud Managed Services Market in 2025
  • Asia-Pacific advances at 10.21% CAGR across the forecast period
  • Middle East & Africa reached USD 8.94 billion in 2025 on sovereign cloud buildouts


Market Size and Forecast (2021–2035)

Figures below blend hyperscaler partner-program disclosures, systems integrator segment reporting, procurement records from public-sector cloud frameworks, and primary interviews with 60+ enterprise infrastructure leads. Historical years are reconciled against audited service-line revenue where available.
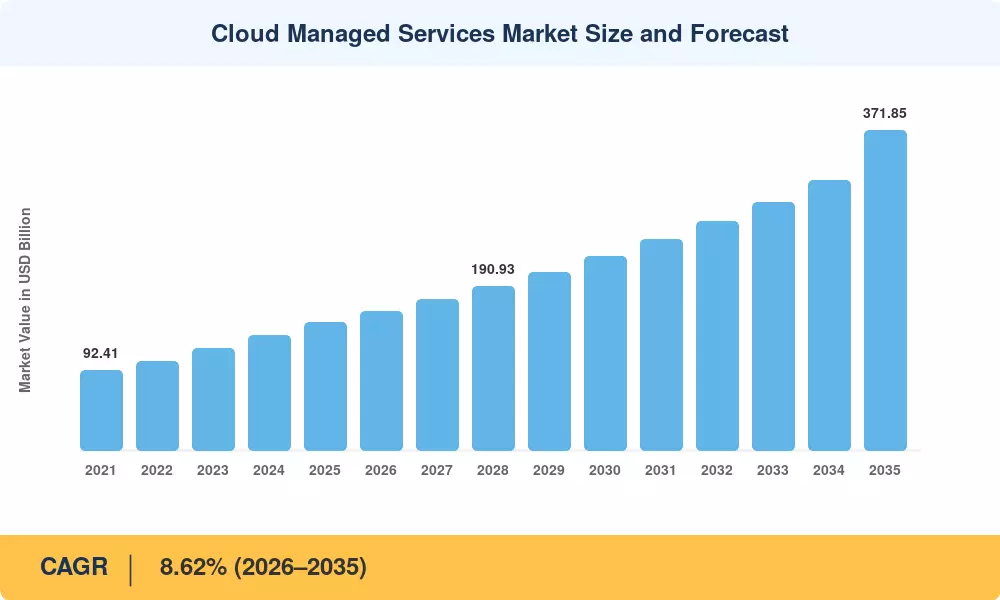
Cloud Managed Services Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory resilience mandates ~2.1% Europe, North America Short-term (≤2 yr)
Multi-cloud operational complexity ~1.8% Global Short-term (≤2 yr)
AI workload infrastructure demand ~1.6% North America, APAC Medium-term (2–4 yr)
Cybersecurity talent shortage ~1.4% Global Medium-term (2–4 yr)
SME cloud adoption in emerging economies ~1.1% APAC, South America Long-term (≥4 yr)
Sovereign cloud policy expansion ~0.9% Europe, MEA Long-term (≥4 yr)
Sustainability and energy reporting ~0.7% Europe Long-term (≥4 yr)


Regulatory Resilience Mandates

With fines up to 1% of average daily global turnover, DORA requires in-scope financial organizations to keep a register of ICT third-party agreements and to show exit strategies for essential suppliers [2]. Because compliance work is ongoing and unglamorous, it ends up with outside operators. According to a 2025 survey of European banks, outsourced cloud governance budgets increased by a median of 18% annually [12]. Spending like that is sticky.


Multi-Cloud Operational Complexity

Flexera's 2025 State of the Cloud study found 89% of enterprises running multi-cloud estates, with 27% reporting more than USD 12 million in annual public cloud waste [4]. Each additional platform multiplies identity models, tagging schemes, and billing formats. Internal teams rarely scale linearly against that. Providers who normalise telemetry across three or more platforms command premium rates in the Cloud Managed Services Market.

AI Workload Infrastructure Demand

The IEA projected data centre electricity consumption could reach roughly 945 TWh by 2030, with AI training and inference the dominant marginal load [7]. GPU clusters demand scheduling discipline, thermal-aware placement and utilization accounting that traditional server operations never required. Enterprises buying accelerated capacity increasingly buy the operating layer alongside it.

Cybersecurity Talent Shortage

ISC2 estimated a global cybersecurity workforce gap of about 4.8 million professionals in 2024 [6]. Cloud security engineering sits at the scarcest end of that gap. Rather than compete for scarce hires, mid-market firms contract 24/7 detection and response into the Cloud Managed Services Market, where operators amortize the same specialists across dozens of estates.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Margin compression from automation ~-1.2% Global Medium-term (2–4 yr)
Data sovereignty fragmentation ~-0.9% Europe, APAC Short-term (≤2 yr)
In-house platform team insourcing ~-0.8% North America Medium-term (2–4 yr)
Hyperscaler first-party service expansion ~-0.7% Global Long-term (≥4 yr)
Contract disputes over SLA attribution ~-0.5% Global Short-term (≤2 yr)


Margin Compression from Automation

Automation cuts the labour hours a provider can bill. As remediation playbooks handle a rising share of incidents, per-seat and per-instance pricing erodes. Industry filings suggest managed services gross margins narrowed by roughly 240 basis points between 2022 and 2025 across listed integrators [13]. Providers respond by moving to outcome-based contracts, but repricing legacy books takes years.

Data Sovereignty Fragmentation

Sovereignty rules rarely align. India's data centre localization guidance, the EU Cloud Sovereignty framework and Saudi Arabia's Cloud Computing Regulatory Framework each impose distinct residency, personnel-vetting and audit requirements [8]. Serving a multinational estate then requires duplicated toolchains and locally-cleared staff. That kills the economies of scale on which the Cloud Managed Services Market historically depended.

Hyperscaler First-Party Service Expansion

A line item is eliminated from a partner's statement of work for each managed database, managed Kubernetes, and managed observability product that a hyperscaler ships [14]. Moving up-stack into application operations and compliance attestation has been the business solution, but the ceiling keeps falling. Structural squeeze affects partners who lack vertical specialization.


Cloud Managed Services Market Opportunities

SME Penetration in Emerging Economies

Small and medium enterprises across India, Indonesia and Vietnam remain underserved, with the World Bank estimating over 65 million formal SMEs in developing economies lacking structured IT operations support [11]. Standardized, low-touch service tiers priced under USD 2,000 monthly open a volume channel the Cloud Managed Services Market has barely tapped.

Telemetry Monetization and Benchmarking Products

Operators can bundle anonymized benchmarking, such as cost-per-workload, incident mean-time-to-resolve, and carbon-per-transaction, as a subscription service if they have years' worth of cross-client performance data. This increases switching costs and turns an operational byproduct into recurring high-margin revenue.


Sovereign and Regulated-Vertical Cloud Operations

Workloads in public administration, healthcare, and defense have clearance, residency, and audit requirements that prevent generalist competitors. Pricing is 30–45% more than commercial baselines when providers invest in accredited staff and domestic facilities [8].


AI Operations and GPU Estate Management

Scheduling, cost attribution and thermal optimization for accelerated compute is an emerging discipline with almost no installed base of incumbent expertise. Early movers define the reference architecture for the Cloud Managed Services Market.

Carbon-Aware Workload Placement

CSRD reporting obligations now reach thousands of EU-operating firms [10]. Shifting batch workloads to low-carbon-intensity regions and hours produces auditable emissions reductions — a service line that did not exist commercially before 2023.


Cloud Managed Services Market Future Outlook

Autonomous Operations Become the Baseline

By 2030, closed-loop remediation will handle the majority of routine incidents. The shift moves provider value from response speed to policy quality — who writes the better guardrail, not who answers the pager faster. Commercial models follow, migrating toward availability outcomes and consumption-linked fees.

Platform Economics and Contract Consolidation

Fragmented multi-vendor arrangements are expensive to govern. Expect buyers to consolidate around two or three strategic operators with unified telemetry, mirroring what happened in facilities management two decades ago. Scale advantages accrue to providers with proprietary control planes rather than resold toolchains.

The Energy Constraint

IEA analysis indicates data centre electricity demand could roughly double by 2030 [7]. Power availability, not compute availability, becomes the binding constraint on workload placement. Operators who can model grid carbon intensity and negotiate capacity across regions will hold real commercial leverage in the Cloud Managed Services Market.

Sustainability Reporting as Contract Requirement

CSRD phase-in extends assurance obligations across large EU-operating firms through the late 2020s [10]. Scope 3 emissions from cloud consumption require auditable, provider-supplied data. Contracts increasingly specify emissions reporting formats alongside uptime targets — a structural change to what managed services must deliver.


Regional Market Share Analysis

Region Metric Primary Investment Themes
North America 34.2% share AI operations, FedRAMP-authorized delivery
Europe 27.8% share DORA compliance, sovereign cloud
Asia-Pacific 10.21% CAGR SME digitization, data localization
South America USD 9.83 Billion Fintech scaling, cost optimization
Middle East & Africa USD 8.94 Billion National cloud programs, giga-project IT
Total USD 149.02 Billion —


North America

Country Metric Key Driver
US 84.1% of region Federal cloud authorization pipeline
Canada 10.7% of region Protected B workload migration
Mexico 5.2% of region Nearshore delivery centre growth


North American demand is shaped less by migration and more by estate rationalization. The FedRAMP modernization roadmap shortened authorization timelines and expanded reuse of existing packages, widening the pool of providers able to serve federal buyers [1]. Commercially, U.S. enterprises increasingly split contracts — one operator for security, another for platform engineering — which raises total addressable spend even where workload growth flattens.

Europe

Country Metric Key Driver
Germany 23.4% of region Industrial data sovereignty
UK 21.8% of region Financial services resilience
France 15.1% of region SecNumCloud qualification demand
Italy 8.9% of region Public administration migration
Spain 7.6% of region Digital Spain 2026 programme
Nordic Countries 9.2% of region Low-carbon data centre siting
Russia 3.1% of region Domestic platform substitution
Rest of Europe 10.9% of region Cross-border cloud frameworks


Europe's growth is regulatory in origin. DORA's third-party register requirement forced financial institutions to formalize arrangements that had lived in informal statements of work [2]. France's SecNumCloud qualification and Germany's Gaia-X-derived architectures add a second qualification layer. Providers holding both national accreditation and hyperscaler competency badges face little effective competition in regulated segments.

Asia-Pacific

Country Metric Key Driver
China 31.2% of region State-backed cloud consolidation
India 19.7% of region Digital India public stack
Japan 17.4% of region Legacy mainframe retirement
South Korea 10.3% of region K-Cloud national programme
ASEAN 14.1% of the region Cross-border data rules
Rest of Asia-Pacific 7.3% of region Telecom-led managed offerings


India anchors much of the regional acceleration. Government digital public infrastructure has normalised cloud consumption among mid-sized firms that previously ran co-located hardware. Japan presents a different profile: an ageing mainframe estate with a documented systems engineer shortage pushes replatforming work directly to external operators. Together, these dynamics make Asia-Pacific the fastest-growing block in the Cloud Managed Services Market.

South America

Country Metric Key Driver
Brazil 11.4% CAGR LGPD compliance operations
Argentina 8.7% CAGR Fintech infrastructure demand
Rest of South America 7.9% CAGR Regional hyperscaler zone launches


Brazil dominates regional spend, with LGPD enforcement driving formalised data handling processes that most mid-market firms cannot staff internally. Currency volatility complicates multi-year contracting, so providers increasingly price in local currency with indexed escalators. Regional cloud region launches since 2023 have removed the latency objection that previously slowed migration.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.6% of region Vision 2030 digital programmes
UAE 27.2% of the region Government cloud-first policy
South Africa 14.8% of the region Financial sector modernization
Egypt 8.4% of region Public digitization initiatives
Rest of MEA 15.0% of region Telecom operator partnerships


Gulf demand is programme-driven rather than organically enterprise-led. Saudi Arabia's Cloud Computing Regulatory Framework establishes registration and classification duties that effectively require locally-registered operators [8]. Giga-project IT estates — NEOM, Red Sea developments — represent greenfield builds with no legacy constraint, allowing providers to deploy modern operating models from day one.


Cloud Managed Services Market By Region, 2025-2035

Cloud Managed Services Market Segmentation

By Service Type

The Cloud Managed Services Market splits its service taxonomy as follows.

Segment Metric Primary Demand Driver
Managed Infrastructure Services 34.15% share Estate consolidation programmes
Managed Network Services 18.62% share SD-WAN and connectivity sprawl
Managed Security Services 11.42% CAGR Threat volume and talent scarcity
Managed Mobility Services USD 14.31 Billion Distributed workforce endpoints
Other Service Types 17.94% share Application and data operations


Managed infrastructure retains leadership because it is where estate complexity concentrates — compute, storage, backup and identity all sit under it. Managed security grows fastest for a different reason: liability. Boards now treat cloud misconfiguration as a governance failure, and external operators carry contractual accountability that internal teams cannot.

By Deployment Type

Deployment preference shapes delivery economics across the Cloud Managed Services Market.

Segment Metric Primary Demand Driver
Public Cloud 47.55% share Hyperscaler capability depth
Private Cloud 25.13% share Regulated workload residency
Hybrid Cloud 12.31% CAGR Legacy integration requirements


Public cloud holds majority share, but hybrid grows fastest, and the reason is unglamorous: most large enterprises will not fully exit their data centres this decade. Managing the seam between estates — consistent identity, unified monitoring, workload portability — is technically harder than managing either side alone, which supports premium pricing.

By Enterprise Size

Segment Metric Primary Demand Driver
Large Enterprise USD 88.98 Billion Multi-region estate governance
SMEs 10.41% CAGR Packaged low-touch service tiers


Large enterprises anchor the revenue at USD 88.98 billion, driven by the unglamorous complexity of multi-region estate governance—keeping disparate systems compliant and secure across borders is far harder than managing a single infrastructure footprint, commanding premium budgets. Meanwhile, SMEs expand at a rapid 10.41% CAGR, propelled by the pragmatic need for packaged low-touch service tiers that eliminate the friction of bespoke cloud migrations.

By End User Industry

Vertical demand within the Cloud Managed Services Market concentrates as follows.

Segment Metric Primary Demand Driver
BFSI 29.21% share Operational resilience regulation
IT and Telecom 21.47% share Network function virtualization
Retail and E-Commerce 10.87% CAGR Peak-season elasticity needs
Healthcare USD 16.24 Billion Clinical data compliance
Manufacturing 12.83% share Industrial IoT data pipelines
Other End Users 12.65% share Public sector and education


BFSI leads on regulatory weight rather than workload volume — each euro of financial-services cloud spend carries more governance overhead than the equivalent in media or retail. Retail's growth reflects a structural change in demand shape: elastic peak capacity for seasonal events requires operational choreography that most retail IT teams staff only once a year.


Competitive Benchmarking

Concentration sits in the medium band, with an estimated HHI near 620 and a top-five share of roughly 31%. That combination describes a market where global integrators hold scale advantages in large-enterprise deals while thousands of regional providers compete effectively in mid-market and vertical niches. No single provider approaches pricing power, and competitive differentiation increasingly rests on compliance credentials and vertical depth rather than rate cards.

Company Est. Revenue Share Range Key Offerings for Cloud Managed Services Market Strategic Positioning
Accenture ~8–11% Cloud transformation, managed operations, security Scale leader in large-enterprise transformation
IBM (incl. Kyndryl heritage) ~6–9% Hybrid cloud management, mainframe modernization Hybrid and regulated-industry specialist
Infosys ~4–6% Cobalt cloud services, application operations Cost-competitive global delivery
Wipro ~3–5% FullStride cloud, managed security operations Vertical-led consulting integration
Tata Consultancy Services ~4–6% Cloud operations, SAP and Oracle managed services Enterprise application operations depth
Rackspace Technology ~2–4% Multi-cloud managed services, FinOps Pure-play multi-cloud operator
NTT DATA ~3–5% Managed network and cloud, edge operations Network-adjacent infrastructure strength
  ~3–5% Cloud risk, compliance-led managed services Regulatory and audit positioning
Capgemini ~3–5% Cloud platform operations, sovereign cloud European sovereignty specialist
HCLTech ~3–5% CloudSMART, autonomous operations Automation-first delivery model
Atos / Eviden ~2–4% Managed hybrid cloud, cybersecurity operations European public-sector footprint
Fujitsu ~2–3% Managed infrastructure, Japanese enterprise migration Regional incumbent in Japan


Recent News & Developments

  • European Commission (January 2025): DORA became applicable across EU financial entities, mandating ICT third-party registers and exit plans — immediately expanding compliance-linked managed services demand [2].
  • Accenture (March 2025): Expanded its cloud managed services practice through acquisition of a European sovereign cloud operator, adding SecNumCloud-adjacent delivery capability [15].


  • Saudi Communications and Information Technology Commission (June 2024): Updated the Cloud Computing Regulatory Framework classification tiers, tightening registration duties for foreign operators serving Saudi workloads [8].
  • Rackspace Technology (November 2024): Launched a FinOps-led optimization offering with contractual savings guarantees, moving pricing toward outcome-based structures [17].
  • HCLTech (February 2025): Extended a multi-year managed cloud agreement with a global financial institution covering hybrid estate operations across three continents [18].
  • Infosys (July 2023): Opened dedicated cloud operations centres in Europe to meet data residency and personnel-location clauses emerging in DORA-anticipating contracts [19].
  • Capgemini (October 2025): Announced a sovereign cloud managed services joint venture targeting European public administration workloads [20].


Cloud Managed Services Market Report Scope

Parameter Detail
Market Scope Global outsourced management, monitoring, optimization and security of public, private and hybrid cloud environments
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.62% (2026–2035)
Market Size Checkpoints USD 149.02 Billion (2025); USD 161.83 Billion (2026); USD 371.85 Billion (2035)
Fastest Growing Segments Hybrid Cloud (deployment); Managed Security Services (service type); Retail and E-Commerce (end user); Asia-Pacific (geography)
Companies Profiled Accenture, IBM, Infosys, Wipro, TCS, Rackspace Technology, NTT DATA, Capgemini, HCLTech, Atos/Eviden, Fujitsu
Valuation Currency USD Billion

FAQs

How should a buyer structure exit clauses in a Cloud Managed Services Market contract?
Specify data extraction formats, knowledge-transfer duration, and runbook ownership upfront. DORA requires documented exit strategies for critical providers, making this a compliance item rather than a negotiation nicety [2].
What distinguishes a managed service provider from a systems integrator in practice?
Integrators are paid to deliver change; managed providers are paid to sustain steady state. Contracting the same firm for both creates incentive conflict on defect remediation [12].
Which pricing model works best for variable AI workloads?
Consumption-linked pricing with a committed floor generally outperforms per-seat models here. GPU utilization swings too violently for headcount-based structures to price fairly [7].
Are hyperscaler-native tools sufficient without a Cloud Managed Services Market provider?
Native tools cover single-platform estates adequately. Once a second platform enters, normalization of identity, tagging and billing exceeds what native tooling handles [4].
What certifications actually matter when shortlisting providers?
Beyond ISO 27001, look for jurisdiction-specific credentials — SecNumCloud in France, FedRAMP authorization in the US [1] [22]. Generic badges rarely satisfy regulated buyers.
How do integration challenges differ for the Cloud Managed Services Market in legacy manufacturing estates?
Operational technology networks often cannot tolerate agent installation or scheduled reboots. Providers must deploy passive monitoring and negotiate maintenance windows against production schedules [9].
What procurement mistake most damages Cloud Managed Services Market outcomes?
Buying on an hourly rate rather than incident-resolution outcome. Rate-based contracts reward slow remediation, while outcome-linked structures align provider economics with estate stability [17].    
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach

Research Methodology on Cloud-Managed Services Market

Introduction

This research report proposes to study the global cloud managed services market which covers various enterprise and industry segments. The research aims to analyze the market and its progress in the past five years to estimate the market value over the forecast period 2023-2030. The pertinent questions to be answered revolve around the estimation of the size and value of the market and the impact of its dynamics on the industry developments during this period.

The research process is designed to explore the market dynamics and assess their influence on the growth of the cloud-managed services market in terms of revenue and market size. The short-term and long-term objectives of the research are cited in detail. The overall methodology of the research is described so that the research goals and approach can be recognized clearly. The population, data sources, and collection of data are mentioned at length. Appropriate stratification, scalarization and analysis methods are also discussed to evaluate the market progress.

Research Goals and Objectives

The primary aim of the research report is to provide a comprehensive assessment of the cloud-managed services market and its trends since 2022, and to estimate its growth rate and market size for the period 2023-2030. The research caters to the needs of stakeholders in the industry, by providing them a strategic understanding of the actions and decisions taken by them.

The short-term objectives of the research:

  • To evaluate the market size and forecast the value of the cloud-managed services market during the period 2023-2030.
  • To analyze the market dynamics and trends associated with cloud-managed services over the forecast period 2023 to 2030.
  • To provide an in-depth analysis of the vendor landscape and the key players in the cloud-managed services market.

The long-term objectives of the research include:

  • To analyze the impact of emerging technologies on the cloud-managed services market.
  • To provide insights into emerging market opportunities for the introduction of new offerings.
  • To understand the demand for cloud-managed services in various industry verticals.

Research Methodology

The research process includes primary and secondary data from various sources such as industry-specific reports, white papers, and research journals. The Market Research Future (MRFR) experts also conducted a market survey to obtain a more in-depth understanding of the market. The surveys are designed to obtain a more accurate assessment of the market trends and dynamics.

Further, the market survey captures data from a broad-based set of vendors, organizations, and associations. With the use of the gathered data, the MRFR team aims to analyze the market size, the technological developments, and the application of cloud-managed services. In addition, the research identifies the potential vendors in the industry and their products, pricing structures and market strategies.

Population, Sample and Data Collection

The population for the research include both suppliers and consumers of cloud-managed services. The survey had a sample size of 1000 respondents, who were dynamic and computer-literate. The survey was conducted with the help of email, interviews, and questionnaires. The respondents include CXOs, directors, company executives, and business owners among others.

The scope of the study includes the collection of data from various sources such as industry publications, reports, and white papers. In addition, the data is collected from online sources, magazines, and press releases of the industry. The collected data is further validated by the experts and senior management, before further analysis.

Data Stratification and Analysis

The data gathered is stratified based on geographical location, market size, and segmentation. Further, the data is scalarized to arrive at the market size. This is followed by the analysis of the data concerning the market overview, market performance analysis, the vendor landscape, and the analysis of the market trends.

The market performance analysis involves using statistical methods such as the SWOT analysis and Porter’s five forces model to comprehend the growth opportunities and the threats faced by the industry. The market overview is achieved through extensive interviews held with the key players in the market. The study of the market trends is to identify any upcoming opportunities in the market.

The final analysis of the results is done by experts who apply their industry knowledge to understand the impact of the market dynamics on the market. The results of the research are presented in the form of a market report with details of the market size, key players, and market trends.

Conclusion

This research report discusses the research methodology deployed by Market Research Future ( MRFR) to analyze the global cloud-managed services market. The research employed a combination of primary and secondary data collection techniques for obtaining an in-depth understanding of the market. Household surveys and estimated research data techniques were used to assess the market size and trends from 2023-2030. The market is analyzed using market performance analysis, a technological overview, the vendor landscape, and an analysis of the market trends. With the help of the conducted analysis, the research aims to provide stakeholders with a better understanding of the market and its demand in various industry verticals.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















