Cloud Communication Platform Market (2026 - 2035)

ID: MRFR/ICT/2094-CR 123 Pages Ankit Gupta Last Updated: September 15, 2026
Cloud Communication Platform Market Size, Share and Research Report By Data-Sovereignty and Localization Mandates, By Carrier Termination Economics, By Communication Fraud Exposure and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
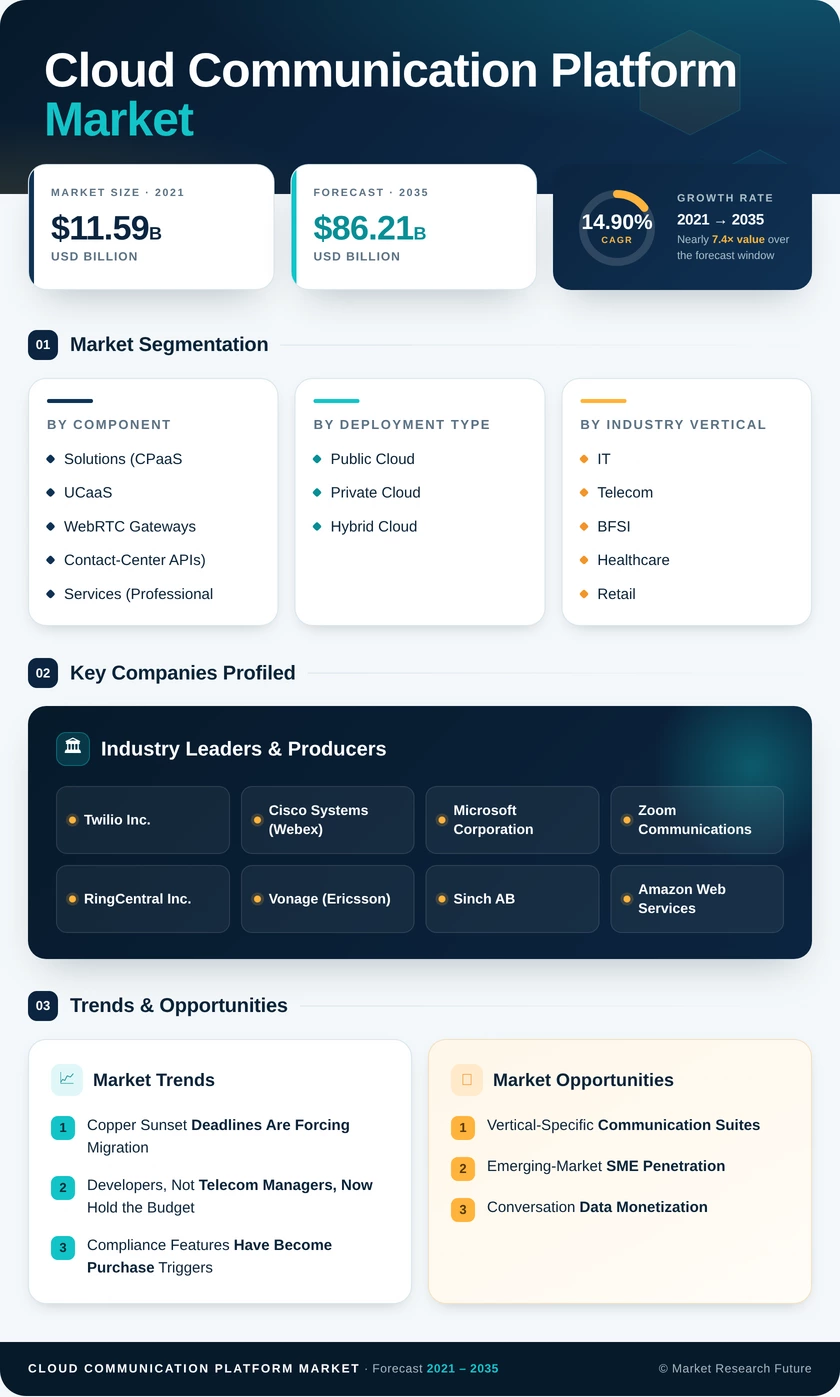
Cloud Communication Platform Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.90%
2025 Market SizeUSD 21.51 Billion
2035 Market SizeUSD 86.21 Billion
Key Players
Twilio Inc.
Cisco Systems
Microsoft Corporation
Zoom Communications
RingCentral Inc.
Vonage
Opportunities
  • Vertical-Specific Communication Suites
  • Emerging-Market SME Penetration
  • Conversation Data Monetization
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology |
    4. 1.4 Market Summary
  2. 2 Key Report Takeaways |
    1. 2.1 Takeaways by Technology |
    2. 2.2 Takeaways by Sector |
    3. 2.3 Takeaways by Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Estimate (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Drivers Analysis |
    1. 4.1 Copper Sunset Deadlines and PBX Retirement |
    2. 4.2 Developer-Led Procurement and API Adoption |
    3. 4.3 Compliance Tooling as a Purchase Trigger |
    4. 4.4 Latency Economics and Edge Deployment
  5. 5 Market Restraints Analysis |
    1. 5.1 Data-Sovereignty and Localization Mandates |
    2. 5.2 Carrier Termination Economics |
    3. 5.3 Communication Fraud Exposure
  6. 6 Market Opportunity Analysis |
    1. 6.1 Vertical-Specific Communication Suites |
    2. 6.2 Emerging-Market SME Penetration |
    3. 6.3 Conversation Data Monetization |
    4. 6.4 Sovereign and Regional Cloud Zones |
    5. 6.5 Autonomous Contact Center Operations |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Autonomous Interaction Handling |
    2. 8.2 Platform Economics and Consolidation |
    3. 8.3 Sustainability in Vendor Selection |
    4. 8.4 Network APIs and Carrier Relationships
  9. 9 Segmentation Analysis |
    1. 9.1 By Component | |
      1. 9.1.1 Solutions | | |
        1. 9.1.1.1 CPaaS | | |
        2. 9.1.1.2 UCaaS | | |
        3. 9.1.1.3 WebRTC Gateways | | |
        4. 9.1.1.4 Contact-Center APIs | |
      2. 9.1.2 Services | | |
        1. 9.1.2.1 Professional Services | | |
        2. 9.1.2.2 Managed Services |
    2. 9.2 By Deployment Type | |
      1. 9.2.1 Public Cloud | |
      2. 9.2.2 Private Cloud | |
      3. 9.2.3 Hybrid Cloud |
    3. 9.3 By Industry Vertical | |
      1. 9.3.1 IT and Telecom | |
      2. 9.3.2 BFSI | |
      3. 9.3.3 Healthcare | |
      4. 9.3.4 Retail and E-commerce | |
      5. 9.3.5 Media and Entertainment | |
      6. 9.3.6 Government and Public Sector | |
      7. 9.3.7 Others |
    4. 9.4 By Enterprise Size | |
      1. 9.4.1 Large Enterprises | |
      2. 9.4.2 Small and Medium-sized Enterprises
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Twilio Inc. | |
      2. 10.3.2 Cisco Systems (Webex) | |
      3. 10.3.3 Microsoft Corporation | |
      4. 10.3.4 Zoom Communications | |
      5. 10.3.5 RingCentral Inc. | |
      6. 10.3.6 Vonage (Ericsson) | |
      7. 10.3.7 Sinch AB | |
      8. 10.3.8 Amazon Web Services | |
      9. 10.3.9 8x8 Inc. | |
      10. 10.3.10 Infobip Ltd. | |
      11. 10.3.11 Bandwidth Inc.
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Valuation Currency & Assumptions |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Cloud Communication Platform Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Cloud Communication Platform Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis – Contribution to CAGR, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis – Drag on CAGR, 2026–2035 |
  20. TABLE 5 Global Market Size, by Component, 2021–2035 (USD Billion) |
  21. TABLE 6 Global Market Size, by Solutions Sub-Segment, 2021–2035 (USD Billion) |
  22. TABLE 7 Global Market Size, by Services Sub-Segment, 2021–2035 (USD Billion) |
  23. TABLE 8 Global Market Size, by Deployment Type, 2021–2035 (USD Billion) |
  24. TABLE 9 Global Market Size, by Industry Vertical, 2021–2035 (USD Billion) |
  25. TABLE 10 Global Market Size, by Enterprise Size, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Market Size, by Region, 2021–2035 (USD Billion) |
  27. TABLE 12 North America Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 13 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  29. TABLE 14 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  30. TABLE 15 South America Market Size, by Country, 2021–2035 (USD Billion) |
  31. TABLE 16 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  32. TABLE 17 North America Market Size, by Component, 2021–2035 (USD Billion) |
  33. TABLE 18 North America Market Size, by Deployment Type, 2021–2035 (USD Billion) |
  34. TABLE 19 North America Market Size, by Industry Vertical, 2021–2035 (USD Billion) |
  35. TABLE 20 Europe Market Size, by Component, 2021–2035 (USD Billion) |
  36. TABLE 21 Europe Market Size, by Deployment Type, 2021–2035 (USD Billion) |
  37. TABLE 22 Europe Market Size, by Industry Vertical, 2021–2035 (USD Billion) |
  38. TABLE 23 Asia-Pacific Market Size, by Component, 2021–2035 (USD Billion) |
  39. TABLE 24 Asia-Pacific Market Size, by Deployment Type, 2021–2035 (USD Billion) |
  40. TABLE 25 Asia-Pacific Market Size, by Industry Vertical, 2021–2035 (USD Billion) |
  41. TABLE 26 South America Market Size, by Component, 2021–2035 (USD Billion) |
  42. TABLE 27 Middle East & Africa Market Size, by Component, 2021–2035 (USD Billion) |
  43. TABLE 28 US Market Size, by Component and Vertical, 2021–2035 (USD Billion) |
  44. TABLE 29 China Market Size, by Component and Vertical, 2021–2035 (USD Billion) |
  45. TABLE 30 India Market Size, by Component and Vertical, 2021–2035 (USD Billion) |
  46. TABLE 31 Competitive Benchmarking Matrix, 2026 |
  47. TABLE 32 Company Profiles – Key Players |
  48. TABLE 33 Recent Developments & Strategic Announcements, 2023–2025 |
  49. TABLE 34 Report Scope & Methodology Summary |
  50. TABLE 35 Detailed Sources & Citations
  51. 16 LIST OF FIGURES |
  52. FIGURE 1 Market Dynamics – Drivers, Restraints, Opportunities, and Challenges |
  53. FIGURE 2 Industry Value Chain Analysis |
  54. FIGURE 3 Porter's Five Forces Analysis |
  55. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) |
  56. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) |
  57. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) |
  58. FIGURE 7 Market Share by Deployment Type, 2025 vs 2035 (%) |
  59. FIGURE 8 Market Share by Industry Vertical, 2025 (%) |
  60. FIGURE 9 Market Share by Enterprise Size, 2025 vs 2035 (%) |
  61. FIGURE 10 Regional Revenue Share, 2025 (%) |
  62. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  63. FIGURE 12 North America Country-Level Share, 2025 (%) |
  64. FIGURE 13 Europe Country-Level Share, 2025 (%) |
  65. FIGURE 14 Asia-Pacific Country-Level Share, 2025 (%) |
  66. FIGURE 15 Competitive Landscape – Estimated Revenue Share Bands, 2026 |
  67. FIGURE 16 Vendor Positioning Matrix – Capability vs Compliance Depth |
  68. FIGURE 17 Pricing Model Evolution, 2026–2035 |
  69. FIGURE 18 Adoption Curve by Enterprise Size, 2021–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentSolutions (CPaaS, UCaaS, WebRTC Gateways, Contact-Center APIs); Services (Professional, Managed)SolutionsServices
By Deployment TypePublic Cloud; Private Cloud; Hybrid CloudPublic CloudHybrid Cloud
By Industry VerticalIT and Telecom; BFSI; Healthcare; Retail and E-commerce; Media and Entertainment; Government and Public Sector; OthersIT and TelecomHealthcare
By Enterprise SizeLarge Enterprises; Small and Medium-sized EnterprisesLarge EnterprisesSmall and Medium-sized Enterprises
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
CPaaSCommunication embedded directly into applications through programmable interfaces
UCaaSSeat-based collaboration consolidating voice, video, and chat into one contract
WebRTC GatewaysBrowser-native media handling replacing plugin and appliance dependencies
Contact-Center APIsComposable routing and analytics displacing monolithic CCaaS suites
Professional ServicesDial-plan migration, number porting, and compliance validation engagements
Managed ServicesContinuous operations, monitoring, and optimization on subscription terms


Component demand is shifting from packaged suites toward composable building blocks. Buyers increasingly assemble routing, media, and analytics from separate services rather than accepting a single vendor's full stack, which raises integration effort and explains why services outpace solutions on growth.

By Deployment Type

Sub-SegmentKey Trend
Public CloudDefault choice for elastic scaling and lowest total entry cost
Private CloudReserved for defense, critical infrastructure, and highly regulated isolation needs
Hybrid CloudFastest-growing model, splitting sensitive records from cost-efficient analytics workloads


Deployment decisions have become regulatory decisions. Where residency rules bind, hybrid architectures localize call records and recordings while non-real-time processing stays in shared regions — a compromise that adds complexity but preserves most of the economic advantage.

By Industry Vertical

Sub-SegmentKey Trend
IT and TelecomCommunication embedded into resold software products, creating dual buyer-channel role
BFSIRecorded advisory calls, transaction alerts, and identity verification at scale
HealthcareTelemedicine and patient engagement backed by reimbursement parity
Retail and E-commerceConversational commerce and order-lifecycle notifications
Media and EntertainmentInteractive live streaming with low-latency audience participation
Government and Public SectorCitizen service portals requiring sovereign hosting
OthersLogistics dispatch, education delivery, and manufacturing field support


Vertical concentration follows interaction volume. Sectors that touch customers many times per transaction generate disproportionate traffic, while sectors with high compliance intensity generate disproportionate contract value — healthcare and BFSI sit at the intersection of both.

By Enterprise Size

Sub-SegmentKey Trend
Large EnterprisesMulti-country consolidation contracts replacing fragmented regional PBX estates
Small and Medium-sized EnterprisesSelf-serve provisioning and consumption pricing removing procurement friction


Enterprise-size dynamics split revenue from momentum. Large accounts anchor the base with long, negotiated agreements, while smaller firms — particularly in emerging markets with no legacy equipment to retire — supply the steepest adoption curve through the forecast decade.

By Geography

Sub-SegmentKey Trend
North AmericaContact-center replacement cycle and caller-authentication compliance
EuropeSovereign hosting requirements and completed all-IP migration in core markets
Asia-Pacific5G standalone depth and SME leapfrog adoption at volume
South AmericaInstant-payment notification traffic and chat-first customer service
Middle East & AfricaGovernment digitalization programs mandating in-country cloud regions


Geographic performance tracks the interaction of regulation and infrastructure. Markets with firm sunset deadlines convert fastest, markets with strict residency rules convert toward hybrid, and markets with dense mobile coverage but thin legacy estates convert straight to cloud without an intermediate step.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.