Captive Portal Market Summary
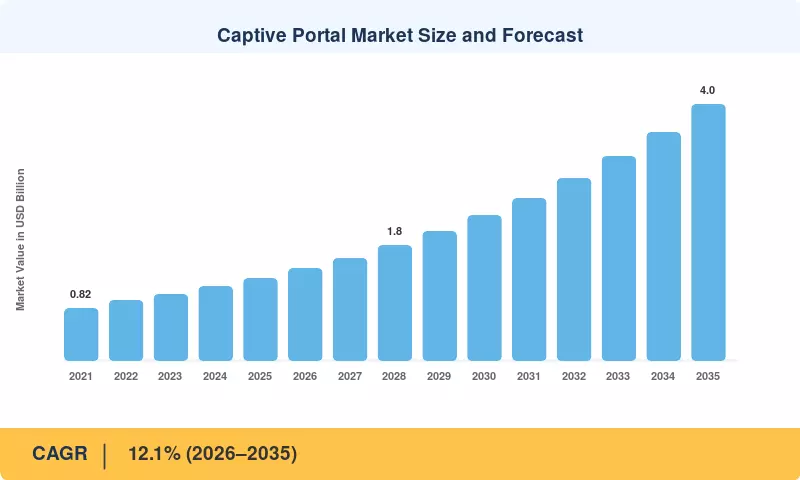
The Captive Portal Market was valued at USD 1.28 Billion in 2025 and is projected to grow from USD 1.43 Billion in 2026 to USD 4.00 Billion by 2035, registering a CAGR of 12.1% over the 2026–2035 forecast period. Public funding is the clearest near-term catalyst. The U.S. Broadband Equity, Access, and Deployment (BEAD) Program commits USD 42.45 Billion to connectivity build-outs [9], while India's PM-WANI framework is seeding thousands of neighbourhood public data offices that require authenticated user onboarding [7]. Every new venue hotspot funded under these programs needs a login, consent, and session-control layer.
Technology is shifting just as quickly. Venues are retiring appliance-based controllers and static splash pages in favour of cloud-managed, API-driven identity engines that combine social login, one-time passwords, property management system (PMS) lookups and Passpoint roaming in a single workflow. Modern guest Wi-Fi authentication increasingly runs on Wi-Fi 6E and Wi-Fi 7 access points, helped by the FCC's decision to open 1,200 MHz of 6 GHz spectrum for unlicensed use [12]. That spectrum expansion is driving hardware refresh cycles that pull portal upgrades along with them.
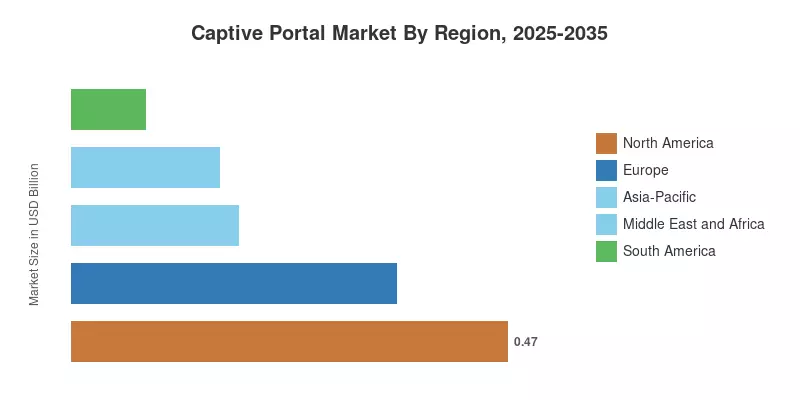
North America leads with a 36.5% share, anchored by hospitality chains, stadiums, and E-Rate-funded schools. Asia-Pacific is the fastest-growing region at a 14.2% CAGR, reflecting public hotspot programs in India and Southeast Asia and real-name registration rules in China. Europe holds a 27.0% share, where GDPR compliance shapes product design as much as demand does. Over the next decade, the Captive Portal Market will reward vendors that turn a compliance checkpoint into a revenue-generating customer engagement layer.
Key Report Takeaways
• By Deployment Model
- Cloud-Based deployments hold a 66.0% share of the Captive Portal Market, supported by subscription billing and centralized dashboards
- On-Premise systems are forecast to grow at an 8.1% CAGR, sustained by data-sovereignty requirements in government and defense venues
• By Authentication Method
- Social-Login accounts for a 42.5% share, driven by fast onboarding and demographic data capture
- Passpoint/OpenRoaming is the fastest-rising method at a 16.8% CAGR, backed by telecom-grade roaming federations
• By Enterprise Size
- Small and Mid-Size Businesses represent a 57.6% share, reflecting plug-and-play cloud kits
- Large Enterprises are expected to expand at a 9.4% CAGR as complex multi-site integrations mature
• By End-User Industry
- Hospitality holds a 35.9% share, with hotels using portals for loyalty enrolment and upsell prompts
- Transportation is the fastest-growing vertical in the Captive Portal Market at a 15.5% CAGR, led by airports and rail hubs
- Education generated USD 0.13 Billion in 2025, supported by school connectivity funding
• By Region
- North America commands a 36.5% share, the largest of any region
- Asia-Pacific leads growth at a 14.2% CAGR through 2035
Market Size and Forecast (2021–2035)
Estimates for the Captive Portal Market combine bottom-up modelling of installed access points, venue counts and average subscription pricing with top-down validation against vendor financial disclosures, public funding program data and interviews with network integrators. Historical values for 2021–2024 are reconciled against company filings and industry association data, 2025 serves as the base year, and 2026–2035 values are projected using driver and restraint weightings described in Sections 4 and 5.





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



