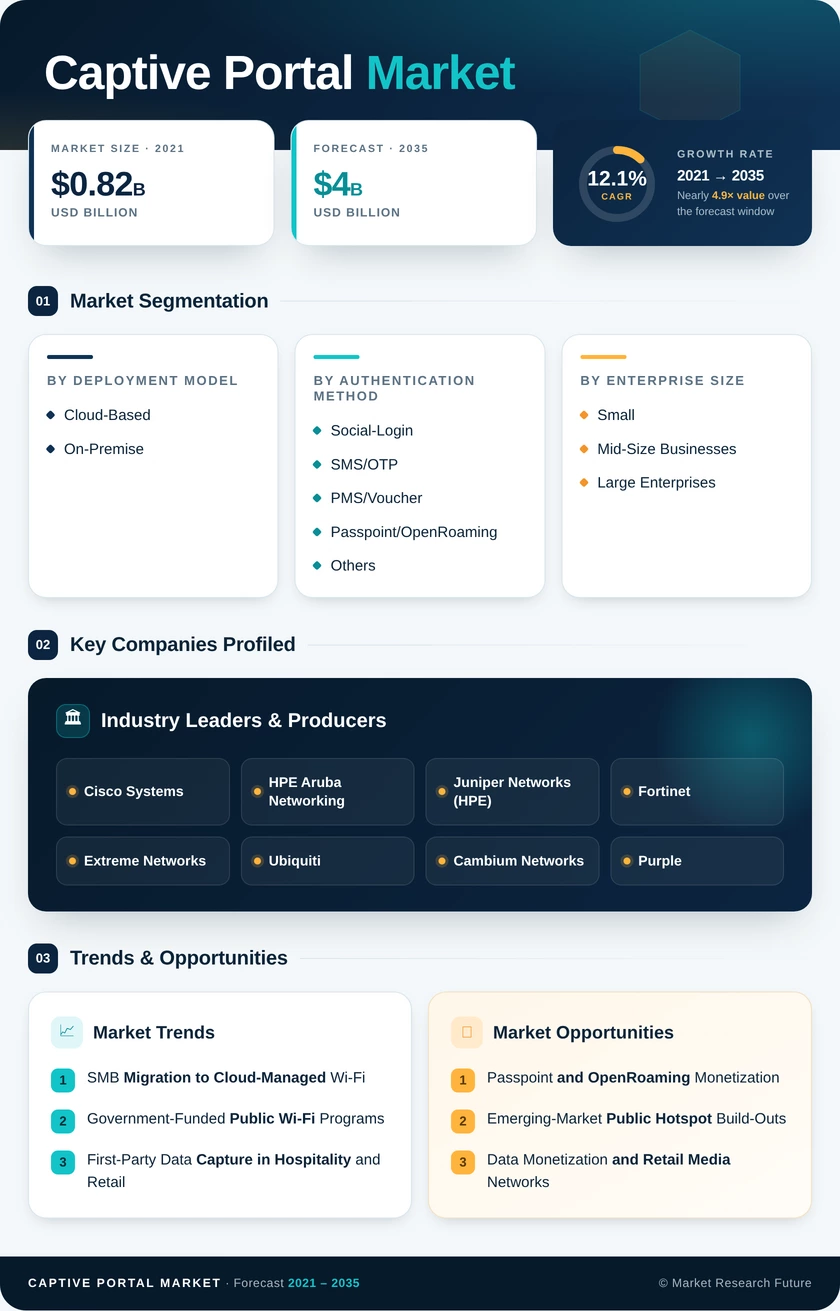
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Deployment Model | Cloud-Based; On-Premise | Cloud-Based (66.0% share) | Cloud-Based (66.0% share; faster-growing model) |
| By Authentication Method | Social-Login; SMS/OTP; PMS/Voucher; Passpoint/OpenRoaming; Others | Social-Login (42.5% share) | Passpoint/OpenRoaming (16.8% CAGR) |
| By Enterprise Size | Small and Mid-Size Businesses; Large Enterprises | Small and Mid-Size Businesses (57.6% share) | Small and Mid-Size Businesses (57.6% share; faster-growing cohort) |
| By End-User Industry | Hospitality; Retail and QSR; Transportation; Education; Others | Hospitality (35.9% share) | Transportation (15.5% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East and Africa | North America (36.5% share) | Asia-Pacific (14.2% CAGR) |
Market Segmentation Overview
By Deployment Model
| Sub-Segment | Key Trend |
|---|---|
| Cloud-Based | Multitenant platforms with continuous feature releases and built-in analytics |
| On-Premise | Retained in defense, government, and regulated healthcare sites |
Cloud-Based platforms lead with a 66.0% share and also grow faster than On-Premise systems, because subscription billing and centralized dashboards remove the need for local servers and in-house expertise. On-Premise deployments expand at a slower 8.1% CAGR, held in place by facilities that must keep authentication logs inside their own perimeter. Hybrid connectors that store logs locally while managing policy in the cloud are narrowing the gap between the two models.
By Authentication Method
| Sub-Segment | Key Trend |
|---|---|
| Social-Login | Fast onboarding, moderated by data-minimization limits |
| SMS/OTP | Required where identity verification is mandated |
| PMS/Voucher | Tied to hotel guest registries and paid access tiers |
| Passpoint/OpenRoaming | Automatic, carrier-grade roaming at high-traffic venues |
| Others | Email and click-through acceptance for low-risk venues |
Social-Login leads with a 42.5% share because guests already hold the credentials and venues gain demographic data at the moment of connection. Passpoint/OpenRoaming grows fastest at a 16.8% CAGR, since carriers and airports want silent, secure roaming for returning devices. SMS/OTP holds ground in markets with identity mandates, while PMS/Voucher remains the default for hotel stays and paid access.
By Enterprise Size
| Sub-Segment | Key Trend |
|---|---|
| Small and Mid-Size Businesses | Plug-and-play cloud kits and template splash pages |
| Large Enterprises | Deep integration with identity providers and zero-trust policy |
Small and Mid-Size Businesses lead with a 57.6% share and are the faster-growing cohort, as low-touch cloud onboarding lets cafés, clinics, and boutique retailers deploy compliant login flows without IT staff. Large Enterprises grow at a steadier 9.4% CAGR because their multi-site rollouts involve lengthy security reviews and identity-provider integration. Their contracts remain strategically important as reference accounts that validate vendor security credentials.
By End-User Industry
| Sub-Segment | Key Trend |
|---|---|
| Hospitality | Loyalty enrolment, upsell prompts and PMS integration |
| Retail and QSR | Footfall analytics and in-store promotions |
| Transportation | High-capacity authentication at airports, rail and cruise terminals |
| Education | Acceptable-use enforcement and guest isolation |
| Others | Healthcare, smart-city kiosks and event venues |
Hospitality leads with a 35.9% share because hotels monetize login events through loyalty sign-ups and room upgrades. Transportation grows fastest at a 15.5% CAGR, as passenger volumes above pre-pandemic levels require portals that authenticate thousands of devices per minute under strict security rules. Retail and QSR chains focus on analytics, while Education relies on portals to separate student, staff, and visitor traffic.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA