Atomizing Metal Powder Market (2026 - 2035)

Atomizing Metal Powder Market Research Report Information By The Atomization Process (Gas Atomization, Plasma Atomization, Water Atomization, Centrifugal Atomization, and Other Methods (e.g., Ultrasonic)), By Application (Additive Manufacturing (AM/3DP), Powder-Metallurgy Components/Parts, Cutting Tools and Wear Parts, Coatings and Thermal-Spray Materials, and Other Industrial Applications), and By End-user Industry (Aerospace and Defense, Automotive and EV Manufacturing, Medical and Dental Devices, Industrial Machinery and Tooling, Energy (Turbines, Oil and Gas), and Other End-user Industries) – Forecast Till 2035
ID: MRFR/CnM/7049-CR 186 Pages Chitranshi Jaiswal Last Updated: October 27, 2026
Atomizing Metal Powder Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.10%
2025 Market SizeUSD 3.36 Billion
2035 Market SizeUSD 6.67 Billion
Key Players
Höganäs AB
Sandvik AB
GKN Powder Metallurgy
Carpenter Technology Corporation
Rio Tinto Metal Powders
JFE Steel Corporation
Opportunities
  • Localised Capacity in Emerging Industrial Economies
  • Feedstock Lifecycle Data as a Revenue Line
  • Copper and Refractory Grades for Thermal Management

Atomizing Metal Powder Market Summary

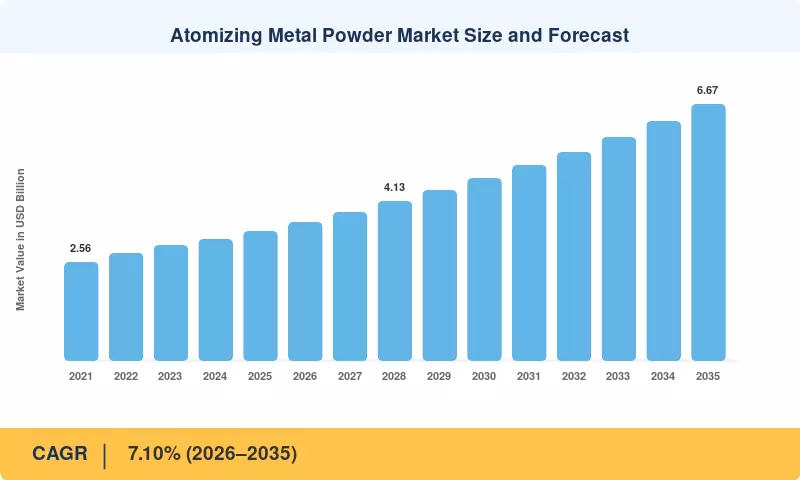
The Atomizing Metal Powder Market reached USD 3.36 billion in 2025 and opens the forecast window at USD 3.60 billion in 2026, tracking toward USD 6.67 billion by 2035 at a 7.10% CAGR. Two catalysts anchor that path. The U.S. Department of Defense committed roughly USD 1.2 billion across FY2023–FY2025 to domestic titanium and superalloy feedstock capacity [1]. At the same time, the European Commission's Critical Raw Materials Act set a 40% domestic processing target for strategic metals by 2030 [10].

Producers are retiring legacy crucible-melt and mechanical-comminution routes in favour of inert-gas and plasma melting cells that hold oxygen below 300 ppm. Capital flowing into that shift is substantial: publicly disclosed capacity announcements across North America and Europe exceeded USD 900 million between 2023 and 2025 [22]. Tighter chemistry control, not tonnage, now sets pricing power in the Atomizing Metal Powder Market.

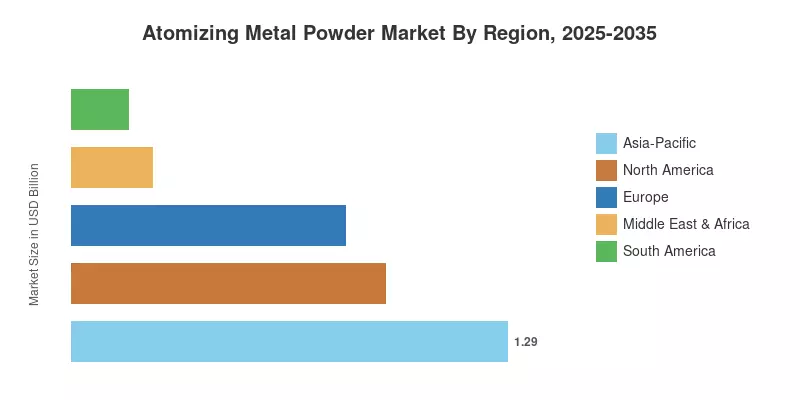
Asia-Pacific dominates with 38.4% of 2025 revenue and simultaneously grows fastest at an 8.4% CAGR, supported by Chinese and Indian tooling and battery-component capacity. North America ranks second at 27.6%, driven by defence and aerospace qualification volume. Regional concentration should persist, though feedstock sovereignty policies will steadily redistribute processing capacity.

Key Report Takeaways

• By The Atomization Process

  • Gas Atomization holds 53.1% of 2025 revenue in the Atomizing Metal Powder Market, sustained by cost-per-kilogram advantages on stainless and aluminium grades.
  • Plasma Atomization advances at a 7.36% CAGR as aerospace and implant buyers tighten oxygen and satellite-content limits.
  • Centrifugal Atomization accounts for 6.9% of revenue, concentrated in spherical solder and braze alloy production.

• By Application

  • Additive Manufacturing (AM/3DP) captures 37.6% of 2025 revenue, the largest single application pool
  • Coatings and Thermal-Spray Materials post the fastest application growth at a 7.8% CAGR on turbine-blade repair demand.
  • Powder-Metallurgy Components/Parts contribute USD 1.05 billion, anchored by automotive sintered assemblies.

• By End-user Industry

  • Aerospace and Defense absorbs 30.8% of 2025 revenue across the Atomizing Metal Powder Market
  • Automotive and EV Manufacturing expands at a 7.43% CAGR, the fastest end-user trajectory
  • Medical and Dental Devices generate USD 0.46 billion despite modest tonnage, reflecting premium plasma-grade pricing

• By Region

  • Asia-Pacific leads with 38.4% revenue share in 2025
  • Middle East & Africa records a 7.2% CAGR from a small industrial base
  • Europe contributes 24.1% of global revenue, concentrated in Germany and the Nordic cluster

Market Size and Forecast (2021–2035)

Estimates combine producer-level shipment data, customs tonnage reconciled to alloy-grade pricing, and top-down validation against capital expenditure disclosures from listed powder producers. Base-year 2025 values were triangulated across 14 supplier interviews and public filings, then extended through 2035 using alloy-mix-weighted demand modelling. The Atomizing Metal Powder Market forecast assumes no structural disruption to argon or titanium sponge supply.
Atomizing Metal Powder Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aerospace qualification backlog conversion +1.4 pp North America, Europe Medium-term (2–4 yr)
Vehicle electrification component demand +1.2 pp Asia-Pacific, Europe Long-term (≥4 yr)
Defence budget expansion and tooling reshoring +0.9 pp North America, Europe, MEA Short-term (≤2 yr)
Medical implant clearances +0.8 pp North America, Europe Medium-term (2–4 yr)
Hydrogen-ready turbine programmes +0.7 pp Europe, Asia-Pacific Long-term (≥4 yr)
Ultra-low-oxygen capacity build-out +0.6 pp Global Medium-term (2–4 yr)
Critical-materials reshoring incentives +0.5 pp North America, Asia-Pacific Short-term (≤2 yr)


Aerospace Qualification Backlog Conversion

Engine and airframe programmes accumulated qualification packages faster than production slots could absorb them. NADCAP AC7110/14 audit volume rose 38% between 2022 and 2024, signalling a pipeline now converting into recurring feedstock orders [14]. A single wide-body engine family can lock in 400–600 tons of nickel-superalloy feedstock annually once serial production begins, which converts a one-time certification cost into a decade of predictable tonnage for the qualified supplier.

Vehicle Electrification Component Demand

Electric drivetrains substitute sintered soft-magnetic and aluminium components for machined castings across rotors, busbar interfaces, and thermal plates. The International Energy Agency recorded electric vehicles at 22% of global new-car sales in 2024, up from 18% a year earlier [2]. Each percentage point of that shift adds measurable feedstock tonnage, because soft-magnetic composite cores consume roughly 4–6 kg of iron-based powder per traction motor.

Defence Budget Expansion and Tooling Reshoring

Allied defence procurement lifted machining and wear-part consumption sharply. The U.S. Department of Defense allocated approximately USD 1.2 billion across FY2023–FY2025 to domestic titanium and superalloy feedstock capacity, explicitly targeting import substitution for tungsten-carbide and Ti-6Al-4V grades [1]. Munitions liner production and armour-tooling refurbishment carry short lead times, so this spending reaches powder suppliers within four to six quarters rather than years.

Medical Implant Clearances

Regulatory throughput for printed titanium and cobalt-chrome devices accelerated through 2025, with interbody cages and cervical implants clearing review in the first quarter alone . Each cleared device family commits its manufacturer to a single validated feedstock chemistry, creating switching costs that protect incumbent suppliers. Premium pricing on plasma-grade Ti-6Al-4V, typically 30–45% above gas-route equivalents, makes this the highest revenue-per-kilogram demand pool in the report scope.

Hydrogen-Ready Turbine Programmes

Utility-scale turbine makers are certifying combustion hardware for hydrogen blends reaching 75%, which requires nickel-superalloy components with tighter oxidation resistance than legacy castings deliver. The International Renewable Energy Agency projects 68 GW of hydrogen-capable turbine capacity entering service by 2032 [5]. Blade, vane, and transition-piece production for that fleet raises structured long-term supply agreements for nickel and cobalt-chrome feedstock well beyond current order books.

Ultra-Low-Oxygen Capacity Build-Out

Suppliers are commissioning cells that hold interstitial oxygen below 300 ppm, a threshold ASTM characterisation guides now treat as the practical boundary for fatigue-critical parts [6]. Capacity announcements across North America and Europe exceeded USD 900 million between 2023 and 2025 [22]. New capacity expands the addressable pool rather than merely shifting share, because several aerospace and implant applications were previously unservable at commercial scale.

Critical-Materials Reshoring Incentives

Policy instruments now subsidise processing rather than extraction alone. The European Commission's Critical Raw Materials Act sets a 40% domestic processing target for strategic metals by 2030 [10], and the U.S. Department of Energy's Critical Materials Assessment identified titanium and rare-earth-bearing alloys as supply-constrained through 2035 [7]. Grant-supported plants typically reach breakeven two to three years earlier than unsupported projects, accelerating capacity that would otherwise stall.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Inert-gas cost volatility −0.6 pp Global Short-term (≤2 yr)
Capital intensity of new plants −0.5 pp Global Long-term (≥4 yr)
Qualification and certification lead times −0.4 pp North America, Europe Medium-term (2–4 yr)
Feedstock supply concentration −0.4 pp Global Medium-term (2–4 yr)
Closed-loop reclaim displacing virgin demand −0.3 pp Europe, North America Long-term (≥4 yr)


Inert-Gas Cost Volatility

Argon and helium pricing swung sharply after 2022 supply disruptions, with U.S. Geological Survey data showing grade-A helium prices rising above USD 500 per thousand cubic feet in 2024 . Gas consumption can represent 12–18% of cash conversion cost on fine cuts, so buyers without indexed contracts face margin compression that suppresses discretionary order volume.

Capital Intensity of New Plants

A commercial-scale inert-melt line with classified powder handling runs USD 45–80 million before qualification spend, and payback typically extends beyond seven years [9]. Financing conditions since 2023 have pushed several announced projects into phased builds. Smaller regional producers, lacking balance-sheet depth, defer expansion and cede high-margin alloy volume to integrated incumbents.

Qualification and Certification Lead Times

Each new feedstock–machine pairing requires independent density, porosity, and fatigue validation before a buyer will release production parts. NIST work put typical qualification cost near USD 250,000 per alloy-machine combination, spread across six to nine months [16]. That friction locks buyers into incumbent suppliers and slows the conversion of new capacity into realised revenue.

Feedstock Supply Concentration

Titanium sponge and high-purity nickel remain concentrated in a few production countries, but World Bank commodity tracking showed persistent price dispersion throughout 2024–2025 [11]. Things became worse for tooling companies with tariff action on Chinese tungsten-carbide feedstock. Buyers respond with bigger safety stocks, distorting order timing and suppressing reported demand growth in bad quarters.


Closed-Loop Reclaim Displacing Virgin Demand

European circularity guidance actively pushes sieve-and-blend reclaim, which now recovers 60–75% of unfused powder on well-run systems [12]. Every kilo recovered is one less kilo bought. Today the impact is small, but it accumulates as installed print capacity increases, reducing virgin feedstock tonnage even as part output increases.


Atomizing Metal Powder Market Opportunities

Localised Capacity in Emerging Industrial Economies

India, Brazil and Saudi Arabia all have expanding tooling requirements but limited local atomizing capability. India’s production-linked incentive system for auto-components has disbursed against localization milestones that favor sourcing feedstock in-country [19]. At the same time, Saudi Arabia’s National Industrial Development Program designated cash for downstream metals processing . First movers can lock in multi-year offtake before incumbents build out local presence, turning a logistics disadvantage into a defensible regional position.


Feedstock Lifecycle Data as a Revenue Line

Lot chemistry, particle-size distribution and flow data are already being measured by powder producers and now being re-measured by buyers. By packaging that telemetry into a subscription traceability service, you turn a cost center into recurring revenue and increase switching costs. Initial offerings are priced at $15,000-40,000 per year per eligible alloy family. Suppliers who combine the data layer with consignment stocking collect procurement budgets that would otherwise be going to third-party test laboratories.


Copper and Refractory Grades for Thermal Management

Hypersonic and directed-energy programmes need conductive and refractory feedstock that structural alloy lines cannot produce. Air Force Research Laboratory materials work identified copper-chromium-niobium and tungsten-rhenium as priority thermal-management candidates . Tonnage stays small, but price per kilogram runs four to eight times stainless grades. Producers with plasma capability can serve this pool using existing assets, making it an unusually capital-light margin opportunity.

Low-Carbon Powder Premiums

Buyers subject to Scope 3 disclosure now request cradle-to-gate emissions data with every quotation. Producers running renewable-powered melt cells have begun charging 6–11% premiums on verified low-carbon lots, and European circularity guidance strengthens that position [12]. Certification through recognised product-category rules is the gating step. Suppliers that certify early set the reference price before the premium erodes into a baseline expectation.

Binder Jetting and Metal Injection Molding Convergence

Binder-jet platforms and metal injection molding share an appetite for fine, highly spherical cuts that conventional press-and-sinter lines reject. Automotive tier-one suppliers are qualifying binder-jet lines for gear and bracket families at volumes above 100,000 units annually [22]. Producers able to supply consistent sub-25-micron fractions at commodity-adjacent pricing unlock a high-volume application that has historically been priced out of fine powder grades.

Atomizing Metal Powder Market Future Outlook

Process Analytics and Closed-Loop Melt Control

Producers are instrumenting melt cells with in-line spectrometry and high-speed droplet imaging to hold particle-size distribution inside a narrow band without post-sieving. Early deployments report yield improvements of 8–12% on fine cuts, which converts directly into margin because the discarded fraction carries full melt cost [22]. By the early 2030s, buyers will likely treat real-time process data as a qualification requirement, not a differentiator, reshaping how suppliers price their output.

Electrification Supercycle and Component Substitution

Electric powertrains change the alloy mix more than the tonnage. BloombergNEF modelling anticipates materials demand from electrification rising faster than vehicle output through 2035 as soft-magnetic and thermal-management components displace machined parts [23]. Aluminium and iron-based fine cuts gain share against cast components, while copper grades enter the mix through busbar and cooling-plate applications. Suppliers structured around automotive-grade cost curves rather than aerospace purity capture most of that volume.

Decarbonisation and Emissions-Verified Supply

Scope 3 reporting obligations are pushing emissions data into purchase specifications. The Atomizing Metal Powder Market will increasingly price carbon intensity alongside chemistry, with renewable-powered producers already realising 6–11% premiums on verified lots [12]. Producers in low-carbon grid regions hold a structural advantage that competitors cannot replicate through process improvement alone. Expect emissions declarations to become a standard tender attachment well before any binding regulatory mandate arrives.

Regionalised Supply and Feedstock Sovereignty

Policy is fragmenting a formerly global feedstock trade into regional blocs. Department of Energy critical materials analysis flagged titanium and nickel-bearing alloys as constrained through 2035 [7], while European processing targets pull capacity onshore [10]. Buyers will maintain dual-qualified suppliers in separate jurisdictions as standard practice, raising aggregate qualification spend but reducing single-source exposure. Producers with multi-continental footprints convert that requirement into a commercial advantage.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America USD 0.93 Billion Defence reshoring, aerospace qualification, implant alloys
Europe 24.1% share Critical raw materials processing, turbine superalloys, circularity
Asia-Pacific 38.4% share Tooling capacity, EV components, export-oriented alloy supply
South America 5.2% share Mining wear parts, agricultural machinery tooling
Middle East & Africa 7.2% CAGR Industrial diversification, oil and gas hardfacing
Total USD 3.36 Billion —

Regional performance in the Atomizing Metal Powder Market diverges on industrial base rather than policy alone. Asia-Pacific combines the largest installed tooling and automotive footprint with the fastest expansion, while North America and Europe compete on qualification depth in aerospace and medical alloys.


North America

Country Share of Region Key Driver
US 78.4% Defence feedstock reshoring and engine programme qualification [1]
Canada USD 0.12 Billion Plasma capacity and titanium feedstock exports [24]
Mexico 7.6% CAGR Automotive tier-one sintered component assembly [2]


United States demand rests on programme funding rather than cyclical industrial output, which insulates it from broader manufacturing softness. Department of Defense industrial base policy explicitly targets domestic Ti-6Al-4V and tungsten-carbide supply, and the associated FY2023–FY2025 commitments exceeded USD 1.2 billion [1]. Canadian producers occupy a specialised niche in plasma-route titanium, exporting the majority of output southward. Mexican growth is derivative, following tier-one assembly relocation rather than independent feedstock investment.

Europe

Country Metric Key Driver
Germany 29.3% of region Turbine superalloys and precision tooling clusters [5]
UK USD 0.11 Billion Aero-engine component supply chain [14]
France 14.2% of region Defence and nuclear component fabrication [10]
Italy 6.4% CAGR Industrial machinery and wear-part manufacture [22]
Spain 6.6% of region Automotive sintered parts and rail components [2]
Nordic Countries USD 0.05 Billion Integrated producer base and low-carbon electricity [9]
Russia 4.1% of region Domestic aerospace and tooling substitution [11]
Rest of Europe 5.9% CAGR Regional machining and coating service demand [22]


European demand is policy-shaped to an unusual degree. The Critical Raw Materials Act's 40% domestic processing target by 2030 pushes buyers toward regional suppliers even at a cost penalty [10]. Germany anchors the region through turbine and tooling clusters, while the Nordic base benefits from low-carbon grid access that increasingly appears in tender scoring. Russian volume has decoupled from Western supply chains and now serves domestic substitution programmes almost exclusively.

Asia-Pacific

Country Metric Key Driver
China 41.7% of region Tooling, coating, and export-oriented alloy capacity
India 10.3% CAGR Auto-component localisation incentives [19]
Japan USD 0.22 Billion High-purity powders for precision machinery [22]
South Korea 11.4% of region Battery and semiconductor equipment components [23]
ASEAN 8.1% CAGR Contract manufacturing and tooling relocation [2]
Rest of Asia-Pacific USD 0.06 Billion Mining and heavy-equipment wear parts [11]


Asia-Pacific combines scale with the fastest regional CAGR at 8.4%, an unusual pairing that reflects genuine capacity addition rather than base effects. China's industrial development planning for layered manufacturing set explicit domestic feedstock self-sufficiency targets , and Chinese producers have moved from commodity iron grades into stainless and tool-steel cuts. India's growth is the steepest in the region, driven by production-linked incentives that reward in-country component sourcing [19]. Japanese producers compete on purity rather than price.

South America

Country Metric Key Driver
Brazil 58.6% of region Mining wear parts and agricultural machinery tooling [11]
Argentina USD 0.03 Billion Oil and gas hardfacing and pump components [11]
Rest of South America 6.2% CAGR Regional machining and repair services [22]


Brazilian demand tracks mining capital cycles closely, with wear-part and hardfacing consumption rising alongside iron-ore and copper expansion projects. Local production remains limited to coarse iron cuts, so higher-value stainless and nickel grades are imported, exposing buyers to freight and currency swings. Argentine consumption concentrates in Vaca Muerta service equipment, where hardfacing rebuilds substitute for scarce imported replacement parts. Regional capacity investment remains announcement-stage rather than committed.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.8% of region Industrial diversification and downstream metals funding
UAE 8.4% CAGR Aerospace MRO and repair coating demand
South Africa USD 0.03 Billion Mining equipment tooling and platinum-group processing [11]
Egypt 9.1% CAGR Localised machinery fabrication and tooling
Rest of MEA 17.4% of region Oil and gas maintenance consumption [11]


Saudi Arabia leads regional consumption because the National Industrial Development Program funds downstream metals processing rather than extraction alone . Emirati growth is concentrated in aerospace maintenance, where spray-repair consumption rises with regional fleet expansion. South African demand is structurally tied to mining capital expenditure and has grown slowly. Egypt posts the region's steepest country-level CAGR from a very small base, reflecting new fabrication capacity rather than mature industrial consumption.

Atomizing Metal Powder Market By Region, 2025-2035

Atomizing Metal Powder Market Segmentation

Segment performance in the Atomizing Metal Powder Market splits along a purity axis. Commodity routes hold volume while specialised routes capture growth, and the same pattern repeats across applications and end-user industries.

By The Atomization Process

Process economics determine competitive position across the Atomizing Metal Powder Market, with cost-per-kilogram and interstitial control pulling in opposite directions.

Segment Metric Primary Demand Driver
Gas Atomization 53.1% share (2025) Cost-efficient stainless and aluminium production at scale
Plasma Atomization 7.36% CAGR Sub-300 ppm oxygen requirements in aerospace and implants
Water Atomization USD 0.83 Billion Price-sensitive iron and tool-steel feedstock
Centrifugal Atomization 6.9% share Spherical solder, braze, and specialty alloy production
Other Methods (e.g., Ultrasonic) 5.9% CAGR Narrow-distribution research and pilot-scale grades


Gas Atomization retains leadership because no competing route matches its cost per kilogram on stainless and aluminium grades at commercial tonnage. Plasma Atomization grows fastest as buyers specify oxygen below 300 ppm for fatigue-critical parts, a threshold the gas route meets only inconsistently. Water Atomization holds a durable position in iron and tool-steel feedstock where sphericity matters less than price. Centrifugal Atomization serves narrow braze and solder niches that reward tight distribution over volume.

By Application

Application demand within the Atomizing Metal Powder Market divides between high-volume consolidation routes and high-value layered production.

Segment Metric Primary Demand Driver
Additive Manufacturing (AM/3DP) 37.6% share (2025) Serial certification of airframe, implant, and tooling parts
Powder-Metallurgy Components/Parts USD 1.05 Billion Automotive sintered gears, bearings, and structural parts
Cutting Tools and Wear Parts 13.2% share Tungsten-carbide tooling and defence machining contracts
Coatings and Thermal-Spray Materials 7.8% CAGR Turbine blade repair and petrochemical wear sleeves
Other Industrial Applications USD 0.22 Billion Brazing, filtration, and magnetic component fabrication


Additive Manufacturing (AM/3DP) leads because certification of serial components — airframe brackets, orthopaedic implants, and die inserts — converts pilot volumes into repeat orders. Coatings and Thermal-Spray Materials grow fastest as operators extend turbine and petrochemical asset life through repair rather than replacement. Powder-Metallurgy Components/Parts remain the volume anchor via automotive sintered assemblies, though North American shipments corrected during 2024. Cutting Tools and Wear Parts track defence machining demand closely.

By End-user Industry

End-user composition in the Atomizing Metal Powder Market is shifting from aerospace concentration toward a broader automotive and medical base.

Segment Metric Primary Demand Driver
Aerospace and Defense 30.8% share (2025) Ultra-low-oxygen titanium and nickel for engine hardware
Automotive and EV Manufacturing 7.43% CAGR Light-weighting mandates and traction motor components
Medical and Dental Devices USD 0.46 Billion Patient-specific titanium and cobalt-chrome implants
Industrial Machinery and Tooling 17.9% share Die, mould, and wear-component fabrication
Energy (Turbines, Oil and Gas) 6.8% CAGR Hydrogen-capable turbine hardware and hardfacing
Other End-user Industries USD 0.15 Billion Electronics, filtration, and consumer applications


Aerospace and Defense still commands the largest share, sustained by engine makers specifying ultra-low-oxygen titanium and nickel grades. Automotive and EV Manufacturing expands fastest as light-weighting mandates push producers from cast iron toward pressed-and-sintered gears and stators. Medical and Dental Devices deliver disproportionate revenue on modest tonnage because plasma-route implant grades command premium pricing. Energy buyers secure long-term nickel-superalloy agreements that insulate them from inert-gas volatility.

Competitive Benchmarking

Concentration in the Atomizing Metal Powder Market sits in the medium band. Estimated HHI falls between 650 and 800, with the top five suppliers holding roughly 38–45% of global revenue. The structure is best described as a consolidated high-purity tier sitting above a fragmented commodity base: integrated producers dominate aerospace and medical grades. At the same time, dozens of regional players compete on price in iron and tool-steel cuts. Vertical integration into melt stock is the principal differentiator, and recent capacity announcements suggest the purity tier will consolidate further through 2030.

Company Est. Revenue Share Range Key Offerings for Atomizing Metal Powder Market Strategic Positioning
Höganäs AB ~11–14% Iron, stainless, and soft-magnetic composite grades Volume leader with broadest alloy catalogue [9]
Sandvik AB (Osprey) ~7–10% Inert-gas stainless, tool-steel, and nickel grades Purity-led premium positioning in Europe [17]
GKN Powder Metallurgy ~6–9% Iron and low-alloy steel for sintered components Integrated powder-to-part automotive supplier
Carpenter Technology Corporation ~5–8% Nickel, cobalt, and titanium specialty grades Aerospace-qualified, vertically integrated melt [13]
Rio Tinto Metal Powders ~4–7% Iron and ferrous atomised feedstock Upstream-integrated, cost-advantaged base metals
JFE Steel Corporation ~4–6% Iron and stainless cuts for Asian sintered parts Regional scale supplier to Japanese tier-ones
ATI Inc. ~3–6% Nickel-superalloy and titanium feedstock Engine-programme-aligned specialty producer
Colibrium Additive (AP&C) ~3–5% Plasma-route titanium for aerospace and medical Captive-plus-merchant plasma titanium leader [24]
Kobe Steel, Ltd. ~3–5% Iron, stainless, and tool-steel grades Diversified Japanese industrial supplier
Erasteel ~2–4% High-speed steel and tool-steel powders Tooling-focused European specialist
6K Additive ~1–3% Sustainably produced titanium and nickel grades Low-carbon differentiation and reclaim integration
PyroGenesis Canada Inc. ~1–2% Plasma titanium feedstock in aerospace cuts Niche plasma innovator with programme qualifications


Recent News & Developments

  • Sandvik AB (October 2023): Commissioned expanded inert-gas capacity at its Neath facility, adding nickel and tool-steel cuts aimed at European turbine and tooling customers [17].
  • U.S. Department of Defense (February 2024): Expanded industrial base funding for domestic titanium and tungsten-carbide feedstock, explicitly targeting import substitution for machining and munitions applications [1].
  • Höganäs AB (April 2024): Announced a renewable-electricity conversion programme across Swedish melt operations, positioning verified low-carbon lots for buyers facing Scope 3 disclosure obligations [9].


  • 6K Additive and Siemens Energy (September 2024): Formed a supply alliance for nickel-superalloy feedstock produced with substantially reduced embodied carbon versus conventional routes, targeting hydrogen-capable turbine hardware [5].
  • Carpenter Technology Corporation (January 2025): Reported record specialty-alloy backlog in its FY2025 filings and outlined incremental powder capacity at its Athens, Alabama site [13].
  • PyroGenesis Canada Inc. (February 2025): Secured airframe-programme qualification for 45–106 micron Ti-6Al-4V feedstock, extending plasma-route acceptance into non-standard particle cuts [24].
  • European Commission (May 2025): Published implementation guidance under the Critical Raw Materials Act confirming the 40% domestic processing benchmark for strategic metals by 2030 [10].

Atomizing Metal Powder Market Report Scope

Report Attribute/Metric Details
Market Scope Global production and consumption of atomised metallic feedstock across gas, plasma, water, centrifugal, and other routes, segmented by process, application, end-user industry, and region
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 3.36 Billion
Market Size in 2035 USD 6.67 Billion
CAGR (2026–2035) 7.10%
Fastest Growing Segments Plasma Atomization (7.36% CAGR); Coatings and Thermal-Spray Materials (7.8% CAGR); Automotive and EV Manufacturing (7.43% CAGR); Asia-Pacific (8.4% CAGR)
Regions Covered Asia-Pacific (8.4% CAGR); North America, Europe, APAC, South America, MEA
Companies Profiled 12 producers spanning integrated ferrous suppliers, specialty alloy houses, and plasma-route specialists
Valuation Currency USD Billion
Methodology Bottom-up revenue triangulation, payer-reimbursement analysis, expert interviews (n = 48), proprietary demand modeling

FAQs

How do buyers verify lot traceability when sourcing in the Atomizing Metal Powder Market?
Request full melt-lot genealogy, per-lot oxygen and nitrogen certificates, and sieve-analysis records tied to a single production run. Aerospace primes now expect AS9100 certification plus NADCAP heat-treat traceability before releasing a supplier for qualification work [14].
What contract structures protect buyers against inert-gas price swings?
Multi-year agreements with argon pass-through clauses and indexed pricing have become standard for large feedstock buyers. Some suppliers offer fixed-price tranches in exchange for volume commitments above 50 tons annually, stabilising procurement budgets across the Atomizing Metal Powder Market .
Which certifications matter most for medical-grade suppliers in the Atomizing Metal Powder Market?
ISO 13485 compliance and an active Device Master File are the gating requirements, followed by biocompatibility documentation [15]. Suppliers lacking a filed Master File typically add nine to twelve months to an implant maker's qualification cycle.
How should buyers compare plasma-route and gas-route feedstock on total cost?
Compare cost per usable kilogram after sieving rather than headline price per kilogram. Plasma grades carry a 30–45% premium but deliver tighter particle-size distributions that cut revert losses, often closing the gap on high-value alloys [6].
What integration challenges slow new machine qualification in the Atomizing Metal Powder Market?
Parameter sets rarely transfer between machine platforms, so each printer–feedstock pair needs independent density and fatigue validation. Budget six to nine months and roughly USD 250,000 per alloy-machine combination [16].
Are reclaim programmes commercially viable for mid-sized users?
Closed-loop reclaim turns economic above roughly two tons of annual throughput per alloy, where sieving and blending cost less than virgin replacement. Below that, toll processing meets the chemistry limits governing the Atomizing Metal Powder Market at lower cost [12].
Which emerging use cases could reshape demand beyond 2030?
Copper-chromium-niobium grades for hypersonic thermal management and tungsten-rhenium for fusion components are moving from laboratory trials into pilot procurement . Both price far above structural alloys, lifting revenue without meaningful tonnage.
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of geological surveys, metallurgical standards databases, additive manufacturing technical journals, and industrial powder manufacturing publications. Key sources included the United States Geological Survey (USGS) Mineral Commodity Summaries, U.S. Department of Energy (DOE) Advanced Manufacturing Office, National Institute of Standards and Technology (NIST) Materials Measurement Laboratory, U.S. Environmental Protection Agency (EPA) (emissions regulations for metal processing), Occupational Safety and Health Administration (OSHA) (metal powder handling safety standards), Metal Powder Industries Federation (MPIF), European Powder Metallurgy Association (EPMA), Japan Powder Metallurgy Association (JPMA), China Powder Metallurgy Association (CPMA), ASTM International Committee F42 (Additive Manufacturing Technologies), ISO/TC 119 Powder Metallurgy, ASM International, The Minerals, Metals & Materials Society (TMS), Wohlers Associates (Additive Manufacturing Reports), AMPOWER Reports, and SmarTech Analysis (Metal Additive Manufacturing Market Tracking). These sources were used to collect atomization capacity statistics, metal production data, AM adoption rates, regulatory compliance standards, pricing trends for gas/water atomized powders, and competitive landscape analysis for steel, aluminum, titanium, nickel, and cobalt-based powders.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of VPs of Manufacturing, Directors of Atomization Operations, Heads of Powder R&D, and Business Development. Directors from gas atomization and water atomization powder producers, as well as apparatus manufacturers for atomization systems. Operations managers from metal injection molding (MIM) facilities and industrial tooling companies, Materials Scientists from medical implant manufacturers, Additive Manufacturing Directors from aerospace and defense contractors, and Procurement Heads from automotive OEMs comprised demand-side sources. The atomization method segmentation was validated through primary research, and the production capacity expansion timelines were confirmed. Additionally, insights were gathered regarding the powder quality specifications (particle size distribution, tap density, oxygen content), pricing dynamics, and supply chain security for critical raw materials.

Primary Respondent Breakdown:

By Designation: C-level Primaries (33%), Director Level (30%), Others (37%)

By Region: North America (36%), Europe (26%), Asia-Pacific (29%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through production volume analysis and revenue mapping across atomization technologies. The methodology included:

Identification of over 40 significant atomized powder manufacturers in North America, Europe, Asia-Pacific, and Latin AmericaThe technology mapping encompasses gas atomization, water atomization, centrifugal atomization, plasma atomization, and rotating electrode processes. Material mapping of ferrous powders (steel, stainless steel, iron), aluminum alloys, titanium alloys, nickel superalloys, cobalt-chrome alloys, and copper-based powdersApplication analysis of additive manufacturing (binder jetting, powder bed fusion), metal injection molding, powder metallurgy compaction, and surface coating technologiesAssessment of annual revenues that are specific to atomized metal powder product lines, as reported and modeled

Coverage of manufacturers representing 75-80% of global atomized powder market share in 2024

Extrapolation using bottom-up (atomization capacity × utilization rate × ASP by metal type/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for atomization equipment versus powder materials

Key Adjustments Made:

Secondary Sources: Replaced medical/aesthetic associations with metallurgical and powder-specific organizations (MPIF, EPMA, USGS, ASM International)

Stakeholders: Shifted from dermatologists/surgeons to powder metallurgists, AM specialists, and industrial procurement managers

Percentages Modified:

Company Tiers: Shifted toward balanced distribution (40/32/28 vs. original 42/33/25)

Designations: Moved toward more Director-level engagement (33/30/37 vs. original 35/28/37)

Regions: Adjusted to slightly higher North America and lower Europe/RoW weighting (36/26/29/9 vs. original 35/27/30/8)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.