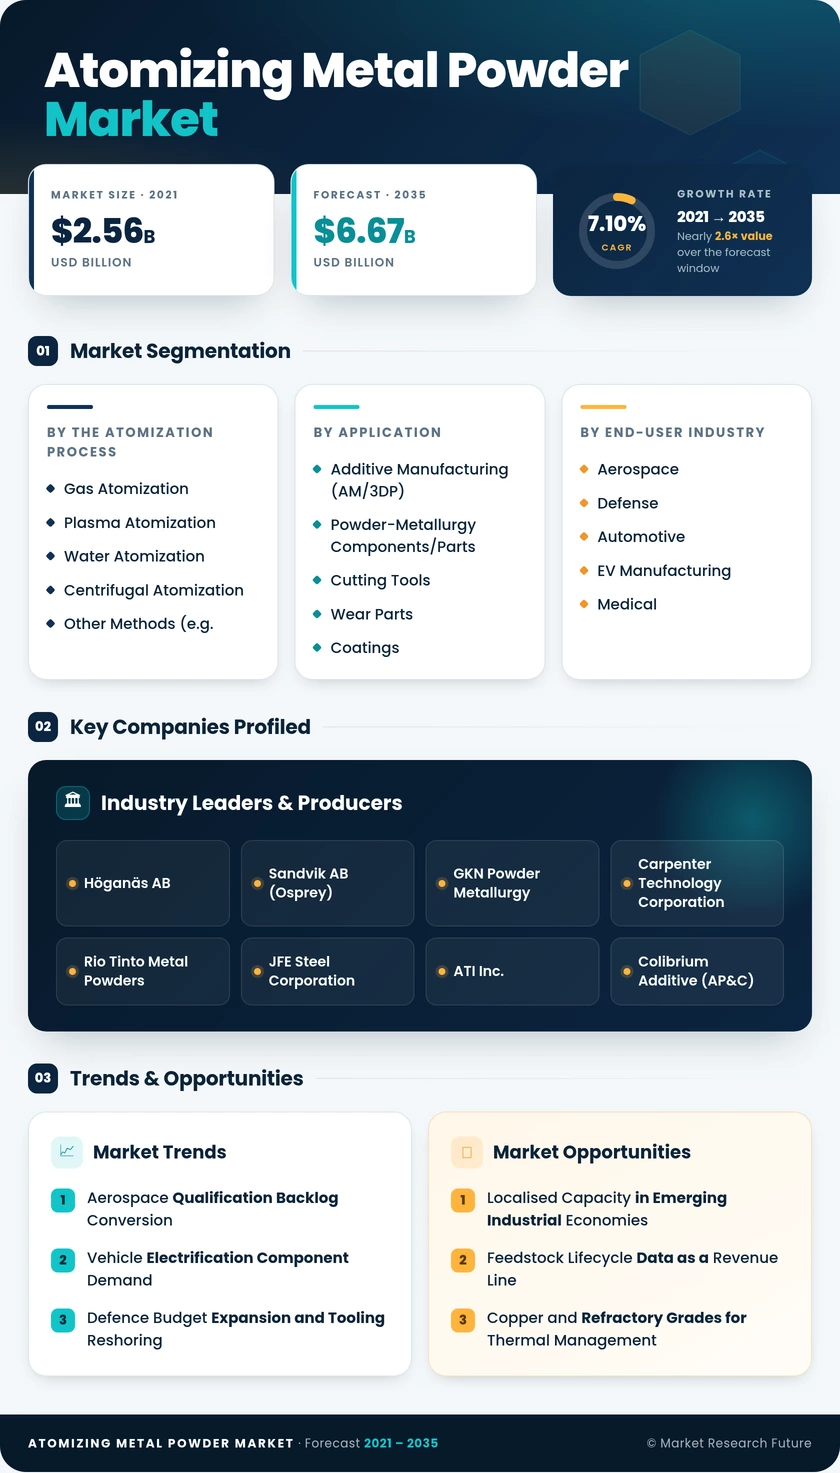
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By The Atomization Process | Gas Atomization; Plasma Atomization; Water Atomization; Centrifugal Atomization; Other Methods (e.g., Ultrasonic) | Gas Atomization (53.1% share, 2025) | Plasma Atomization (7.36% CAGR) |
| By Application | Additive Manufacturing (AM/3DP); Powder-Metallurgy Components/Parts; Cutting Tools and Wear Parts; Coatings and Thermal-Spray Materials; Other Industrial Applications | Additive Manufacturing (AM/3DP) (37.6% share, 2025) | Coatings and Thermal-Spray Materials (7.8% CAGR) |
| By End-user Industry | Aerospace and Defense; Automotive and EV Manufacturing; Medical and Dental Devices; Industrial Machinery and Tooling; Energy (Turbines, Oil and Gas); Other End-user Industries | Aerospace and Defense (30.8% share, 2025) | Automotive and EV Manufacturing (7.43% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (38.4% share) | Asia-Pacific (8.4% CAGR) |
Market Segmentation Overview
By The Atomization Process
| Sub-Segment | Key Trend |
|---|---|
| Gas Atomization | Helium-argon blend optimisation lowers cost per kilogram on stainless and aluminium cuts |
| Plasma Atomization | Capacity additions target sub-300 ppm oxygen for fatigue-critical components |
| Water Atomization | Remains the default route for price-led iron and tool-steel feedstock |
| Centrifugal Atomization | Narrow-distribution output serves braze, solder and specialty alloy niches |
| Other Methods (e.g., Ultrasonic) | Pilot-scale adoption where extremely tight distributions justify low throughput |
Gas Atomization holds 53.1% of 2025 revenue because its cost per kilogram on stainless and aluminium remains unmatched at commercial tonnage, and buyers of non-critical parts have no incentive to pay for tighter interstitials. Plasma Atomization grows fastest at 7.36% as engine and implant specifications push oxygen below 300 ppm, a limit the gas route meets only inconsistently on fine cuts. Water Atomization retains a defensible base in iron and tool-steel feedstock where sphericity is secondary to price, while Centrifugal Atomization serves braze and solder niches that reward distribution control over scale.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Additive Manufacturing (AM/3DP) | Serial certification of airframe brackets, implants and die inserts drives repeat orders |
| Powder-Metallurgy Components/Parts | Automotive sintered gears and bearings anchor volume despite 2024 inventory correction |
| Cutting Tools and Wear Parts | Tungsten-carbide tooling demand tracks defence machining contracts |
| Coatings and Thermal-Spray Materials | Turbine blade repair and petrochemical wear sleeves extend asset life |
| Other Industrial Applications | Brazing, filtration and magnetic components provide diversified baseline demand |
Additive Manufacturing (AM/3DP) leads at 37.6% of 2025 revenue because certification converts pilot builds into standing orders, and each qualified part family locks in a single feedstock chemistry for years. Coatings and Thermal-Spray Materials advance fastest at 7.8% as turbine and petrochemical operators choose repair over replacement under capital discipline. Powder-Metallurgy Components/Parts remain the tonnage anchor through automotive sintered assemblies, contributing USD 1.05 billion, though North American shipments corrected during 2024 on inventory adjustment. Cutting Tools and Wear Parts move with defence machining award cycles rather than general industrial output.
By End-user Industry
| Sub-Segment | Key Trend |
|---|---|
| Aerospace and Defense | Ultra-low-oxygen titanium and nickel demand tied to engine programme ramps |
| Automotive and EV Manufacturing | Light-weighting mandates shift gears and stators from cast iron to sintered routes |
| Medical and Dental Devices | Patient-specific titanium and cobalt-chrome implants command premium pricing |
| Industrial Machinery and Tooling | Die, mould and wear-component fabrication provides stable baseline consumption |
| Energy (Turbines, Oil and Gas) | Hydrogen-capable turbine hardware secures long-term superalloy agreements |
| Other End-user Industries | Electronics, filtration and consumer uses add incremental diversification |
Aerospace and Defense commands 30.8% of 2025 revenue because engine makers specify interstitial limits that few suppliers can hold, concentrating spend among qualified producers. Automotive and EV Manufacturing grows fastest at 7.43% as light-weighting rules move gears and stators away from cast iron toward pressed-and-sintered routes, raising demand for medium-cost iron, steel and aluminium grades. Medical and Dental Devices deliver USD 0.46 billion on comparatively small tonnage, since plasma-route implant grades price well above structural alloys. Energy buyers lock multi-year superalloy contracts that buffer them from inert-gas volatility.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA