Agrochemicals Market (2026 - 2035)

Agrochemicals Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Fertilizers, Pesticides, Adjuvants, Plant Growth Regulators), By Crop Type (Grains and Cereals, Oilseeds and Pulses, Commercial Crops, Fruits and Vegetables, Turf and Ornamental), By Formulation (Liquid Concentrates, Granular and Solid, Water-Dispersible Formats), By Application Mode (Foliar Spray, Soil Treatment, Fertigation, Seed Treatment), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Forecast Till 2035

Forecast Period
2026-2035
CAGR
4.87%
2025 Market Size
USD 760.24 Million
2035 Market Size
USD 1,219.37 Million
Agriculture ● Updated August 24, 2026 Report ID: MRFR/Agri/0759-HCR | Pages: 128 | Author: Snehal Singh, Varsha More

Agrochemicals Market Summary

The Agrochemicals Market stood at USD 760.24 Million in 2025 and opens the forecast window at USD 794.83 Million in 2026, climbing to USD 1,219.37 Million by 2035 at a 4.87% CAGR. Two catalysts anchor that trajectory. Budget 2025 lifted federal food-security allocations to roughly RM 4.19 billion, routing grants into smallholder replanting and fertiliser subsidy pools that convert directly into input purchase orders [3]. Parallel residue-limit tightening under sustainability certification schemes is pushing growers off unregistered generics and toward registered, higher-value formulations [6].

Beneath the headline number, a quiet technology swap is underway. Knapsack sprayers and blanket broadcast application — labour-hungry, imprecise, and increasingly hard to staff — are giving way to drone-mounted spray rigs, controlled-release granules, and variable-rate injection systems. Field trials across plantation crops report input savings of 18–25% per hectare against conventional passes, and equipment vendors have committed capital accordingly [11][15].

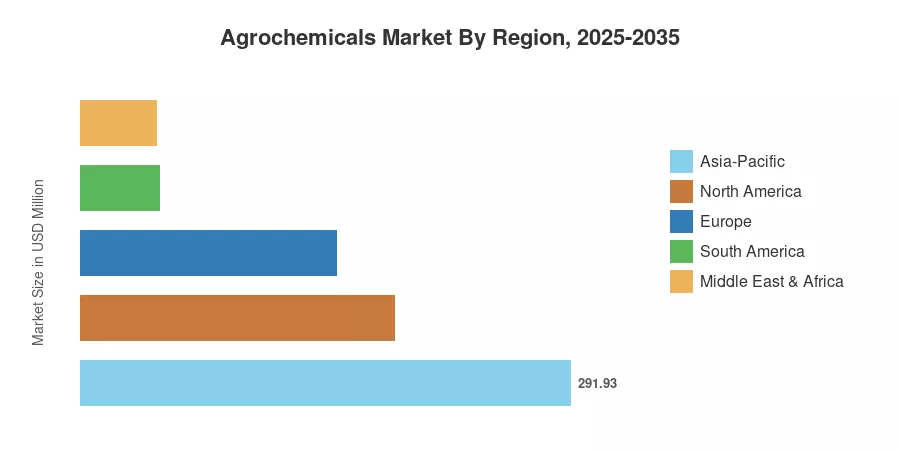
Regionally, Asia-Pacific holds 38.4% of the Agrochemicals Market on the strength of oil palm, rubber and paddy acreage. South America grows fastest at 6.18% CAGR, lifted by soybean expansion and reduced registration backlogs. North America follows as the second-largest bloc, where resistance pressure in corn and soy sustains premium chemistry demand. Expect the next decade of the Agrochemicals Market to reward formulation science over volume tonnage.


Key Report Takeaways

• By Product Type

  • Pesticides led the Agrochemicals Market with a 42.6% share in 2025, supported by year-round plantation spray cycles
  • Plant growth regulators are the fastest-expanding line at an 8.75% CAGR through 2035
  • Adjuvants contributed USD 70.70 million in 2025 as tank-mix optimisation moved mainstream

• By Crop Type

  • Commercial crops accounted for 32.85% of demand in 2025, reflecting estate-scale procurement discipline
  • Fruits and vegetables advanced at an 8.54% CAGR, the quickest crop-side trajectory in the Agrochemicals Market
  • Grains and cereals generated USD 200.70 million in 2025

• By Region

  • Asia-Pacific commanded a 38.4% share in 2025
  • South America posts the highest regional CAGR at 6.18%
  • Europe recorded USD 152.81 million, constrained by active-ingredient withdrawals


Market Size and Forecast (2021–2035)

Estimates below blend national trade statistics, plant-protection product registration databases, fertiliser consumption returns filed with agriculture ministries, and audited disclosures from the twelve largest suppliers active in the Agrochemicals Market. Historical years were reconciled against customs-level import tonnage before conversion to value at rolling annual average prices.
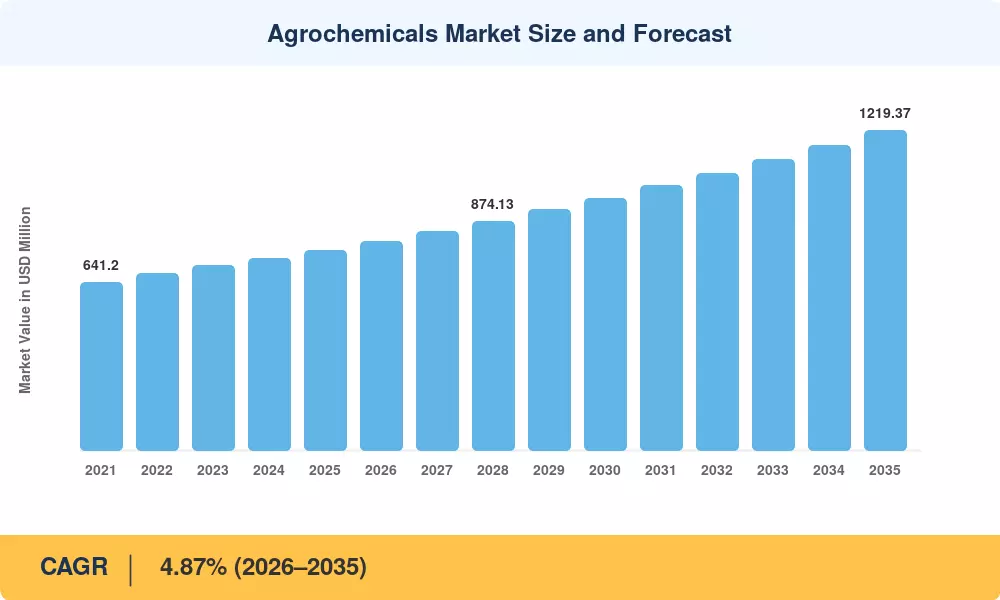
Agrochemicals Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Food-security budget allocations and input subsidies ~1.05% Asia-Pacific, MEA Short-term (≤2 yr)
Sustainability certification and residue-limit tightening ~0.86% Global Medium-term (2–4 yr)
Farm labour scarcity driving mechanised application ~0.74% Asia-Pacific, Europe Medium-term (2–4 yr)
Resistance pressure requiring new modes of action ~0.62% Americas Long-term (≥4 yr)
Horticulture and protected-cropping expansion ~0.55% Asia-Pacific, MEA Medium-term (2–4 yr)
Plantation replanting and rejuvenation programmes ~0.48% Asia-Pacific Long-term (≥4 yr)
Digital agronomy prescriptions lifting product mix value ~0.39% Global Long-term (≥4 yr)


Public Food-Security Spending Converts Straight Into Input Demand

Fiscal support remains the single most reliable demand floor in the Agrochemicals Market. Malaysia's Budget 2025 raised food-security allocation to RM 4.188 billion (about USD 1.01 billion), with dedicated envelopes for paddy fertiliser assistance and smallholder replanting [3]. India's nutrient-based subsidy outlay for 2024–25 exceeded INR 1.65 trillion, and Brazil's Plano Safra committed BRL 400.59 billion in rural credit, a share of which underwrites crop-protection purchases [7][20]. Where subsidy disbursement is digitised and tied to land records, leakage drops and measurable applied tonnage rises within one cropping season.

Certification Schemes Are Rewriting Product Qualification

Sustainability certification has become a de facto formulary. Under the Malaysian Sustainable Palm Oil scheme, certified estates must document product registration status and observe pre-harvest intervals, effectively excluding grey-channel supply [6]. The EU's maximum residue level revisions have cut import tolerances on several legacy actives to 0.01 mg/kg, forcing exporters to reformulate rather than reprice [5]. Compliance costs rise, but so does average selling price — certified estates in audited samples paid a 12–17% premium versus uncertified neighbours for equivalent actives.

Labour Scarcity Is Pulling Application Technology Forward

Plantation operators report harvester and sprayer vacancy rates above 20% across several Southeast Asian estates, and wage inflation has outpaced commodity price gains for three consecutive seasons [4]. Drone spraying answers both problems: a single operator covers 40–60 hectares per day against 4–6 hectares manually, and droplet-size control cuts drift losses. Regulators have responded — aerial application permitting frameworks now exist in most major producing economies, and equipment financing schemes have narrowed the payback window to under 18 months [11].


Restraints Impact Analysis

Restraint weightings are directional drag estimates assigned through the same analyst-scoring framework. They are not deductible line items against the reported CAGR and should be read comparatively across the Agrochemicals Market.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Active-ingredient withdrawals and re-registration burden ~0.71% Europe, North America Medium-term (2–4 yr)
Volatile ammonia, phosphate and energy feedstock costs ~0.58% Global Short-term (≤2 yr)
Counterfeit and unregistered product circulation ~0.44% Asia-Pacific, Africa Long-term (≥4 yr)
Smallholder affordability and credit constraints ~0.37% MEA, South Asia Medium-term (2–4 yr)
Public pressure and NGO-led restriction campaigns ~0.29% Europe Long-term (≥4 yr)


The Registration Treadmill Is Getting Steeper

Europe has removed or non-renewed more than 100 active substances since 2019, and the Farm to Fork target of halving chemical pesticide use by 2030 keeps the pipeline under review [5][18]. Each re-registration dossier now carries multi-year data-generation costs that mid-tier suppliers struggle to absorb, which paradoxically concentrates the field. Growers face shrinking rotation options precisely when resistance management demands more, not fewer, modes of action.

Counterfeits Erode Both Price and Trust

According to industry surveillance estimates, 12–18% of crop-protection goods are either unlawful or of poor quality in a number of high-growth regions [13]. The harmful substances include: distributors bear the burden of warranty claims, agrochemical regulatory compliance costs increase for the honest majority, and yield failures are attributed to valid chemistry. The developing solution is track-and-trace serialization rules, but outside of metropolitan distribution hubs, enforcement capability is still limited.


Feedstock Volatility Distorts Planning

Annual supply contracts are risky for both parties because ammonia and phosphate rock prices fluctuated by over 60% from peak to trough throughout the 2022–2024 window [16]. Shorter tenor pricing and surcharge provisions were the formulators' response, but the ensuing invoice uncertainty deters smallholder pre-purchase, which is the exact behaviour that stabilises seasonal demand.


Agrochemicals Market Opportunities

Biologicals as a Portfolio Hedge

Biological agrochemical alternatives now clear registration faster than synthetics in several jurisdictions, with reduced-risk pathways cutting review timelines by 30–40% [10]. For suppliers facing withdrawal exposure in Europe, this is a strategic hedge rather than a niche play.

Drone Application Services

Selling hectares treated, rather than litres shipped, converts a commodity transaction into a recurring service annuity. Operators bundling product, prescription and application capture 2.3× the gross margin of straight distribution [11][15].

Emerging-Market Smallholder Aggregation

Africa and South Asia together hold over 400 million smallholdings with input intensity far below global averages [1]. Cooperative aggregation platforms — pooling demand, financing and last-mile delivery — unlock volumes that direct-to-farm models cannot economically reach.

Data Monetisation From Application Records

Each recommended spray produces geotagged effectiveness statistics. An income stream unrelated to tonnage is created when suppliers license anonymised residue and resistance datasets to food processors, insurers, and certifying organizations [15].


Post-Patent Premiumisation

Roughly USD 4.2 billion of branded actives lose exclusivity before 2030 [12]. The opportunity is not generic price-matching but reformulation — encapsulation, adjuvant systems and combination products that reset the value conversation.


Agrochemicals Market Future Outlook

Autonomous Application Becomes Default

By 2032, autonomous ground rigs and swarm-capable drones should handle the majority of plantation spray hectares in the Agrochemicals Market's leading geographies. Vision-guided targeting has already cut herbicide volume by up to 77% in commercial green-on-green trials, shifting supplier revenue toward higher-concentration, drift-controlled formulations [15].

Prescription Platforms Reshape Distribution Economics

Agronomy software vendors increasingly sit between manufacturer and grower, owning the recommendation. Distributors that fail to secure a data position risk demotion to pure logistics — a margin structure that historically halves within five years of platform intermediation [15][19].

Carbon and Residue Reporting Enter Procurement

Food processors are extending Scope 3 disclosure requirements upstream, and nitrous oxide from fertiliser is a large, visible line. Suppliers offering verified low-emission nitrogen and documented residue profiles will command preferential shelf position well before regulation compels it [8][21].

Consolidation Around Formulation IP

Defensible value shifts from molecule to delivery mechanism, with almost USD 4.2 billion worth of active ingredients moving off-patent this decade [12]. Anticipate that purchase activity will focus on biological platform, adjuvant, and encapsulation assets rather than tonnage capacity.


Agrochemicals Market Segmentation

Segment behaviour across the Agrochemicals Market diverges sharply — volume sits in one place, growth in another.

By Product Type

Segment Metric (2025) Primary Demand Driver
Pesticides 42.6% share Year-round plantation pest pressure [4]
Fertilizers USD 317.78 Million Subsidy-backed nutrient programmes [7]
Adjuvants 6.92% CAGR Tank-mix efficiency optimisation [11]
Plant Growth Regulators 8.75% CAGR Yield timing and harvest uniformity [2]


Pesticides anchor the Agrochemicals Market because pest and disease pressure does not respect crop calendars in tropical systems — fungicide programmes on oil palm and rubber run continuously. Plant growth regulators, though small, grow fastest: ripening synchronisation and lodging control deliver measurable yield economics that estate managers can defend on a spreadsheet.

By Crop Type

Segment Metric (2025) Primary Demand Driver
Commercial Crops 32.85% share Estate-scale procurement discipline [4]
Grains and Cereals USD 200.70 Million Paddy and wheat intensification [1]
Oilseeds and Pulses 5.68% CAGR Soybean acreage expansion [20]
Fruits and Vegetables 8.54% CAGR Export residue compliance [2]
Turf and Ornamental 4.31% CAGR Urban landscaping budgets [2]


Commercial crops dominate the Agrochemicals Market on procurement structure alone — estates buy in tender lots with agronomist sign-off, producing predictable, high-specification demand. Fruits and vegetables grow faster because export buyers audit residue records, and passing an audit requires registered, traceable product rather than the cheapest available equivalent.

By Formulation

Segment Metric (2025) Primary Demand Driver
Liquid Concentrates 48.3% share Compatibility with mechanised spraying [11]
Granular and Solid USD 243.28 Million Controlled-release nutrient delivery [8]
Water-Dispersible Formats 7.14% CAGR Reduced operator exposure [9]


Formulation choice in the Agrochemicals Market increasingly follows equipment rather than chemistry. Drone tanks favour low-volume, high-concentration liquids; fertigation systems demand full solubility. Suppliers that ignore the application hardware roadmap find perfectly good actives locked out of the fastest-growing hectares.

By Application Mode

Segment Metric (2025) Primary Demand Driver
Foliar Spray 51.7% share Broadest crop and product compatibility [2]
Soil Treatment USD 178.16 Million Residual pest and nutrient management [8]
Fertigation 7.82% CAGR Water-scarce irrigated systems [2]
Seed Treatment 6.45% CAGR Early-stage protection economics [12]


Foliar spray applications dominate with a 51.7% share, driven by the broadest crop and product compatibility [2]. Meanwhile, soil treatments account for a market value of USD 178.16 million geared toward residual pest and nutrient management [8], whereas fertigation expands at a 7.82% CAGR tailored for water-scarce irrigated systems [2]. Finally, seed treatments grow at a 6.45% CAGR focused on early-stage protection economics [12].


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 24.6% share Resistance management, digital prescription platforms
Europe USD 152.81 Million Reformulation, biologicals conversion
Asia-Pacific 38.4% share Plantation replanting, drone application fleets
South America 6.18% CAGR Soybean acreage, registration throughput
Middle East & Africa 5.94% CAGR Protected cropping, irrigation-linked nutrition
Total USD 760.24 Million

Regional performance across the Agrochemicals Market tracks cropping intensity far more closely than farm income, which is why plantation and row-crop geographies dominate absolute value.


North America

Country Metric (2025) Key Driver
US 71.2% of region Corn and soybean resistance cycles [12]
Canada USD 23.19 Million Canola and pulse acreage [17]
Mexico 5.87% CAGR Horticultural export compliance [2]


Regulatory throughput defines the North American Agrochemicals Market. EPA registration review dockets and state-level restrictions create a two-speed environment where national approval no longer guarantees market access, and suppliers increasingly build state-specific label strategies into launch planning [9].

Europe

Country Metric (2025) Key Driver
Germany USD 32.61 Million Cereal intensification [18]
UK 13.6% of region Post-exit registration divergence [5]
France 4.42% CAGR Ecophyto reduction targets [18]
Italy USD 16.80 Million Viticulture fungicide demand [2]
Spain 10.9% of region Irrigated horticulture [2]
Nordic Countries 3.91% CAGR Low-input cropping systems [18]
Russia USD 14.52 Million Domestic formulation capacity [16]
Rest of Europe 12.4% of region Mixed arable systems [18]


Policy, not price, sets the European ceiling. France's Ecophyto programme and EU-wide substitution rules have shrunk the available active portfolio, pushing value growth into adjuvants, biologicals and precision equipment rather than tonnage [18].

Asia-Pacific

Country Metric (2025) Key Driver
China 34.8% of region Domestic manufacturing scale [14]
India USD 61.31 Million Nutrient-based subsidy disbursement [7]
Japan 3.28% CAGR Mature, high-value rice systems [2]
South Korea 6.4% of region Positive-list residue enforcement [2]
ASEAN USD 52.55 Million Oil palm and rubber estates [4]
Rest of Asia-Pacific 5.76% CAGR Paddy intensification programmes [1]


Scale and subsidy jointly explain why the Asia-Pacific Agrochemicals Market leads. Roughly 5.74 million hectares of oil palm and 1.07 million hectares of rubber in Malaysia alone generate non-seasonal demand, while paddy and horticulture programmes layer sharp seasonal peaks on top [4].

South America

Country Metric (2025) Key Driver
Brazil 58.6% of region Soybean and sugarcane acreage [20]
Argentina USD 17.61 Million Export-tax-linked planting decisions [20]
Rest of South America 5.44% CAGR Andean horticulture expansion [1]


Brazil's registration reform cut average approval times materially, releasing a backlog of new actives into a market already expanding by planted area. Plano Safra credit lines finance the input purchase directly, tightening the link between agricultural policy and supplier order books [20].

Middle East & Africa

Country Metric (2025) Key Driver
Saudi Arabia 21.8% of region Protected-cropping investment [2]
UAE 6.71% CAGR Controlled-environment agriculture [2]
South Africa USD 11.06 Million Citrus and maize export compliance [2]
Egypt 16.9% of region Nile Delta horticulture [1]
Rest of MEA 5.18% CAGR Smallholder input access programmes [1]


Water availability, not land, is the binding constraint here — which is why fertigation-compatible formulations and soil-conditioning products outgrow conventional foliar chemistry across the Gulf and North Africa [2].


Agrochemicals Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Agrochemicals Market sits in the medium band — an estimated HHI in the 900–1,100 range, with the top five suppliers holding roughly 44–52% of value. The structure is barbell-shaped: a handful of R&D-led multinationals command patented chemistry, a dense middle tier of regional formulators competes on service and credit terms, and a long tail of local repackagers serves price-sensitive smallholders.

Company Est. Revenue Share Range Key Offerings for Agrochemicals Market Strategic Positioning
Syngenta Group ~10–13% Herbicides, fungicides, seed care Broadest patented portfolio; deep agronomy services
Bayer CropScience ~9–12% Crop protection, digital agronomy Integrated seed-and-chemistry play
BASF SE ~8–11% Fungicides, herbicides, adjuvants Formulation science leadership
Corteva Agriscience ~7–10% Herbicides, insecticides, biologicals Fast-growing biologicals franchise
UPL Limited ~5–8% Post-patent actives, soil health Emerging-market distribution depth
FMC Corporation ~4–7% Insecticides, diamide chemistry Focused, high-margin active pipeline
Sumitomo Chemical ~4–6% Fungicides, plant growth regulators Strong Asia-Pacific plantation presence
ADAMA Ltd. ~3–5% Off-patent formulations Cost-efficient generics at scale
Nufarm Limited ~3–5% Herbicides, seed technologies Agile regional formulation footprint
Yara International ~3–5% Crop nutrition, fertigation solutions Low-carbon nitrogen positioning
Ancom Nylex Berhad ~2–4% Formulated crop protection, adjuvants Southeast Asian manufacturing base
Behn Meyer Group ~2–4% Specialty nutrition, distribution Technical distribution and blending


Recent News & Developments

  • Syngenta Group (March 2024): Expanded biologicals manufacturing capacity with a stated commitment above USD 100 million, signalling that biocontrol has moved from pilot to core portfolio [10].


  • Malaysian Government (October 2024): Budget 2025 raised food-security allocation to RM 4.188 billion, with earmarked fertiliser assistance for paddy smallholders [3].
  • Corteva Agriscience (February 2025): Announced acquisition of a biologicals platform to broaden its non-synthetic portfolio ahead of key patent expiries [12].
  • US EPA (May 2025): Advanced registration review decisions on several legacy actives, prompting label revisions and buffer-zone requirements across multiple states [9].


Agrochemicals Market Report Scope

Parameter Detail
Market Scope Global supply of fertilizers, pesticides, adjuvants and plant growth regulators across all crop types
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.87% (2026–2035)
Market Size Checkpoints USD 760.24 Million (2025); USD 794.83 Million (2026); USD 1,219.37 Million (2035)
Fastest Growing Segments Plant Growth Regulators (product type); Fruits and Vegetables (crop type); Fertigation (application mode)
Companies Profiled 12 leading suppliers benchmarked across the Agrochemicals Market
Valuation Currency USD Million, at annual average exchange rates

FAQs

What should procurement teams verify before qualifying a new supplier in the Agrochemicals Market?
Check active-substance registration status in every destination country, not just the country of manufacture. Request batch-level certificates of analysis and confirm the formulation plant holds a current inspection record [24].
How do toll-manufacturing agreements change distributor economics?
Tolling shifts working capital onto the brand owner while the toller earns a conversion fee. Distributors gain margin stability but surrender pricing upside when active-ingredient costs fall [19].
Which certifications matter most for exporters entering the Agrochemicals Market?
Destination residue standards dominate — Codex alignment plus buyer-specific private schemes. Manufacturing-side ISO certification helps commercial credibility but rarely unlocks market access on its own [24].
Do patent expiries always trigger price collapse?
No. Prices fall fastest where the molecule is simple to synthesise, and formulation is undifferentiated. Complex delivery systems and combination products often hold 60–70% of pre-expiry pricing for years [12].
What integration friction appears when digital agronomy platforms enter the Agrochemicals Market?
Data ownership is the recurring fight. Growers, distributors and manufacturers all claim rights to field-level application records, and unresolved contracts stall rollouts more often than technical issues do [15].
Are resistance-management programmes changing purchasing decisions?
Yes. Buyers increasingly specify mode-of-action rotation across a season rather than sourcing the single cheapest efficacious product, which favours suppliers offering broad, complementary portfolios [12].
What financing structures help smallholders afford premium inputs?
Input credit bundled with offtake agreements works best — the buyer deducts input cost at delivery. Cooperative aggregation lowers default risk and improves supplier collection rates materially [1].    
Author
Author
Author Profile
Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Co-Author
Co-Author Profile
Varsha More LinkedIn Senior Research Analyst
Experienced business professional with a demonstrated history of working in the CFnB industry. Skilled in market research, and market estimation. Strong professional with a Masters focused in marketing management.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, agricultural industry publications, peer-reviewed agronomy journals, and authoritative environmental and agricultural organizations. Key sources included the US Environmental Protection Agency (EPA), European Chemicals Agency (ECHA), Food and Agriculture Organization (FAO), US Department of Agriculture (USDA), European Food Safety Authority (EFSA), Organisation for Economic Co-operation and Development (OECD) Agricultural and Environmental Statistics, National Institute of Food and Agriculture (NIFA), World Health Organization (WHO) Pesticide Evaluation Scheme, UN Environment Programme (UNEP) Chemicals and Health Branch, EU Pesticides Database, Australian Pesticides and Veterinary Medicines Authority (APVMA), Health Canada Pest Management Regulatory Agency (PMRA), and national agricultural ministry reports from key markets including Brazil's Ministry of Agriculture (MAPA), India's Ministry of Agriculture & Farmers Welfare, and China's Ministry of Agriculture and Rural Affairs. These sources were used to collect crop production statistics, pesticide registration and usage data, fertilizer consumption trends, regulatory approval pathways, environmental impact assessments, and trade flow analysis for nitrogenous, phosphatic, and potassic fertilizers, as well as herbicides, insecticides, and fungicide categories.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. The supply side was represented by regional players and agrochemical manufacturers such as Bayer, BASF, Corteva Agriscience, FMC Corporation, and Syngenta, as well as by CEOs, VPs of product development, and heads of regulatory affairs. The demand side came from a variety of places, including chief agronomists, farm operations managers, procurement leaders from farming cooperatives and large-scale businesses, category managers from retail networks and distributors of agricultural products, and sustainability officers from food commodities processors. Market segmentation by crop type (food grains, cash crops, plantation crops, horticulture) was confirmed through primary research. Active ingredient pipeline timelines were also confirmed. Insights regarding patterns of adoption for precision agriculture technologies, pricing dynamics for commodity versus specialty fertilizers, and regional regulatory compliance challenges were further gathered.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (38%), Director Level (30%), Others (32%)

• By Region: North America (40%), Europe (25%), Asia-Pacific (28%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping and consumption volume analysis. The methodology included:

• Identification of 50+ key manufacturers and formulators across North America, Europe, Asia-Pacific, and Latin America

• Product mapping across pesticides (herbicides, insecticides, fungicides) and fertilizers (nitrogenous, phosphatic, potassic) segments

• Analysis of reported and modeled annual revenues specific to agrochemical portfolios including active ingredients and formulated products

• Coverage of manufacturers representing 75-80% of global market share in 2024

• Extrapolation using bottom-up (crop acreage × application rates × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for each crop type and product category

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















