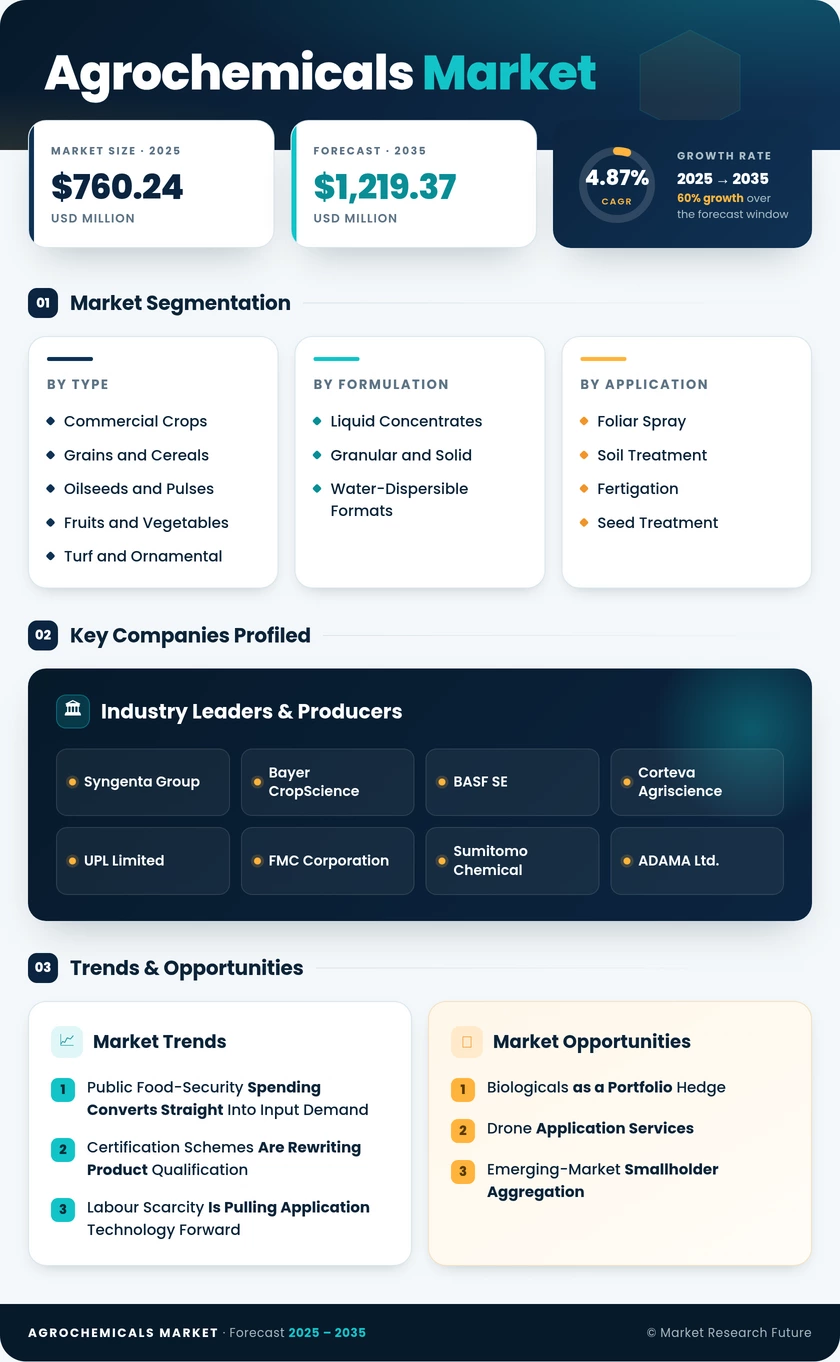
Agrochemicals Market (2026 - 2035)

ID: MRFR/Agri/0759-HCR 128 Pages Snehal Singh Last Updated: September 15, 2026

Agrochemicals Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Fertilizers, Pesticides, Adjuvants, Plant Growth Regulators), By Crop Type (Grains and Cereals, Oilseeds and Pulses, Commercial Crops, Fruits and Vegetables, Turf and Ornamental), By Formulation (Liquid Concentrates, Granular and Solid, Water-Dispersible Formats), By Application Mode (Foliar Spray, Soil Treatment, Fertigation, Seed Treatment), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Forecast Till 2035

Agrochemicals Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.87%
2025 Market SizeUSD 760.24 Million
2035 Market SizeUSD 1,219.37 Million
Key Players
Syngenta Group
Bayer CropScience
BASF SE
Corteva Agriscience
UPL Limited
FMC Corporation
Opportunities
  • Biologicals as a Portfolio Hedge
  • Drone Application Services
  • Emerging-Market Smallholder Aggregation
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Report Takeaways |
    1. 2.1 By Product Type |
    2. 2.2 By Crop Type |
    3. 2.3 By Geography
  3. 3 Global Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Market Size by Revenue (USD Million) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Public Food-Security Spending and Input Subsidies |
    2. 4.2 Certification Schemes and Product Qualification |
    3. 4.3 Labour Scarcity and Mechanised Application |
    4. 4.4 Resistance Pressure and New Modes of Action
  5. 5 Restraints Impact Analysis |
    1. 5.1 Active-Ingredient Withdrawals and Re-Registration Burden |
    2. 5.2 Counterfeit and Unregistered Product Circulation |
    3. 5.3 Feedstock Cost Volatility |
    4. 5.4 Smallholder Affordability Constraints
  6. 6 Opportunity Analysis |
    1. 6.1 Biologicals as a Portfolio Hedge |
    2. 6.2 Drone Application Services |
    3. 6.3 Emerging-Market Smallholder Aggregation |
    4. 6.4 Data Monetisation From Application Records |
    5. 6.5 Post-Patent Premiumisation |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Autonomous Application Becomes Default |
    2. 8.2 Prescription Platforms and Distribution Economics |
    3. 8.3 Carbon and Residue Reporting in Procurement |
    4. 8.4 Consolidation Around Formulation IP
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Product Type | |
      1. 9.1.1 Fertilizers | |
      2. 9.1.2 Pesticides | |
      3. 9.1.3 Adjuvants | |
      4. 9.1.4 Plant Growth Regulators |
    2. 9.2 By Crop Type | |
      1. 9.2.1 Grains and Cereals | |
      2. 9.2.2 Oilseeds and Pulses | |
      3. 9.2.3 Commercial Crops | |
      4. 9.2.4 Fruits and Vegetables | |
      5. 9.2.5 Turf and Ornamental |
    3. 9.3 By Formulation | |
      1. 9.3.1 Liquid Concentrates | |
      2. 9.3.2 Granular and Solid | |
      3. 9.3.3 Water-Dispersible Formats |
    4. 9.4 By Application Mode | |
      1. 9.4.1 Foliar Spray | |
      2. 9.4.2 Soil Treatment | |
      3. 9.4.3 Fertigation | |
      4. 9.4.4 Seed Treatment
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Syngenta Group | |
      2. 10.3.2 Bayer CropScience | |
      3. 10.3.3 BASF SE | |
      4. 10.3.4 Corteva Agriscience | |
      5. 10.3.5 UPL Limited | |
      6. 10.3.6 FMC Corporation | |
      7. 10.3.7 Sumitomo Chemical | |
      8. 10.3.8 ADAMA Ltd. | |
      9. 10.3.9 Nufarm Limited | |
      10. 10.3.10 Yara International | |
      11. 10.3.11 Ancom Nylex Berhad | |
      12. 10.3.12 Behn Meyer Group
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources and Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Agrochemicals Market Size & Forecast, by Revenue (USD Million), 2021–2035 |
  17. TABLE 2 Global Agrochemicals Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Market Size, by Product Type, 2021–2035 (USD Million) |
  21. TABLE 6 Global Market Size, by Crop Type, 2021–2035 (USD Million) |
  22. TABLE 7 Global Market Size, by Formulation, 2021–2035 (USD Million) |
  23. TABLE 8 Global Market Size, by Application Mode, 2021–2035 (USD Million) |
  24. TABLE 9 Global Market Size, by Region, 2021–2035 (USD Million) |
  25. TABLE 10 North America Market Size, by Country, 2021–2035 (USD Million) |
  26. TABLE 11 Europe Market Size, by Country, 2021–2035 (USD Million) |
  27. TABLE 12 Asia-Pacific Market Size, by Country, 2021–2035 (USD Million) |
  28. TABLE 13 South America Market Size, by Country, 2021–2035 (USD Million) |
  29. TABLE 14 Middle East & Africa Market Size, by Country, 2021–2035 (USD Million) |
  30. TABLE 15 North America Market Size, by Product Type, 2021–2035 (USD Million) |
  31. TABLE 16 North America Market Size, by Crop Type, 2021–2035 (USD Million) |
  32. TABLE 17 Europe Market Size, by Product Type, 2021–2035 (USD Million) |
  33. TABLE 18 Europe Market Size, by Crop Type, 2021–2035 (USD Million) |
  34. TABLE 19 Asia-Pacific Market Size, by Product Type, 2021–2035 (USD Million) |
  35. TABLE 20 Asia-Pacific Market Size, by Crop Type, 2021–2035 (USD Million) |
  36. TABLE 21 South America Market Size, by Product Type, 2021–2035 (USD Million) |
  37. TABLE 22 South America Market Size, by Crop Type, 2021–2035 (USD Million) |
  38. TABLE 23 Middle East & Africa Market Size, by Product Type, 2021–2035 (USD Million) |
  39. TABLE 24 Middle East & Africa Market Size, by Crop Type, 2021–2035 (USD Million) |
  40. TABLE 25 Regional Market Share Summary and Investment Themes, 2025 |
  41. TABLE 26 Competitive Benchmarking Matrix, 2026 |
  42. TABLE 27 Company Profiles – Key Players |
  43. TABLE 28 Recent Developments & Strategic Announcements, 2023–2025 |
  44. TABLE 29 Report Scope & Methodology Summary |
  45. TABLE 30 Detailed Sources and Citations Index
  46. 16 LIST OF FIGURES |
  47. FIGURE 1 Market Dynamics – Drivers, Restraints and Opportunities Snapshot |
  48. FIGURE 2 Industry Value Chain Analysis |
  49. FIGURE 3 Porter's Five Forces Assessment |
  50. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Million) |
  51. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 |
  52. FIGURE 6 Market Share by Product Type, 2025 vs 2035 |
  53. FIGURE 7 Market Share by Crop Type, 2025 vs 2035 |
  54. FIGURE 8 Market Share by Formulation, 2025 |
  55. FIGURE 9 Market Share by Application Mode, 2025 |
  56. FIGURE 10 Regional Market Share Distribution, 2025 |
  57. FIGURE 11 Regional CAGR Comparison, 2026–2035 |
  58. FIGURE 12 Country-Level Contribution Heatmap, 2025 |
  59. FIGURE 13 Competitive Landscape – Estimated Revenue Share Bands, 2026 |
  60. FIGURE 14 Strategic Positioning Matrix – Innovation vs Distribution Reach

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeFertilizers; Pesticides; Adjuvants; Plant Growth RegulatorsPesticidesPlant Growth Regulators
By Crop TypeGrains and Cereals; Oilseeds and Pulses; Commercial Crops; Fruits and Vegetables; Turf and OrnamentalCommercial CropsFruits and Vegetables
By FormulationLiquid Concentrates; Granular and Solid; Water-Dispersible FormatsLiquid ConcentratesWater-Dispersible Formats
By Application ModeFoliar Spray; Soil Treatment; Fertigation; Seed TreatmentFoliar SprayFertigation
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificSouth America


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
FertilizersSubsidy-linked demand with a shift toward controlled-release and low-carbon nitrogen
PesticidesPortfolio rotation driven by resistance management and residue-limit tightening
AdjuvantsRapid uptake as tank-mix optimisation becomes standard estate practice
Plant Growth RegulatorsFastest-growing line, tied to harvest timing and lodging control economics


Product-side value is migrating from tonnage to specification. Buyers now evaluate registration status, residue profile and equipment compatibility before price, which favours suppliers with documented formulation science over commodity repackagers.

By Crop Type

Sub-SegmentKey Trend
Grains and CerealsSteady volume anchored by paddy and wheat intensification programmes
Oilseeds and PulsesAcreage-led growth concentrated in South American soybean systems
Commercial CropsTender-based estate procurement delivering predictable high-spec demand
Fruits and VegetablesExport residue audits pushing growers toward registered, traceable product
Turf and OrnamentalModest, urban-budget-dependent demand with strong seasonality


Crop mix determines margin more than geography does. Horticulture and estate crops both tolerate premium chemistry, while broadacre grains remain the most price-elastic buyers in the portfolio.

By Formulation

Sub-SegmentKey Trend
Liquid ConcentratesPreferred format for mechanised and drone-based application systems
Granular and SolidControlled-release technology extending nutrient availability windows
Water-Dispersible FormatsGrowth driven by operator-exposure reduction and handling safety


Formulation strategy now follows the application hardware roadmap. Suppliers aligning concentration and solubility profiles to drone tanks and fertigation lines capture the fastest-growing hectares.

By Application Mode

Sub-SegmentKey Trend
Foliar SprayBroadest compatibility; increasingly delivered through autonomous rigs
Soil TreatmentResidual protection and structured nutrient release
FertigationFastest-growing mode in water-constrained irrigated systems
Seed TreatmentEarly-stage protection with attractive cost-per-hectare economics


Application mode is becoming the real segmentation axis. As prescription platforms specify where and how product is placed, mode selection increasingly dictates which formulations reach the field at all.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.