Actinic Keratosis Treatment Market (2026 - 2035)

Actinic Keratosis Treatment Market Research Report: Size, Share, Trend Analysis By Types (Medications and Procedures), By End Users (Hospitals & Oncology Centers, Dermatology Clinics and Ambulatory Surgical Center)) - Growth Outlook & Industry Forecast 2025 To 2035

Forecast Period
2026-2035
CAGR
4.38%
2025 Market Size
USD 7.68 Billion
2035 Market Size
USD 11.74 Billion
Pharmaceutical ● Updated August 24, 2026 Report ID: MRFR/Pharma/1746-CR | Pages: 95 | Author: Satyendra Maurya, Rahul Gotadki

Actinic Keratosis Treatment Market Summary

The Actinic Keratosis Treatment Market was valued at USD 7.68 billion in 2025 and opens the forecast window at USD 7.99 billion in 2026, climbing to USD 11.74 billion by 2035 at a 4.38% CAGR. Two catalysts anchor that trajectory. First, the U.S. Centers for Medicare & Medicaid Services has steadily widened coverage clarity for field-directed dermatologic care, and destruction of premalignant lesions remains one of the highest-volume billed dermatology procedures in Medicare Part B [5]. Second, Australia's national skin-cancer awareness spending — running above AUD 30 million annually across federal and state programs — keeps diagnosis rates high in the world's most lesion-dense population [12].

Clinical practice is shifting underneath those numbers. Single-lesion destruction, long the reflex answer, is giving way to field cancerization management: shorter-course topicals, daylight-mediated protocols, and fractional laser-assisted drug delivery that treat the whole sun-damaged field rather than the visible tip of it. LEO Pharma, Almirall and Biofrontera collectively directed more than USD 400 million into dermatology R&D across 2023–2024, much of it aimed at compressing treatment courses from four weeks to four days [19][21].

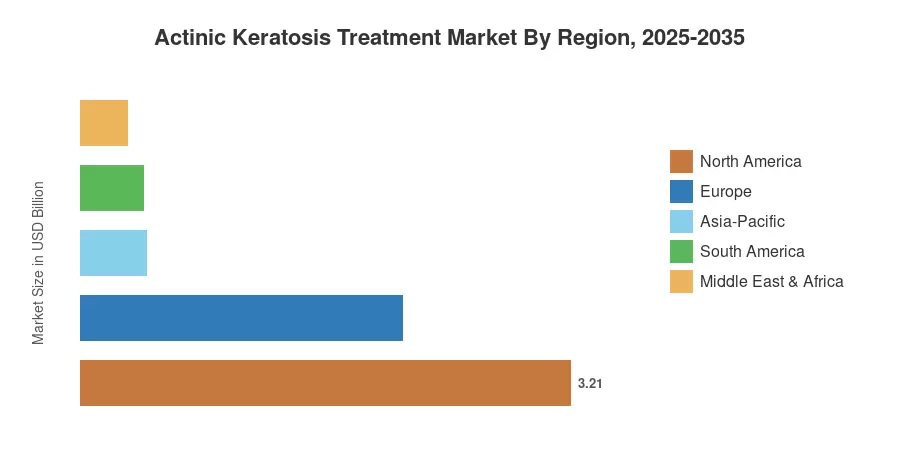
Regionally, North America holds 41.8% of the Actinic Keratosis Treatment Market on the strength of reimbursement depth and dermatologist density. Asia-Pacific grows fastest at a 5.62% CAGR, propelled by Japan's aging cohort and Australia's screening intensity. Europe, second at 27.5%, leans on organized skin-check programs in Germany and the Nordics. The next decade belongs to whoever can make field therapy tolerable enough that patients finish it.


Key Report Takeaways

• By Therapy

  • Topical medications commanded 42.0% of the Actinic Keratosis Treatment Market in 2025, still the default first-line answer in primary and specialist care.
  • Procedural treatments are advancing at a 5.48% CAGR through 2035 as laser and curettage capacity expands.
  • Photodynamic approaches contributed roughly USD 1.41 billion in 2025 revenue.

• By End User

  • Hospitals and oncology centers held a 49.8% share in 2025, reflecting referral concentration for high-risk lesions.
  • Home-care settings post the fastest end-user growth at a 5.06% CAGR
  • Online pharmacies expand at a 5.42% CAGR, the quickest distribution channel in the Actinic Keratosis Treatment Market

• By Region

  • North America retained a 41.8% share in 2025
  • Asia-Pacific records the steepest regional CAGR at 5.62%
  • Europe generated approximately USD 2.11 billion in 2025


Market Size and Forecast (2021–2035)

Historical values were reconstructed from dermatology procedure volumes reported by national claims databases, pharmacy dispensing audits, and device shipment data, then triangulated against manufacturer segment disclosures. Forecast years apply a demand model weighted by population aging curves, UV-exposure indices, and reimbursement-coverage breadth in the eleven largest treatment economies. The Actinic Keratosis Treatment Market is expressed throughout in USD billion at constant 2025 prices.
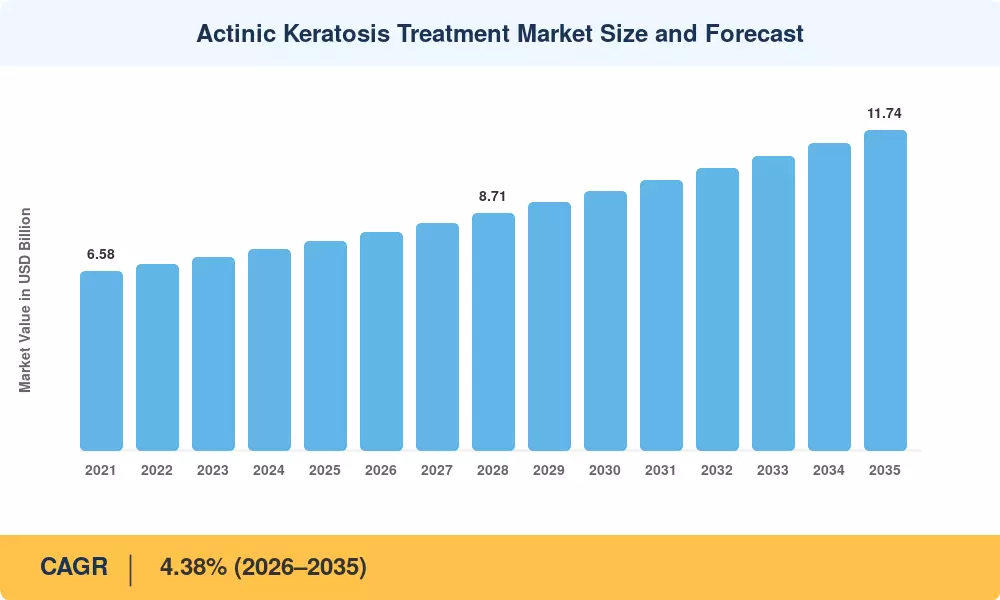
Actinic Keratosis Treatment Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aging fair-skinned population base +0.92 pp North America, Europe, ANZ Long-term (≥4 yr)
Reimbursement clarity for field-directed care +0.71 pp North America, Europe Medium-term (2–4 yr)
Daylight-mediated protocols reducing chair time +0.58 pp Europe, Asia-Pacific Medium-term (2–4 yr)
National skin-screening programs +0.49 pp Germany, Australia, Nordics Short-term (≤2 yr)
Teledermatology and AI-assisted triage +0.41 pp Global Medium-term (2–4 yr)
Shorter-course topical formulations +0.37 pp North America, Europe Short-term (≤2 yr)
Dermatology capacity expansion in Asia-Pacific +0.29 pp Japan, South Korea, China Long-term (≥4 yr)


Reimbursement Clarity for Field-Directed Therapy

In the past, payers reimbursed field therapy reluctantly and lesion destruction liberally. That difference is getting smaller. Prior-authorization requirements for topical field agents have been eliminated by various commercial plans since 2023, while Medicare Part B reimburses premalignant lesion removal at about USD 79 for the first lesion with escalating amounts thereafter [5][7]. In 2024, photodynamic reimbursement was extended to more outpatient settings by Germany's statutory insurers, adding an estimated 210,000 eligible procedures each year [13].


Daylight Protocols and Throughput Economics

The majority of an afternoon is spent in a treatment room during traditional light-source photodynamic procedures. In Nordic trial cohorts, daylight-activated treatments lower reported pain ratings by over half and reduce in-clinic time to about thirty minutes [8]. Adoption in Denmark and Australia exceeds regulatory expectations by a significant margin since that throughput difference translates directly into margin for a clinic with 12 chairs.


Shorter Courses, Better Completion

Adherence has always been the weak link. Four-week regimens see completion rates below 60% in real-world audits, while compressed schedules of two to five days push completion above 85% [3][10]. Manufacturers have responded: the pipeline now favors high-potency, short-duration formulations over gentler long courses, and that reformulation wave is a structural tailwind for the Actinic Keratosis Treatment Market through 2030.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Generic erosion of legacy topical agents −0.61 pp Global Short-term (≤2 yr)
Patient non-adherence and local skin reactions −0.48 pp Global Medium-term (2–4 yr)
Bundled-payment caps on procedural dermatology −0.39 pp North America, Europe Medium-term (2–4 yr)
Dermatologist shortages in rural catchments −0.33 pp US interior, Rest of Europe Long-term (≥4 yr)
Low diagnostic awareness in emerging economies −0.27 pp South America, MEA Long-term (≥4 yr)


Generic Price Compression

Fluorouracil and imiquimod both sit deep in generic territory, and average wholesale pricing on 5% fluorouracil cream has fallen more than 40% since 2019 across U.S. and European channels [9]. Volume keeps rising; revenue per course does not. Branded players have largely conceded the commodity tier and repositioned toward differentiated delivery, which protects margin but caps the value ceiling of the Actinic Keratosis Treatment Market.

Tolerability and the Abandonment Problem

Field therapy that works is painful. According to dermatology audits, mid-course abandonment for four-week regimens is close to 27%, and erythema, crusting, and erosion peak at the same moment when patients are most likely to stop [10]. Roughly one-third of those dropouts are recovered by clinics that implement systematic follow-up contacts, but staffing such intervention is a cost that few practices are prepared to bear.


Access Gaps Outside Metropolitan Centres

There are similar shortages in interior Brazil and much of sub-Saharan Africa, with nearly 40% of U.S. counties lacking a dermatologist in practice [11][16]. Teledermatology reduces the diagnostic gap, but not the procedural one; a doctor and a device must still be present in the patient's room for cryotherapy and laser.


Actinic Keratosis Treatment Market Opportunities

Field Therapy as Preventive Standard of Care

An episodic purchase becomes recurrent when the field is treated instead of the lesion. Because treatment costs for invasive squamous cell carcinoma are an order of magnitude higher than those for prevention, payers are becoming more accommodating [4]. The most beneficial narrative change accessible to manufacturers is to position the treatment of precancerous skin lesions as cost-avoidance rather than cosmetic dermatology.


Drug-Device Combination Platforms

Topical penetration is significantly increased by fractional laser pretreatment, and combination treatments currently earn premium billing in a number of European systems. In the Actinic Keratosis Treatment Market, device manufacturers who collaborate with pharmaceutical partners gain a structurally superior position by capturing value on both sides of the interaction.


Emerging-Market Diagnostic Build-Out

Brazil, Saudi Arabia and South Africa combine high UV indices with underdeveloped screening infrastructure. Brazil's national cancer institute has expanded mobile dermatology screening into 14 states, and each diagnostic expansion converts latent prevalence into treated demand [16][18]. First movers who fund screening capacity tend to own the subsequent treatment channel.

Data Monetization Through Longitudinal Lesion Registries

Serial dermoscopic imaging generates a defensible data asset. Companies operating imaging platforms can license de-identified progression datasets to payers modelling cost-avoidance and to regulators assessing post-market outcomes — a recurring revenue line entirely separate from product sales [14].

Home-Administered and Subscription Models

Home-care settings already post the fastest end-user growth. Bundling teledermatology review, prescription fulfilment and adherence coaching into a subscription converts a fragmented episode into a managed relationship, with early pilots reporting completion rates above 80% [14].


Actinic Keratosis Treatment Market Future Outlook

AI-Assisted Detection Moves Upstream

Algorithmic lesion classification has crossed the threshold from research curiosity to reimbursable triage in several systems, with regulatory clearances now covering dermoscopic decision support in both the U.S. and EU [14]. The strategic consequence is volume: earlier detection expands the treatable pool for the Actinic Keratosis Treatment Market rather than merely reallocating it. Primary-care physicians equipped with validated triage tools will identify lesions that never previously reached a specialist.

Platform Economics in Drug-Device Bundling

Standalone topicals face relentless price compression; bundled protocols do not. Vendors combining a device, a drug and a documented protocol can defend pricing through clinical outcome data rather than molecule exclusivity. Expect consolidation as pharmaceutical firms acquire laser and light-source assets — a pattern already visible in the Actinic Keratosis Treatment Market's 2024–2025 transaction record.


Sustainability and Outpatient Carbon Accounting

European health systems have begun reporting facility-level emissions, and outpatient procedures that reduce clinic hours and patient travel now carry measurable reporting advantage [15]. Daylight protocols and home-administered regimens score well on both counts. It is a secondary consideration today; by 2032, in tender-driven European procurement, it will be a scored criterion.


Actinic Keratosis Treatment Market Segmentation

By Therapy

Therapy mix in the Actinic Keratosis Treatment Market remains topical-led but is diversifying faster than at any point in the past decade.

Segment Metric (2025) Primary Demand Driver
Topical Medications 42.0% share First-line prescribing default
Procedural Treatments 5.48% CAGR (2026–2035) Cryotherapy and curettage throughput
Photodynamic Therapy USD 1.41 Billion Field clearance efficacy
Combination Therapy 8.3% share Refractory lesion management
Other Therapies USD 0.35 Billion Chemical peels, dermabrasion


Topicals hold their lead because they are cheap, prescribable without a procedure slot, and now available in courses short enough that patients finish them. Procedural treatments grow faster for a different reason entirely: immediate visible clearance and single-visit resolution appeal to patients who will not tolerate weeks of inflammation. Photodynamic AK therapy occupies the middle ground, delivering field-level clearance in a controlled clinical setting, and its growth is gated less by efficacy evidence than by chair-time economics [8].

By End User

End-user concentration in the Actinic Keratosis Treatment Market is loosening as care shifts toward lower-acuity settings.

Segment Metric (2025) Primary Demand Driver
Hospitals & Oncology Centers 49.8% share High-risk and referred lesion volume
Dermatology Clinics USD 2.20 Billion Specialist procedural capacity
Ambulatory Surgical Centers 12.1% share Cost-efficient procedure siting
Home-Care Settings 5.06% CAGR (2026–2035) Self-applied topical regimens


Hospitals retain dominance because referral pathways funnel ambiguous or immunosuppressed cases toward institutional dermatology, where biopsy capability sits alongside treatment. Home-care's rise is the more interesting story — it reflects prescriber confidence in newer short-course formulations and a payer preference for shifting cost out of facility settings entirely.

By Distribution Channel

Segment Metric (2025) Primary Demand Driver
Hospital Pharmacies 44.7% share Integrated dispensing at point of care
Retail Pharmacies USD 2.55 Billion Outpatient prescription fulfilment
Online Pharmacies 5.42% CAGR (2026–2035) Telehealth prescription linkage
Other Channels 7.5% share Direct clinic supply, specialty distributors


Due to integrated dispensing at the point of care and the increasing demand for prompt prescription fulfillment in hospital settings, the Hospital Pharmacies segment led the market in 2025 with 44.7% of the total share. The fastest-growing market is online pharmacies, which are expected to increase at a compound annual growth rate (CAGR) of 5.42% between 2026 and 2035 due to the integration of digital prescription services and growing telehealth acceptance. While other channels, such as direct clinic supply and specialist distributors, accounted for 7.5% of the market, retail pharmacies continue to be a significant distribution channel, generating USD 2.55 billion through outpatient prescription fulfillment in 2025.


By Patient Age Group

Segment Metric (2025) Primary Demand Driver
Below 40 Years 5.66% CAGR (2026–2035) Preventive screening uptake
40–60 Years 30.6% share Occupational sun exposure cohorts
Above 60 Years USD 4.80 Billion Peak cumulative UV damage


The over-60 cohort supplies the bulk of revenue and will continue to. The under-40 growth rate matters strategically rather than commercially: it signals that younger patients, prompted by awareness campaigns and dermoscopic screening at cosmetic visits, are entering the treatment funnel decades before their predecessors did.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 41.8% share Field-therapy reimbursement, combination platforms
Europe USD 2.11 Billion Organized screening, daylight protocols
Asia-Pacific 5.62% CAGR (2026–2035) Dermatology capacity, aging cohorts
South America 5.3% share Mobile screening, generic access
Middle East & Africa USD 0.31 Billion Private clinic build-out, expatriate demand
Total USD 7.68 Billion

Geographic performance in the Actinic Keratosis Treatment Market tracks two variables with unusual fidelity: cumulative UV exposure of the resident population and the depth of outpatient dermatology reimbursement. Where both are high, penetration is near saturation. Where only the first is high, growth is steep.


North America

Country Metric Key Driver
US 86.4% of regional share Medicare lesion-destruction volume
Canada USD 0.29 Billion Provincial dermatology coverage
Mexico 5.9% CAGR Private dermatology expansion


American demand rests on a reimbursement architecture no other market replicates: destruction of premalignant lesions is among the most frequently billed procedures in Medicare Part B, and dermatologist density exceeds 3.6 per 100,000 in coastal states [5][11]. Canada's growth is steadier and slower, constrained by provincial wait-list dynamics. Mexico is the outlier — small base, fast private-sector expansion, and a rapidly professionalizing aesthetic-dermatology channel that increasingly treats sun damage alongside cosmetic indications.

Europe

Country Metric Key Driver
Germany 24.1% of regional share Statutory biennial skin-cancer screening
UK USD 0.34 Billion NHS dermatology pathway reform
France 14.6% of regional share Outpatient photodynamic reimbursement
Italy USD 0.21 Billion Aging coastal population
Spain 4.9% CAGR High UV index, tourism dermatology
Nordic Countries 9.8% of regional share Daylight protocol leadership
Russia USD 0.09 Billion Limited reimbursement breadth
Rest of Europe 4.3% CAGR Gradual guideline harmonization


Germany's statutory skin-cancer screening entitlement, offered biennially to insured adults over 35, remains the most consequential single policy in European dermatology — it surfaces lesions that would otherwise present years later and at greater cost [13]. Nordic systems pioneered daylight-activated protocols and continue to publish the outcome data that drives adoption elsewhere [8]. The UK's picture is more constrained; dermatology referral backlogs have pushed a meaningful share of low-acuity lesion management into primary care and private clinics.

Asia-Pacific

Country Metric Key Driver
China USD 0.31 Billion Tier-1 city dermatology build-out
India 6.4% CAGR Rising diagnostic awareness
Japan 28.7% of regional share Highest regional over-65 share
South Korea USD 0.17 Billion Aesthetic-dermatology crossover
ASEAN 5.8% CAGR Private hospital expansion
Rest of Asia-Pacific 21.3% of regional share Australia and New Zealand lesion density


Australia does most of the heavy lifting inside the Rest of Asia-Pacific line — lesion prevalence there is the highest measured anywhere, and Cancer Council programs have normalized annual skin checks across a large share of the adult population [12]. Japan contributes scale through demographics rather than incidence; with over 29% of citizens above 65, absolute lesion counts keep climbing even at moderate per-capita rates [17]. India and ASEAN remain awareness-limited, which is precisely why their growth rates lead the region.

South America

Country Metric Key Driver
Brazil 61.2% of regional share INCA mobile screening expansion
Argentina USD 0.06 Billion Urban private dermatology
Rest of South America 5.1% CAGR Gradual public coverage widening


Brazil combines a large fair-skinned population in its southern states with intense equatorial UV exposure further north, and its national cancer institute has pushed mobile screening units into underserved states to close the diagnostic gap [16]. Public-sector procurement favours generics heavily, which suppresses value capture even as treated volume climbs. Argentina's market is smaller, more concentrated in Buenos Aires, and more exposed to currency volatility in imported product pricing.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.4% of regional share Vision 2030 healthcare investment
UAE USD 0.07 Billion Expatriate dermatology demand
South Africa 6.1% CAGR High-risk fair-skinned population
Egypt USD 0.04 Billion Emerging private clinic network
Rest of MEA 19.8% of regional share Fragmented access


Gulf demand is driven less by indigenous incidence than by large expatriate populations from higher-risk backgrounds combined with well-funded private clinics; Saudi Arabia's health-sector transformation programme has committed substantial capital to outpatient specialty capacity [18]. South Africa presents the region's clearest clinical need, with a fair-skinned minority carrying incidence rates comparable to Australia's, yet public dermatology capacity remains thin outside major metros.


Actinic Keratosis Treatment Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Actinic Keratosis Treatment Market is moderate. The estimated Herfindahl-Hirschman Index sits near 720, with the top five participants controlling roughly 46–52% of global revenue — enough for pricing discipline in branded tiers, not enough to prevent generic entrants from eroding legacy franchises. Competitive behaviour splits cleanly: large pharmaceutical firms buy pipeline and defend formulary position, while smaller specialists differentiate on protocol and device integration.

Company Est. Revenue Share Range Key Offerings for Actinic Keratosis Treatment Market Strategic Positioning
Bausch Health Companies ~11–14% Topical field agents, dermatology portfolio Scale incumbent defending formulary access
Almirall S.A. ~9–12% Field-directed topicals, dermatology specialty Pure-play dermatology focus in Europe
LEO Pharma A/S ~8–11% Topical therapeutics, medical dermatology R&D-led, strong Nordic clinical base
Galderma S.A. ~6–9% Therapeutic and aesthetic dermatology Dual therapeutic-aesthetic channel leverage
Biofrontera AG ~5–8% Photodynamic agents and light systems Drug-device combination specialist
Sun Pharmaceutical Industries ~4–7% Generic and branded topicals Cost-position leader in emerging markets
Mayne Pharma Group ~3–6% Dermatology generics Volume-led generic supplier
Perrigo Company plc ~3–5% Topical generics, OTC dermatology Private-label and retail channel depth
Taro Pharmaceutical Industries ~3–5% Topical dermatology generics Manufacturing scale in North America
Candela Corporation ~2–4% Fractional laser platforms Device-side procedural enablement
Sol-Gel Technologies ~1–3% Microencapsulated topical formulations Formulation-technology challenger


Recent News & Developments

  • Biofrontera Inc. (June 2024): Started selling its recently FDA-approved RhodoLED® XL red-light lamp commercially in the US, supporting the company's drug-device bundling strategy and enabling larger-field photodynamic illumination when combined with Ameluz®.


  • Almirall S.A. (June 2024): Obtained FDA clearance for a Supplemental New Drug Application (sNDA) that would increase the treatment area of Klisyri® (tirbanibulin) on the face or scalp to 100 cm². This would establish short 5-day regimen adherence and field treatment area coverage as important commercial differentiators.


  • U.S. FDA (January 2024): Approved DermaSensor, the first AI-assisted point-of-care skin cancer detection tool, to expand the upstream referral funnel for primary care practices and assess problematic lesions for all three major skin malignancies.


Actinic Keratosis Treatment Market Report Scope

Parameter Detail
Market Scope Global treatment of actinic keratosis across therapy, end user, distribution channel, patient age group, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.38% (2026–2035)
Market Size Checkpoints USD 7.68 Billion (2025); USD 7.99 Billion (2026); USD 11.74 Billion (2035)
Fastest Growing Segments Procedural treatments (therapy); home-care settings (end user); online pharmacies (channel); below-40 years (age group)
Companies Profiled 11 major participants including Bausch Health, Almirall, LEO Pharma, Galderma, Biofrontera, Sun Pharmaceutical, Mayne Pharma, Perrigo, Taro, Candela, Sol-Gel
Valuation Currency USD Billion, constant 2025 prices

FAQs

What procurement terms should hospital groups negotiate when contracting field-therapy products?
Prioritize outcome-linked pricing tied to documented clearance rates rather than unit cost. Insist on adherence-support services bundled into the contract, since abandonment destroys realized value more than list price does [10].
How should investors evaluate exposure to the Actinic Keratosis Treatment Market given generic pressure?
Weight portfolios toward drug-device combinations and protocol-differentiated assets, not molecules. Companies dependent on legacy topical franchises face structural margin compression regardless of volume growth [9].
Which regulatory nuance most often surprises new entrants in the Actinic Keratosis Treatment Market?
Light sources used in photodynamic protocols are frequently regulated as devices while the applied agent is regulated as a drug, requiring dual submission pathways. Timelines diverge by 9–18 months in several jurisdictions [25].
How do cryotherapy and field-directed approaches compare in practice?
Cryotherapy clears visible lesions quickly and needs no patient compliance. Field approaches treat subclinical damage and reduce recurrence, but demand weeks of tolerance from the patient [3].
What integration challenges do clinics face adopting AI-assisted triage in the Actinic Keratosis Treatment Market?
Image capture standardization is the practical bottleneck — inconsistent dermoscopy technique degrades algorithm performance more than model quality does. Budget for staff training and hardware uniformity, not just software licensing [14].
Are there emerging use cases beyond conventional dermatology settings?
Occupational health programmes for outdoor workers are an underdeveloped channel, particularly in construction and agriculture. Employer-funded screening converts a workforce liability into a manageable, contracted service line [24].
How is competitive rivalry likely to shift by 2030?
Expect pharmaceutical acquirers to absorb device and imaging specialists, consolidating protocol ownership. Standalone generic manufacturers will compete purely on cost and lose relevance in premium clinical settings [22].      
Author
Author
Author Profile
Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed dermatology and oncology journals, clinical trial repositories, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Orange Book and Dermatology Advisory Committee filings, European Medicines Agency (EMA) Dermatology assessments, Health Canada Therapeutic Products Directorate, Australian Therapeutic Goods Administration (TGA), and Pharmaceuticals and Medical Devices Agency (PMDA) Japan. Epidemiological and clinical data were gathered from the National Institutes of Health (NIH)/National Cancer Institute (NCI), International Agency for Research on Cancer (IARC) World Cancer Report, Centers for Disease Control and Prevention (CDC) Skin Cancer Statistics, and WHO Global Cancer Observatory (GLOBOCAN).

Dermatology-specific authoritative sources included the American Academy of Dermatology (AAD) Annual Meeting proceedings and Practice Profile surveys, European Academy of Dermatology and Venereology (EADV) guidelines, British Association of Dermatologists (BAD) clinical audits, and Skin Cancer Foundation screening databases. Prescription and claims data were analyzed through IQVIA National Prescription Audit, Symphony Health Integrated Dataverse, and CMS Medicare Part D Drug Spending Dashboards. Clinical evidence was synthesized from PubMed/MEDLINE, Cochrane Library systematic reviews on field-directed therapy for actinic keratosis, and key journals including Journal of the American Academy of Dermatology (JAAD), Journal of Investigative Dermatology, British Journal of Dermatology, and Dermatologic Surgery. These sources were used to collect patient epidemiology (prevalence of actinic keratosis by Fitzpatrick skin type and age demographics), treatment algorithm adoption rates, regulatory approval timelines for topical field therapies, photodynamic therapy protocol standardization, and reimbursement coding dynamics (CPT codes for cryotherapy and PDT, J-codes for topical medications).


Primary Research

In the primary research process, qualitative and quantitative insights regarding treatment adoption barriers, pipeline viability, and clinical practice pattern adjustments were obtained through interviews with supply-side and demand-side stakeholders. The supply-side sources consisted of Chief Executive Officers, Heads of Global Dermatology Franchises, Chief Medical Officers, Vice Presidents of Clinical Development, regulatory affairs heads, and commercial strategy directors from pharmaceutical manufacturers that were developing topical immunomodulators, cytotoxic agents, and device manufacturers that were producing cryosurgical equipment and photodynamic therapy light sources. Pharmaceutical directors at integrated health systems, procurement leads from dermatology clinics, medical directors of ambulatory surgical centers that provide office-based field therapy, dermatopathologists, medical oncologists who specialize in skin malignancies, and board-certified dermatologists (including fellowship-trained Mohs surgeons and cosmetic dermatologists) comprised demand-side sources.

Primary research has confirmed the clinical pipeline timelines for novel tubulin inhibitors and immune response modifiers, validated market segmentation between destructive procedures and field-directed topical medications and gathered insights on physician prescribing behaviors (treatment sequencing between cryotherapy and topical agents), payer prior authorization requirements, and patient adherence patterns to multi-week topical regimens.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (30%), Others (30%)

By Region: North America (40%), Europe (25%), Asia-Pacific (28%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping and procedure volume analysis specific to both pharmaceutical dispensing and dermatological procedure utilization. The methodology included:

Identification of 30+ key pharmaceutical and medical device manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in topical actinic keratosis therapeutics (5-fluorouracil, imiquimod, diclofenac, ingenol mebutate, tirbanibulin formulations) and procedural devices (cryosurgical units, photodynamic therapy illumination systems, laser platforms)

Product mapping across medication classes (cytotoxic agents, immune modulators, NSAIDs, tubulin inhibitors) and procedural categories (cryotherapy, photodynamic therapy, ablative and non-ablative laser therapy, chemical peels)

Analysis of reported and modeled annual revenues specific to actinic keratosis portfolios, including generic erosion impact on mature brands and launch trajectories for novel agents

Coverage of manufacturers representing 75-80% of global market share in 2024, including Galderma, Almirall, Sun Pharmaceutical, Biofrontera, LEO Pharma, and Cipher Pharmaceuticals

Extrapolation using bottom-up approach (region-specific epidemiology of actinic keratosis cases × diagnosis rates × treatment-seeking rates × average selling price by treatment modality) and top-down validation (manufacturer-reported dermatology revenue segmentation) to derive segment-specific valuations for topical medications versus procedural interventions, with separate modeling for hospital outpatient departments versus independent dermatology clinic settings

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















