Acoustic Emission Testing Market Summary
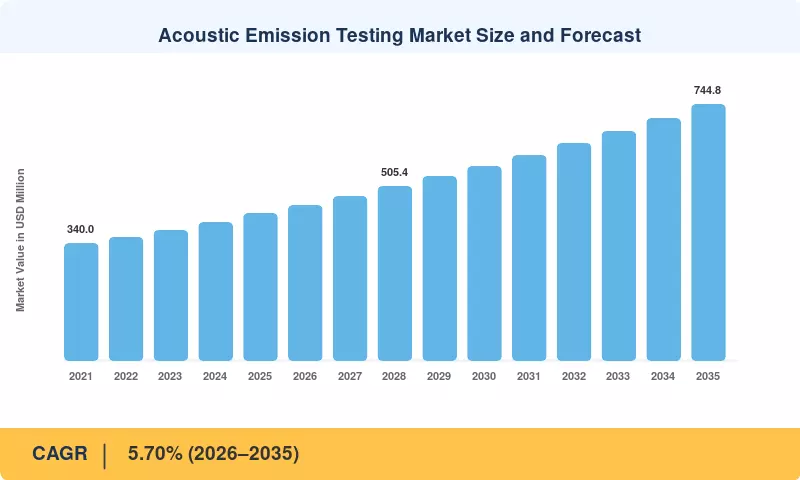
The Acoustic Emission Testing Market reached USD 427.8 Million in 2025 and opens the forecast window at USD 452.2 Million in 2026, advancing to USD 744.8 Million by 2035 at a 5.70% CAGR. Two catalysts anchor that trajectory. The U.S. Infrastructure Investment and Jobs Act committed USD 40 billion to bridge repair and replacement through 2031, pushing state departments of transportation toward continuous strain and crack-growth surveillance [1]. In parallel, the European Union's Industrial Emissions Directive recast tightened leak and containment verification duties on refiners and chemical operators, making passive listening methods a compliance instrument rather than a discretionary check [2].
The legacy approach in this space was periodic shutdown inspections, manual chart interpretation and paper reporting. Instead, that paradigm is giving way to permanently placed piezoelectric arrays flowing into cloud analytics where machine-learning classifiers distinguish real crack propagation from friction and flow noise. In 2024, Baker Hughes generated USD 1.1 billion in revenues from industrial asset-health and inspection technology, demonstrating the rapid transfer of budgets from field labor to instrumentation and software licenses [3]. Now, large refiners are increasingly allocating a portion to monitoring subscriptions in their non-destructive testing expenses.
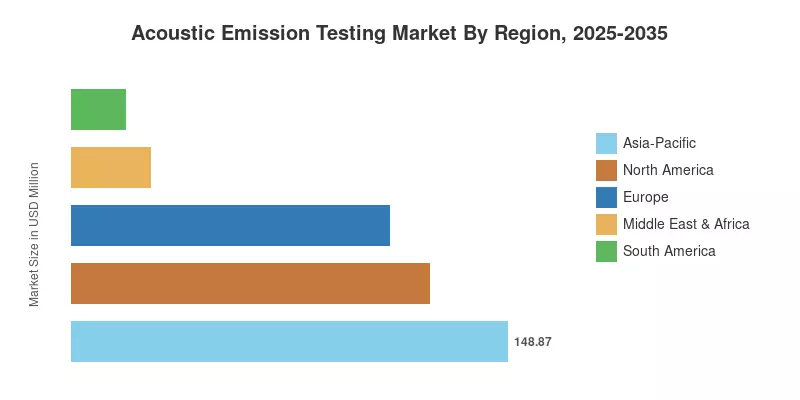
Regionally, Asia-Pacific is the largest market for the Acoustic Emission Testing Market with a share of 34.8% in 2025 and fastest growing at a CAGR of 7.1% due to the growth of the Chinese Petrochemical industry and the pressure-vessel manufacturing base of India. North America – 28.6% (driven by pipeline integrity management standards and nuclear licence renewals) Europe ranks third, thanks to wind blade qualification and hydrogen pilot corridors.
Key Report Takeaways
• By Component
- Sensors held 38.9% of the Acoustic Emission Testing Market in 2025, reflecting the installed base of piezoelectric and emerging MEMS transducers.
- Software is the fastest-expanding component line at a 9.04% CAGR through 2035
- Data acquisition units remain the integration bottleneck, with multi-channel chassis pricing shaping project economics.
• By Portability
- Portable and handheld kits accounted for 41.9% of installations in 2025
- Automated and robotic platforms post the steepest trajectory at a 12.2% CAGR
- Stationary benchtop racks generated USD 147.6 million in 2025 across laboratory and petrochemical continuous-monitoring duty
• By End-User Industry
- Oil and gas contributed 22.6% of the Acoustic Emission Testing Market in 2025
- Automotive and transportation is the fastest-growing vertical at a 10.5% CAGR, led by battery-pack qualification.
- Aerospace demand reached USD 51.3 million in 2025 on composite airframe certification workloads.
• By Region
- Asia-Pacific dominates with a 34.8% share of the Acoustic Emission Testing Market
- Middle East & Africa grows at a 6.3% CAGR on Gulf downstream capacity additions
- Europe generated USD 108.7 Million in 2025
Market Size and Forecast (2021–2035)
Estimates combine bottom-up channel modelling of instrument shipments and service contract values with top-down triangulation against inspection-services revenue disclosures from publicly listed operators. Historical years draw on customs shipment data for transducer and signal-conditioning categories, cross-checked against certification-body activity volumes. Forecast years apply capital-expenditure elasticity to refinery turnaround cycles, grid and nuclear life-extension schedules, and announced battery gigafactory commissioning dates.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



