自動車データ管理市場 (2026 - 2035)

Automotive Data Management Market Research Report By Component Type (Software, Services), By Vehicle Type (Autonomous Vehicles, Non-Autonomous Vehicles), By Deployment Type (Cloud, On-Premise), By Data Type (Structured Data, Unstructured Data) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/AT/28237-HCR 128 Pages Shubham Munde, Sejal Akre Last Updated: September 17, 2026
Automotive Data Management Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)18.5%
2025 Market SizeUSD 2.85 Billion
2035 Market SizeUSD 15.57 Billion
Key Players
Amazon Web Services
Microsoft
IBM
Robert Bosch
Google Cloud
Oracle
Opportunities
  • Compliance-as-a-Service for Mid-Tier OEMs
  • Monetization of Consented Telemetry
  • Emerging-Market Leapfrogging

自動車データ管理市場 概要

主要な市場動向とハイライト

市場規模と予測

CAGR (2025 - 2035) 8.85%

主要なプレーヤー

IBM (US), SAP (DE), Oracle (US), Microsoft (US), Tata Consultancy Services (IN), Capgemini (FR), Deloitte (US), Cognizant (US), HCL Technologies (IN)

自動車データ管理市場 運転手

自動運転車の台頭

自動車データ管理市場は、自動運転車の台頭によって推進されています。自動運転技術の開発が進むにつれて、これらの車両によって生成されるデータの量は前例がありません。自動運転車は、ナビゲートや意思決定を行うために複雑なアルゴリズムと膨大なデータセットに依存しており、洗練されたデータ管理システムが必要です。自動運転車の市場は、10年の終わりまでに数千億ドルに達すると予測されており、効果的なデータ管理ソリューションの需要が必然的に増加します。この傾向は、自動車会社が自動運転車の運用ニーズをサポートするためにデータ管理戦略を優先する必要があることを示しており、その展開における安全性と効率性を確保しています。

車両の接続性の向上

自動車データ管理市場は、車両の接続性の向上に伴い、需要が急増しています。車両がモノのインターネット(IoT)とより統合されるにつれて、生成されるデータの量が増加しています。この接続性により、リアルタイムのデータ収集と分析が可能になり、車両の性能とユーザー体験を向上させるために不可欠です。業界の推定によると、接続された車両の数は2025年までに5億台を超えると予測されており、堅牢なデータ管理ソリューションの必要性を促進しています。その結果、自動車メーカーはこのデータを効果的に活用するためにデータ管理システムに多額の投資を行い、急速に進化する市場で競争力を維持しています。

規制遵守と基準

自動車データ管理市場は、さまざまな規制基準への遵守の必要性によって大きく影響を受けています。政府や規制機関は、自動車部門におけるデータプライバシーとセキュリティに関する厳格な規制を次第に実施しています。例えば、ヨーロッパの一般データ保護規則(GDPR)などの規制は、データの収集、保存、処理方法に関する厳しいガイドラインを課しています。この規制環境は、自動車会社に包括的なデータ管理戦略を採用させ、遵守を確保することを強制し、市場の成長を促進しています。自動車部門における遵守関連の支出は年間数十億ドルに達する可能性があると推定されており、これらの要件を満たす上でのデータ管理の重要な役割を強調しています。

クラウドベースのソリューションの統合

自動車データ管理市場は、データの保存と管理のためにクラウドベースのソリューションをますます採用しています。クラウド技術は、スケーラビリティ、柔軟性、コスト効率を提供し、自動車会社にとって魅力的な選択肢となっています。クラウドベースのプラットフォームを活用することで、メーカーは広範なオンプレミスインフラストラクチャなしで大量のデータを保存および処理できます。このシフトは、リアルタイムでデータにアクセスすることが重要なデータ駆動型モデルに自動車業界が移行する中で特に関連性があります。報告によると、自動車データ管理におけるクラウドセグメントは大幅に成長することが期待されており、多くの企業がデータ管理能力を向上させ、業務を効率化するためにクラウドソリューションに移行しています。

高度な分析の需要の増加

自動車データ管理市場は、高度な分析機能の需要が高まっています。自動車会社がさまざまなソースから膨大なデータを収集するにつれて、このデータを効果的に分析する能力が極めて重要になります。高度な分析は、消費者の行動、車両の性能、メンテナンスニーズに関する洞察を提供し、意思決定プロセスを向上させることができます。市場調査の未来は、自動車データ管理セクター内の分析セグメントが今後数年間で20%以上の年平均成長率(CAGR)で成長することが期待されていると示しています。この傾向は、自動車企業が高度な分析をサポートできる洗練されたデータ管理ソリューションに投資する必要性を強調しており、運用効率と顧客満足度を向上させています。

市場セグメントの洞察

The Automotive Data Management Market is significantly shaped by various applications, with 'self-driving cars' holding the largest market share due to the increasing investments in automated vehicle technologies. 'Telematics' follows closely as a rapidly growing segment, driven by the rising demand for real-time vehicle data and analysis capabilities. Fleet management and predictive maintenance are also noteworthy, providing substantial contributions to the market through their respective applications in enhancing operational efficiency and vehicle performance.

Telematics serves as the dominant segment in the Automotive Data Management Market, capitalizing on the surging demand for connected vehicles and real-time analytics. It encompasses GPS tracking, vehicle diagnostics, and driver behavior monitoring, making it essential for manufacturers and insurers. In contrast, predictive maintenance emerges as a promising value, focusing on data-driven insights to anticipate vehicle issues before they occur. This capability significantly reduces downtime and maintenance costs, ultimately driving operational efficiency within fleets. As technology advances, both sectors are expected to evolve, with telematics refining its data management capabilities while predictive maintenance gains momentum through increasing adoption.

The Automotive Data Management Market is primarily dominated by the Automotive sector, which holds the largest share among various industries. The increasing reliance on advanced data analytics, IoT devices, and connected vehicles propels this sector forward, making it a critical player. The Insurance segment, while smaller in comparison, is rapidly gaining ground, driven by the demand for enhanced risk assessment and personalized insurance solutions backed by data insights.

自動車データ管理市場に関する詳細な洞察を得る

地域の洞察

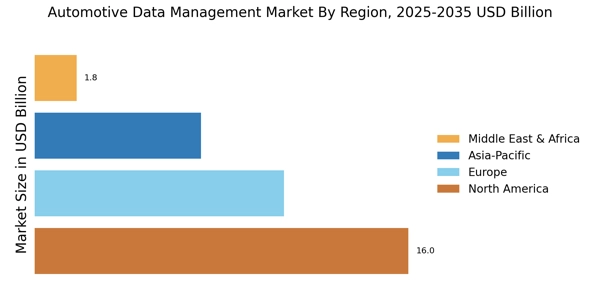
North America : Innovation and Technology Hub

North America is the largest market for Automotive Data Management Market, holding approximately 45% of the global share. The region's growth is driven by rapid technological advancements, increasing vehicle connectivity, and stringent data regulations. The demand for data-driven insights in automotive operations is rising, supported by government initiatives promoting smart transportation systems and data security regulations. The United States and Canada are the leading countries in this market, with major players like IBM, Oracle, and Microsoft establishing a strong presence. The competitive landscape is characterized by continuous innovation and partnerships among tech firms and automotive manufacturers. This collaboration enhances data management capabilities, ensuring compliance with evolving regulations and meeting consumer demands for advanced automotive solutions.

Europe : Regulatory Framework and Growth

Europe is the second-largest market for Automotive Data Management Market, accounting for around 30% of the global market share. The region's growth is propelled by stringent data protection regulations, such as the GDPR, and a strong focus on sustainability in the automotive sector. European governments are investing in smart mobility initiatives, which further drive demand for effective data management solutions in the automotive industry. Leading countries in this region include Germany, France, and the UK, where companies like SAP and Capgemini are key players. The competitive landscape is marked by a mix of established firms and innovative startups, all striving to enhance data management capabilities. The presence of regulatory bodies ensures that data management practices align with legal standards, fostering a secure environment for automotive data usage.

Asia-Pacific : Emerging Market Potential

Asia-Pacific is witnessing significant growth in the Automotive Data Management Market, holding approximately 20% of the global share. The region's expansion is driven by increasing vehicle production, rising consumer demand for connected cars, and government initiatives promoting smart city projects. Countries like China and India are at the forefront, with supportive regulations encouraging technological advancements in the automotive sector. China is the largest market in this region, followed by India, where companies like Tata Consultancy Services and HCL Technologies are making substantial contributions. The competitive landscape is evolving, with both local and international players vying for market share. The focus on innovation and collaboration among automotive manufacturers and tech firms is expected to enhance data management solutions, catering to the growing needs of consumers and businesses alike.

Middle East and Africa : Untapped Market Opportunities

The Middle East and Africa region is gradually emerging in the Automotive Data Management Market, currently holding about 5% of the global share. The growth is driven by increasing investments in infrastructure and a rising number of automotive manufacturers in the region. Governments are also focusing on enhancing transportation systems, which creates a demand for effective data management solutions in the automotive sector. Leading countries include South Africa and the UAE, where there is a growing presence of both local and international players. The competitive landscape is characterized by a mix of established firms and new entrants, all aiming to capitalize on the region's untapped potential. As the automotive industry evolves, the demand for advanced data management solutions is expected to rise, supported by government initiatives and private sector investments.
自動車データ管理市場 Regional Image

主要企業と競争の洞察

The Automotive Data Management Market is currently characterized by a dynamic competitive landscape, driven by the increasing complexity of vehicle data and the growing demand for data-driven insights. Key players are actively engaging in strategies that emphasize innovation, partnerships, and digital transformation to enhance their market positioning. Companies such as IBM (US), SAP (DE), and Oracle (US) are at the forefront, leveraging their technological expertise to provide comprehensive data management solutions tailored for the automotive sector. Their collective focus on integrating advanced analytics and cloud-based services is reshaping the competitive environment, fostering a shift towards more data-centric operational models.In terms of business tactics, companies are increasingly localizing their operations and optimizing supply chains to better serve regional markets. The Automotive Data Management Market appears moderately fragmented, with a mix of established players and emerging startups. This structure allows for a diverse range of solutions, although the influence of major players like Microsoft (US) and Tata Consultancy Services (IN) is significant, as they continue to expand their service offerings and geographic reach.
In August IBM (US) announced a strategic partnership with a leading automotive manufacturer to develop a next-generation data management platform. This collaboration aims to enhance real-time data processing capabilities, which is crucial for the development of autonomous vehicles. The strategic importance of this partnership lies in its potential to set new standards for data interoperability and security within the automotive ecosystem, thereby positioning IBM as a leader in this niche.Similarly, in September 2025, SAP (DE) launched a new suite of data management tools specifically designed for electric vehicle manufacturers. This initiative reflects SAP's commitment to supporting the transition towards sustainable mobility solutions. The introduction of these tools is likely to enhance operational efficiencies and provide manufacturers with the insights needed to optimize their production processes, thereby reinforcing SAP's competitive edge in the market.
In October Microsoft (US) unveiled an advanced analytics platform aimed at improving data utilization for automotive companies. This platform integrates AI and machine learning capabilities, enabling manufacturers to derive actionable insights from vast amounts of data generated by connected vehicles. The strategic significance of this development is profound, as it not only enhances Microsoft's portfolio but also positions the company as a pivotal player in the ongoing digital transformation of the automotive industry.
As of October the competitive trends within the Automotive Data Management Market are increasingly defined by digitalization, sustainability, and the integration of artificial intelligence. Strategic alliances among key players are shaping the landscape, fostering innovation and collaboration. Looking ahead, it is anticipated that competitive differentiation will evolve, with a pronounced shift from price-based competition to a focus on technological innovation, supply chain reliability, and the ability to deliver comprehensive, data-driven solutions.

自動車データ管理市場市場の主要企業には以下が含まれます

Recent Industry Developments

  • Q2 2024: Bosch launches new automotive data platform to support connected vehicles Bosch announced the launch of a new automotive data management platform designed to help automakers and mobility providers manage, analyze, and monetize vehicle data generated by connected cars.
  • Q2 2024: BlackBerry and Elektrobit Partner to Deliver Integrated Automotive Data Management Market Solutions BlackBerry Limited and Elektrobit announced a partnership to integrate BlackBerry IVY with Elektrobit’s automotive software, aiming to provide automakers with enhanced data management and analytics capabilities for next-generation vehicles.
  • Q2 2024: Cognata Raises $25 Million in Series B Funding to Expand Automotive Data Simulation Platform Cognata, a provider of simulation platforms for automotive data management and autonomous vehicle development, secured $25 million in Series B funding to accelerate product development and global expansion.
  • Q3 2024: Otonomo and AWS Announce Strategic Collaboration to Enhance Automotive Data Services Otonomo Technologies and Amazon Web Services (AWS) announced a strategic collaboration to deliver advanced automotive data management and analytics services, leveraging AWS cloud infrastructure for scalability and security.
  • Q3 2024: Renesas Electronics Launches New Automotive Data Management Market Chipset Renesas Electronics introduced a new chipset designed for automotive data management, enabling real-time processing and secure storage of large volumes of vehicle-generated data.
  • Q3 2024: Volkswagen Group Opens Data Innovation Center in Munich Volkswagen Group inaugurated a new Data Innovation Center in Munich focused on developing advanced automotive data management solutions and supporting the company’s digital transformation initiatives.
  • Q4 2024: Wejo Announces Partnership with Microsoft to Advance Automotive Data Analytics Wejo, a connected vehicle data company, announced a partnership with Microsoft to leverage Azure cloud services for enhanced automotive data analytics and management solutions.
  • Q4 2024: Harman Acquires Savari to Strengthen Automotive Data Management Market Capabilities Harman, a subsidiary of Samsung, acquired Savari, a provider of vehicle-to-everything (V2X) communications technology, to bolster its automotive data management and connected vehicle offerings.
  • Q1 2025: Continental Appoints New Head of Automotive Data Solutions Division Continental AG announced the appointment of Dr. Maria Klein as the new head of its Automotive Data Solutions division, responsible for driving innovation in vehicle data management.
  • Q1 2025: Aptiv Launches Next-Generation Automotive Data Management Market Platform Aptiv PLC unveiled its next-generation automotive data management platform, designed to support the growing data needs of electric and autonomous vehicles.
  • Q2 2025: NXP Semiconductors and Arm Collaborate on Automotive Data Security Solutions NXP Semiconductors and Arm announced a collaboration to develop secure automotive data management solutions, focusing on protecting vehicle data from cyber threats.
  • Q2 2025: General Motors Invests in Automotive Data Startup to Boost Connected Vehicle Services General Motors announced a strategic investment in a Silicon Valley-based automotive data management startup to enhance its connected vehicle services and data analytics capabilities.

今後の見通し

自動車データ管理市場 今後の見通し

自動車データ管理市場は、2025年から2035年まで8.85%のCAGRで成長すると予測されており、データ分析の進展、車両の接続性の向上、規制遵守の要求が推進要因となっています。

新しい機会は以下にあります:

  • AI駆動の予測保守ソリューションの開発

2035年までに、市場は革新と戦略的パートナーシップによって堅調な成長が期待されています。

市場セグメンテーション

自動車データ管理市場の業界展望

  • 自動車
  • 保険
  • 物流
  • 輸送
  • 製造

自動車データ管理市場のデータタイプ展望

  • 車両センサーデータ
  • GPSデータ
  • カメラデータ
  • テレマティクスデータ
  • 使用データ

自動車データ管理市場の展開展望

  • クラウド
  • オンプレミス
  • ハイブリッド

自動車データ管理市場のアプリケーション展望

  • 自動運転車
  • テレマティクス
  • フリート管理
  • 予測保守
  • 使用ベースの保険

自動車データ管理市場のデータ管理ツール展望

  • データレイク
  • データウェアハウス
  • ビッグデータ分析
  • 機械学習
  • 人工知能

レポートの範囲

Parameter Detail
Market Scope Global Automotive Data Management Market across component, vehicle, deployment, and data types
Study Period 2021–2035 (historical 2021–2024; base 2025; forecast 2026–2035)
CAGR 18.5% (2026–2035)
Market Size Checkpoints USD 2.85 Billion (2025); USD 3.38 Billion (2026); USD 15.57 Billion (2035)
Fastest Growing Segments Unstructured Data; Autonomous Vehicles; Cloud Deployment
Companies Profiled 11 primary vendors plus 14 secondary participants
Valuation Currency USD Billion, constant 2025 dollars
CAGR Driver Disclaimer Driver and restraint impact percentages are directional weightings, not additive components of the compound growth rate

Frequently Asked Questions

2035年までの自動車データ管理市場の予想市場評価額は何ですか?

自動車データ管理市場の予想市場評価額は2035年までに905.3億米ドルに達すると予想されています。

2024年の自動車データ管理市場の市場評価額は何でしたか?

自動車データ管理市場の全体的な市場評価額は2024年に356.1億米ドルでした。

2025年から2035年の予測期間中の自動車データ管理市場の期待CAGRは何ですか?

2025年から2035年の予測期間中の自動車データ管理市場の期待CAGRは8.85%です。

自動車データ管理市場の主要プレーヤーと見なされる企業はどれですか?

自動車データ管理市場の主要プレーヤーにはIBM、SAP、Oracle、Microsoft、Tata Consultancy Services、Capgemini、Deloitte、Cognizant、HCL Technologiesが含まれます。

自動車データ管理市場における自動運転車の予想評価額は何ですか?

自動車データ管理市場における自動運転車の予想評価額は50億米ドルから150億米ドルの範囲です。

テレマティクスセグメントの市場評価はどのように推移していますか?

テレマティクスセグメントの市場評価は100億米ドルから250億米ドルの範囲になると予想されています。

自動車データ管理市場におけるクラウド展開の期待市場規模は何ですか?

自動車データ管理市場におけるクラウド展開の期待市場規模は100億米ドルから250億米ドルの範囲です。

自動車データ管理市場における車両センサーデータの評価範囲は何ですか?

自動車データ管理市場における車両センサーデータの評価範囲は100億米ドルから250億米ドルになると予想されています。

データ管理ツールとしてのビッグデータ分析の期待評価額は何ですか?

データ管理ツールとしてのビッグデータ分析の期待評価額は100億米ドルから250億米ドルの範囲です。

自動車データ管理市場の成長を促進することが期待される業界セグメントはどれですか?

自動車、保険、物流、輸送、製造などの業界セグメントが自動車データ管理市場の成長を促進すると期待されています。

著者
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, technical standards, and authoritative automotive and technology organizations. Key sources included the US Department of Transportation (DOT), National Highway Traffic Safety Administration (NHTSA), European Automobile Manufacturers Association (ACEA), Society of Automotive Engineers (SAE International), International Organization for Standardization (ISO) technical committees for automotive standards, National Institute of Standards and Technology (NIST), European Union Agency for Cybersecurity (ENISA), US National Telecommunications and Information Administration (NTIA) connected vehicle standards, International Data Corporation (MRFR), MRFR Research, IEEE Xplore Digital Library, OICA (International Organization of Motor Vehicle Manufacturers) production statistics, EU Eurostat Transport Database, and national transport ministry reports from key markets. These sources were used to collect vehicle connectivity statistics, autonomous vehicle testing data, telematics adoption rates, cybersecurity compliance frameworks, data governance regulations, and market landscape analysis for cloud-based data management, on-premises deployment, and hybrid solutions across self-driving cars, fleet management, predictive maintenance, and usage-based insurance applications.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Data Strategy, heads of Connected Car Platforms, and commercial directors from cloud infrastructure providers, automotive OEMs, and providers of automotive data management software were examples of supply-side sources. Chief data officers, fleet operations managers, insurance underwriting directors, heads of logistics technology, and procurement leaders from automakers, insurance firms, fleet management organizations, and transportation and logistics companies were examples of demand-side sources. Primary study verified autonomous vehicle data pipeline timings, validated market segmentation across deployment types (cloud, on-premises, and hybrid), and acquired information on data monetization tactics, cybersecurity investment trends, and regulatory compliance dynamics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and data volume analysis. The methodology included:

Identification of 50+ key technology providers and automotive data platforms across North America, Europe, Asia-Pacific, and Latin America

Product mapping across data lakes, data warehouses, big data analytics, machine learning, and artificial intelligence tools

Segment analysis covering vehicle sensor data, GPS data, camera data, telematics data, and usage data processing solutions

Analysis of reported and modeled annual revenues specific to automotive data management portfolios

Coverage of providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (connected vehicle data volume × processing cost by region) and top-down (technology provider revenue validation) approaches to derive segment-specific valuations for self-driving cars, telematics, fleet management, predictive maintenance, and usage-based insurance

無料サンプルをダウンロード

このレポートの無料サンプルを受け取るには、以下のフォームにご記入ください

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.