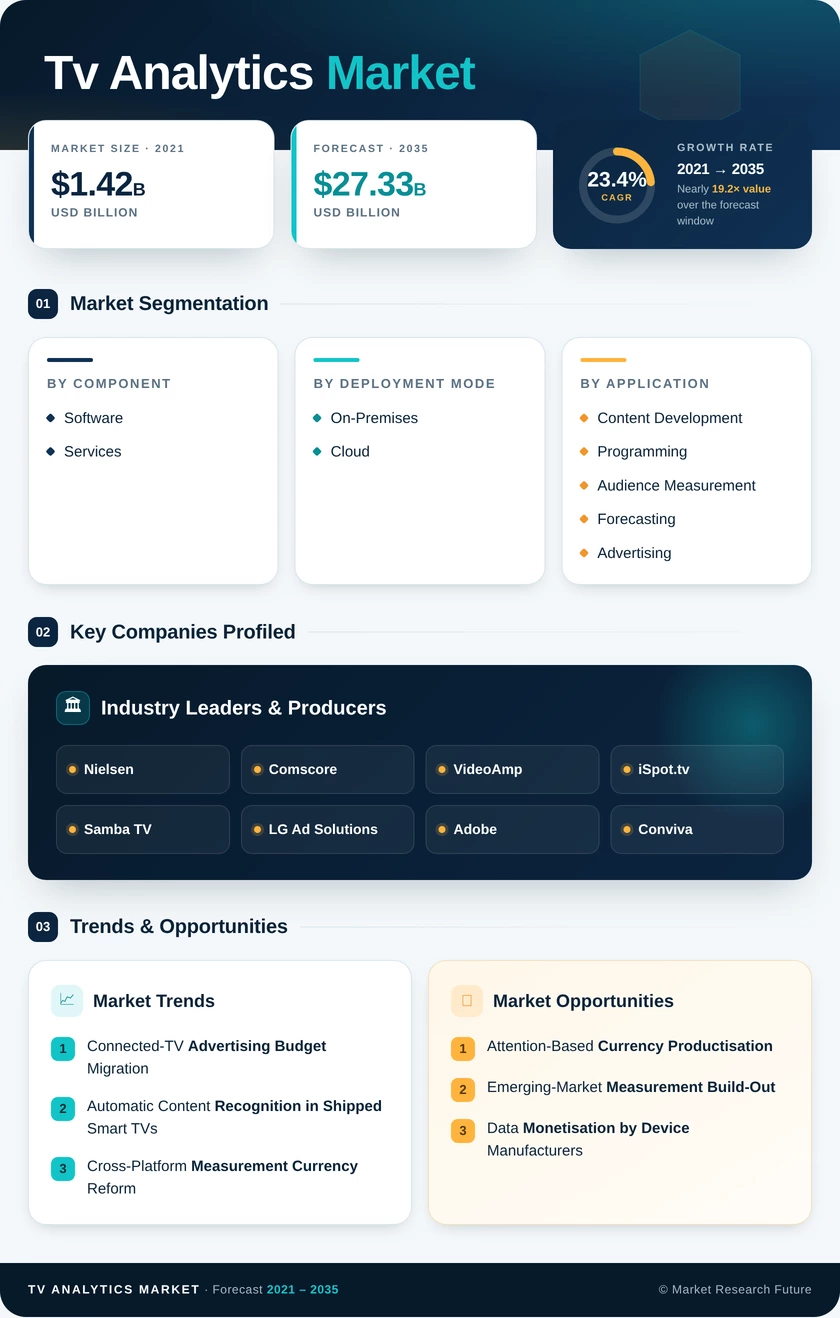
Market Segmentation Analysis
By Component
9.1.1 Software
9.1.2 Services
By Deployment Mode
9.2.1 On-Premises
9.2.2 Cloud
By Application
9.3.1 Content Development and Programming
9.3.2 Audience Measurement and Forecasting
9.3.3 Advertising and Marketing
9.3.4 Recommendation and Personalization Engines
9.3.5 Other Applications
By End User
9.4.1 Broadcasters and Networks
9.4.2 OTT/Streaming Service Providers
9.4.3 Telecom and Cable Operators
9.4.4 Smart-TV OEMs
9.4.5 Other End Users
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Software; Services | Software (50.4% share, 2025) | Services (19.9% CAGR, 2026–2035) |
| By Deployment Mode | On-Premises; Cloud | On-Premises (41.4% share, 2025) | Cloud (22.1% CAGR, 2026–2035) |
| By Application | Content Development and Programming; Audience Measurement and Forecasting; Advertising and Marketing; Recommendation and Personalization Engines; Other Applications | Advertising and Marketing (38.6% share, 2025) | Recommendation and Personalization Engines (22.4% CAGR, 2026–2035) |
| By End User | Broadcasters and Networks; OTT/Streaming Service Providers; Telecom and Cable Operators; Smart-TV OEMs; Other End Users | OTT/Streaming Service Providers (36.1% share, 2025) | Smart-TV OEMs (24.3% CAGR, 2026–2035) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Software | Shift from perpetual dashboard licences to consumption-priced processing engines |
| Services | Growth in consulting, implementation, and managed insight retainers |
Software holds the larger revenue base because broadcasters bought tooling before they built teams, and licensed processing engines remain the entry point for most first-time deployments. Services grow faster at a 19.9% CAGR because integration across ad servers, subscriber systems, and device telemetry demands specialist labour that mid-tier buyers cannot recruit. Vendors increasingly wrap both into multi-year retainers, which improves renewal rates and makes the services line the primary vehicle for account expansion.
By Deployment Mode
| Sub-Segment | Key Trend |
| Cloud | Elastic compute and integrated AI accelerators compress time-to-value |
| On-Premises | Retained for sovereign-data mandates and ultra-low-latency workloads |
Cloud is the growth engine at a 22.1% CAGR because campaign volumes swing sharply and usage-based pricing absorbs that volatility better than provisioned hardware. On-Premises still holds 41.4% of 2025 revenue, concentrated among public broadcasters and state-linked operators bound by residency rules that commercial cloud regions cannot satisfy. Refresh capital requirements deter new on-premises installations, so its share declines steadily even where absolute spend remains stable.
By Application
| Sub-Segment | Key Trend |
| Content Development and Programming | Analytics moving upstream into commissioning and greenlight decisions |
| Audience Measurement and Forecasting | Transition from panel sampling to hybrid census-plus-panel currencies |
| Advertising and Marketing | Impression-level verification embedded in transactional contracts |
| Recommendation and Personalization Engines | Retention modelling tied directly to watch-time and churn outcomes |
| Other Applications | Churn scoring, lifetime-value modelling, and competitive intelligence |
Advertising and Marketing leads at 38.6% because verification is contractually required and funded from media budgets, making it the least discretionary spend in the category. Recommendation and Personalization Engines grow fastest at 22.4% as platforms recognise that incremental watch hours simultaneously expand ad inventory and suppress cancellation, producing measurable lifetime-value gains. Content Development and Programming remains the most underpenetrated block relative to the roughly USD 90 billion in annual content commitments it could inform.
By End User
| Sub-Segment | Key Trend |
| Broadcasters and Networks | Defensive spending to maintain currency compliance during digital transition |
| OTT/Streaming Service Providers | Data-dependent programming, pricing, and retention operations |
| Telecom and Cable Operators | Monetisation of set-top telemetry and bundle optimisation |
| Smart-TV OEMs | Operating-system telemetry converted into advertising and licensing revenue |
| Other End Users | Agencies, brands, and sports-rights holders buying verification |
OTT/Streaming Service Providers dominate at 36.1% because subscription businesses run every core decision — pricing, programming, retention — off the same telemetry, so analytics is operational rather than optional. Smart-TV OEMs grow fastest at 24.3% as manufacturers convert one-time hardware margin into recurring advertising and data-licensing income drawn from native operating systems. Broadcasters and Networks spend substantially but defensively, funding measurement to protect existing revenue, which keeps their contracts long but their pricing tolerance comparatively low.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA