Smart Harvest Market

Smart Harvest Market Size, Share, Industry Trend & Analysis Research Report By Farm Size (Small Farms (50 acres), Medium Farms (50-200 acres), Large Farms (>200 acres)), By Crop Type (Fruits and Vegetables, Grains and Pulses, Oilseeds and Nuts), By Automation Level (Semi-Automated, Fully Automated), By Application (Harvesting, Planting, Cultivation, Irrigation) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035

ID: MRFR/Agri/21473-HCR 128 Pages Snehal Singh, Tejas Chaudhary Last Updated: September 17, 2026
Smart Harvest Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)11.73%
2024 Market Size$ 2.52 Billion
2025 Market Size$ 2.82 Billion
2035 Market Size$ 8.55 Billion
Key Players
Companies such as John Deere
Trimble
AG Leader Technology
Raven Industries
BASF
CNH Industrial
Opportunities
  • Integration of Advanced Data Analytics
  • Government Support and Policy Initiatives
  • Growing Consumer Demand for Organic Produce

Smart Harvest Market Summary

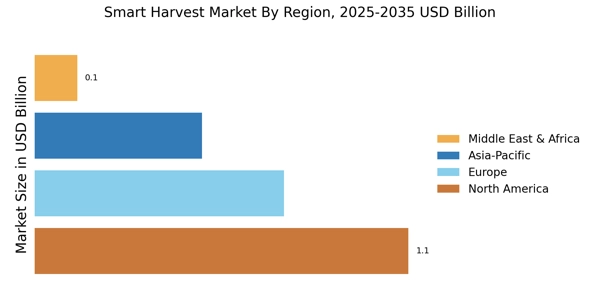
The Global Smart Harvest Market size was valued at USD 2.525 Billion in 2024, and the market is projected to grow from USD 2.821 Billion in 2025 to USD 8.554 Billion by 2035, registering a CAGR of 11.73% during the forecast period 2025–2035. North America led the market in 2024 with over 43.56% share, generating around USD 1.1 Billion in revenue.
The Smart Harvest Market is primarily driven by the growing need to improve agricultural productivity through precision farming and automation. Smart harvesting technologies enable real-time crop monitoring, optimize resource utilization, reduce labor dependency, and enhance harvesting efficiency, supporting sustainable food production amid rising global food demand.
According to FAO projections, global agricultural production must increase by approximately 60% by 2050 to meet rising food demand from population growth. This accelerating need for higher productivity is encouraging wider adoption of smart harvesting technologies, including IoT-enabled monitoring, AI-driven automation, and precision agriculture solutions that improve crop yields while optimizing resource efficiency.

Key Market Trends & Highlights

The Smart Harvest Market is poised for substantial growth driven by technological advancements and increasing consumer demand.

  • North America led the market with over 43.56% of global revenue in 2024.
  • Europe accounted for 30% of the global market, reaching USD 0.76 billion in 2024, making it the second-largest regional market.
  • Fully automated solutions represented nearly 58% of the automation segment, driven by increasing investments in AI-enabled machinery, autonomous equipment, and precision guidance systems.
  • Global organic farmland exceeded 96 million hectares, while the organic food market surpassed EUR 136 billion, accelerating demand for smart harvesting technologies supporting sustainable agriculture.

Market Size & Forecast

2024 Market Size 2.525 (USD Billion)
2035 Market Size 8.554 (USD Billion)
CAGR (2025 - 2035) 11.73%

Major Players

Companies such as John Deere (US), Trimble (US), AG Leader Technology (US), Raven Industries (US), BASF (DE), CNH Industrial (GB), Yara International (NO), Deere & Company (US), Topcon Positioning Systems (JP) are some of the major participants in the global market.

Smart Harvest Market Drivers

Integration of Advanced Data Analytics

The Smart Harvest Industry is increasingly influenced by the integration of advanced data analytics. This technology enables farmers to collect and analyze vast amounts of data from various sources, including soil sensors, weather forecasts, and crop health monitoring systems. By leveraging this data, farmers can make informed decisions regarding planting, irrigation, and harvesting, ultimately enhancing yield and reducing waste.
The market for agricultural analytics is projected to grow significantly, with estimates suggesting a compound annual growth rate of over 20% in the coming years. This trend indicates a shift towards data-driven farming practices, which are likely to become a cornerstone of the market.
  • John Deere continues product development and innovation by expanding its digital farming ecosystem through the John Deere Operations Center, enabling farmers to analyze machine, field, and agronomic data in real time. The company has also strengthened strategic partnerships and collaborations with technology providers to enhance precision farming capabilities. According to the USDA, approximately 61% of U.S. corn acreage and 64% of soybean acreage utilize GPS guidance systems, demonstrating the increasing adoption of data-driven agricultural technologies that support smart harvesting.

Government Support and Policy Initiatives

Government support and policy initiatives play a significant role in shaping the Smart Harvest Industry. Various governments are implementing policies that promote the adoption of smart farming technologies, including subsidies for purchasing advanced equipment and funding for research and development. 
For instance, initiatives aimed at enhancing agricultural productivity and sustainability are being prioritized, which could lead to increased investment in smart harvesting solutions. The financial backing from governmental bodies is likely to stimulate innovation and adoption rates, thereby propelling the market forward. This supportive environment is essential for fostering advancements in agricultural technology.

Growing Consumer Demand for Organic Produce

The rising consumer demand for organic produce is a notable driver in the Smart Harvest Industry. As consumers become more health-conscious and environmentally aware, the preference for organic products continues to surge. This trend compels farmers to adopt smart harvesting technologies that can efficiently produce organic crops while adhering to strict regulations. 
The organic food market is projected to grow at a robust pace, with estimates indicating a potential doubling in size over the next decade. This shift not only influences farming practices but also encourages the integration of smart technologies in the harvesting process, thereby enhancing the overall efficiency of the market.
  • Trimble has strengthened its precision agriculture portfolio through mergers, acquisitions, and portfolio expansion, enabling broader access to connected farming technologies. The company also benefits from government-supported digital agriculture initiatives and evolving regulatory advancements encouraging precision farming adoption. According to the European Commission, the Common Agricultural Policy (CAP) 2023–2027 allocates approximately EUR 387 billion to support sustainable and digital agriculture, creating favorable conditions for smart harvesting technologies.

Adoption of Precision Agriculture Techniques

Precision agriculture techniques are becoming a pivotal driver in the Smart Harvest Industry. These methods utilize technology such as GPS, drones, and remote sensing to optimize field-level management regarding crop farming. By applying inputs like water, fertilizers, and pesticides more efficiently, farmers can enhance productivity while minimizing environmental impact.
Reports indicate that the precision agriculture market is expected to reach several billion dollars by 2026, reflecting a growing recognition of its benefits. This trend not only supports sustainable farming practices but also aligns with the increasing demand for food security, making it a crucial aspect of the market.

Technological Advancements in Robotics and Automation

Technological advancements in robotics and automation are transforming the Smart Harvest Industry. The development of sophisticated robotic systems capable of performing tasks such as planting, monitoring, and harvesting crops is gaining traction. These innovations promise to reduce labor costs and increase efficiency, addressing labor shortages that many agricultural sectors face. 
The market for agricultural robots is anticipated to witness substantial growth, with projections suggesting a significant increase in adoption rates over the next few years. This evolution in technology not only streamlines operations but also enhances the precision and effectiveness of harvesting processes, marking a critical evolution in the market.

Market Segment Insights

By Farm Size: Small Farms (Largest) vs. Large Farms (Fastest-Growing)

In the Smart Harvest Market, the distribution among farm sizes reveals that small farms hold the largest share, at 63%, reflecting their significant adaptation to smart technologies. These farms, often driven by a need for efficiency, have embraced smart harvest solutions to maximize productivity within their limited resources. Meanwhile, large farms are the fastest-growing segment, capitalizing on scale and advanced technologies to enhance operational efficiency, further driving their market presence.

Deere & Company continues product development and innovation by expanding compact precision agriculture solutions, including AutoTrac guidance and Operations Center tools tailored for small and medium-sized farms. According to the USDA Census of Agriculture 2022, the United States has 1.9 million farms, with over 95% classified as family-owned operations, highlighting the substantial customer base driving smart harvesting technology adoption among smaller farms.

By Crop Type: Fruits and Vegetables (Largest) vs. Oilseeds and Nuts (Fastest-Growing)

In the Smart Harvest Market, Fruits and Vegetables hold the largest market share at 47% among various crop types, making them the leading segment. This can be attributed to their increasing demand for sustainable farming practices and technological advancements. Following closely, Oilseeds and Nuts are gaining traction, indicating a growing consumer preference and a surge in innovative harvesting techniques that cater to these crops in response to market demands.

BASF is advancing precision crop management through digital farming solutions and crop protection innovations designed for high-value fruit and vegetable cultivation. The FAO estimates global fruit and vegetable production exceeds 2 billion tonnes annually, reinforcing the growing need for smart harvesting technologies that improve harvesting efficiency, quality, and post-harvest management.

By Automation Level: Fully Automated (Largest) vs. Semi-Automated (Fastest-Growing)

The automation level segment in the Smart Harvest Market reveals distinct patterns in market share distribution, with a 58% share. The Fully Automated systems hold a significant portion of the market due to their high efficiency and reduced labor costs. These systems are increasingly being adopted by larger agricultural enterprises that require advanced technology to streamline operations. On the other hand, Semi-Automated solutions are gaining traction among smaller farms and agricultural operations looking for a balanced approach that combines technology with human oversight.

Topcon Positioning Systems continues product development and innovation by enhancing GNSS-guided automation, machine control, and precision positioning technologies for autonomous harvesting equipment. According to the International Federation of Robotics (IFR), global professional service robot sales increased by 30% in the latest reporting period, reflecting accelerating investment in agricultural automation and autonomous field operations.

By Application: Harvesting (Largest) vs. Planting (Fastest-Growing)

The Smart Harvest Market reveals a diverse application landscape, with harvesting technologies commanding the largest market share at 54%. Harvesting holds a significant position due to its established technologies and the immediate impact on yield and efficiency that farmers seek. Planting, while not the largest, is recognized as the fastest-growing segment, fueled by innovations that enhance crop rotation and seed utilization efficiency, resonating well with the increasing demand for optimized agricultural practices. In recent years, the Smart Harvest Market has seen substantial growth in the planting sector, prompted by advancements in precision agriculture and automation. The drive towards sustainable farming solutions has led to increased investment in planting technologies that bolster crop yield and minimize resource input. Moreover, heightened awareness of environmental impacts aligns with growing interest in innovative planting solutions, positioning it as a focal point for future growth within the market.

CNH Industrial continues expanding its precision harvesting portfolio through advanced combine automation, telematics, and AI-assisted harvesting technologies. The company's smart harvesting innovations improve operational efficiency and reduce grain losses. According to the Association of Equipment Manufacturers (AEM), the U.S. agricultural equipment industry contributes more than USD 180 billion annually to the national economy, supporting continued investment in advanced harvesting machinery.

Get more detailed insights about Smart Harvest Market

Regional Insights

North America : Innovation and Technology Leader

North America is the largest market for smart harvesting technologies, holding approximately 45% of the global market share. The region's growth is driven by advancements in agricultural technology, increasing demand for food production, and supportive government policies promoting sustainable farming practices. Regulatory frameworks are evolving to encourage the adoption of precision agriculture, enhancing efficiency and productivity.

  • North America maintains its leadership in smart harvesting through strong investment in precision agriculture and connected farm technologies. Raven Industries has strengthened its precision agriculture portfolio through advanced autonomous guidance, machine control, and digital farming innovations, supporting higher operational efficiency. According to the USDA Census of Agriculture 2022, the United States operates 1.9 million farms across approximately 880 million acres of farmland, providing a substantial foundation for large-scale deployment of smart harvesting solutions. Additionally, CDC data continue to support agricultural worker safety initiatives that encourage greater mechanization and automation across farming operations.

The United States is the leading country in this sector, with major players like John Deere, Trimble, and AG Leader Technology dominating the landscape. The competitive environment is characterized by continuous innovation and partnerships among technology providers and agricultural firms. Canada also plays a significant role, contributing to the market with its focus on sustainable practices and technological integration.

Europe : Sustainable Agriculture Focus

Europe is the second-largest market for smart harvesting, accounting for about 30% of the global share. The region's growth is fueled by stringent regulations aimed at promoting sustainable agricultural practices and reducing environmental impact. The European Union's Common Agricultural Policy (CAP) encourages the adoption of innovative technologies, driving demand for smart harvesting solutions across member states.

  • Europe continues to expand the adoption of smart harvesting technologies through sustainability-focused agricultural policies and digital transformation initiatives. Companies such as BASF and CNH Industrial are investing in precision farming innovations that align with the European Union's environmental objectives. According to the European Medicines Agency (EMA), the agency evaluated 114 marketing authorization applications for human medicines in 2023, reflecting Europe's strong regulatory framework and commitment to science-driven innovation. Combined with the EU Common Agricultural Policy (CAP) 2023–2027 budget of approximately EUR 387 billion, this environment supports continued investment in advanced smart harvesting technologies.

Leading countries in Europe include Germany, France, and the Netherlands, where companies like BASF and CNH Industrial are making significant strides. The competitive landscape is marked by a strong emphasis on research and development, with numerous startups emerging alongside established firms. The presence of key players fosters collaboration and innovation, enhancing the region's market dynamics.

Asia-Pacific : Emerging Market Potential

Asia-Pacific is witnessing rapid growth in the smart harvesting market, holding approximately 20% of the global share. The region's expansion is driven by increasing agricultural productivity demands, urbanization, and the need for efficient resource management. Governments are implementing policies to support technological advancements in agriculture, which is further propelling market growth.

Countries like China, India, and Japan are at the forefront of this transformation, with significant investments in smart farming technologies. Key players such as Yara International and Topcon Positioning Systems are actively participating in the market, enhancing their presence through strategic partnerships and innovations. The competitive landscape is evolving, with a mix of local and international firms driving advancements in smart harvesting solutions.

Middle East and Africa : Resource Management Challenges

The Middle East and Africa region is gradually emerging in the smart harvesting market, currently holding about 5% of the global share. The growth is primarily driven by the need for efficient water management and sustainable agricultural practices in arid regions. Governments are increasingly recognizing the importance of technology in addressing food security challenges, leading to supportive policies and initiatives.

Countries like South Africa and Kenya are leading the charge, with local firms and international players collaborating to introduce smart harvesting technologies. The competitive landscape is characterized by a mix of established agricultural companies and innovative startups. This region's unique challenges present opportunities for growth, as stakeholders seek to implement solutions that enhance productivity and sustainability.
Smart Harvest Market Regional Image

Key Players and Competitive Insights

Smart Harvest Market industry major players are constantly striving to gain a competitive edge through investment in research and development, expanding product portfolios, and making strategic alliances. Manufacturers are focusing on developing products that are in sync with the changing demands of farmers and the Agriculture sector. Further, market development in technology is also driving market growth, as farmers need new machines and equipment that are more efficient and cost-effective.
Indeed, the nature of the market is such that the share of profit is limited, and the number of competitors is gradually increasing by leaps and bounds. As demand picks up, new players enter the market with competitive pricing strategies, resulting in a diminishing market value for major players.Blue River Technology is one of the major providers of smart harvest solutions whose products range from lettuce thinners to robotic implement carriers, with all systems using computer vision and machine learning to identify and target weed plants.
Overall, the company has had an initial public offering and has implemented its solutions worldwide in major agriculture production companies. Further, the company has not stopped engaging in more research to develop other products and weed lines.
The second major player in the market is Abundant Robotics, whose product is an apple picker that can use computer vision combined with robotic manipulation and artificial intelligence to target and pluck a ripe apple. The advantage of this element is that it is gentle on the trees and the fruit and can pluck up to one apple per second. You can also check other manufacturers, for example, AGCO Corporation, Deere Company, and CNH Industrial.

Key Companies in the Smart Harvest Market include

Recent Industry Developments

The  smart harvest market is projected to reach USD 5.5 billion by 2032, exhibiting a CAGR of 11.73% during the forecast period. Growing demand for precision farming technologies to enhance crop yield and reduce costs is driving market growth. Government initiatives to promote sustainable agriculture practices and the rising adoption of IoT sensors and data analytics in the agricultural sector are further contributing to market expansion. Key recent developments include the launch of new smart harvest solutions by major players such as John Deere and AGCO, and strategic partnerships between technology providers and agricultural cooperatives to drive innovation and adoption.

The market is expected to witness significant growth in developing regions such as Asia-Pacific and Latin America, where governments are actively investing in agricultural modernization and precision farming technologies.

Future Outlook

Smart Harvest Market Future Outlook

The Smart Harvest Market size is projected to reach USD 8.554 Billion by 2035, growing at a CAGR of 11.73%, driven by technological advancements, increasing demand for efficiency, and sustainability initiatives.

New opportunities lie in:

  • Integration of AI-driven analytics for crop yield optimization. Development of autonomous harvesting equipment for labor cost reduction. Expansion of precision agriculture solutions to enhance resource management.

By 2035, the Smart Harvest Market is expected to be robust, driven by innovation and increased adoption of smart technologies.

Market Segmentation

Smart Harvest Market Crop Type Outlook

  • Fruits and Vegetables
  • Grains and Pulses
  • Oilseeds and Nuts

Smart Harvest Market Farm Size Outlook

  • Small Farms
  • Medium Farms
  • Large Farms

Smart Harvest Market Application Outlook

  • Harvesting
  • Planting
  • Cultivation
  • Irrigation

Smart Harvest Market Automation Level Outlook

  • Semi-Automated
  • Fully Automated

Report Scope

MARKET SIZE 2024 2.525(USD Billion)
MARKET SIZE 2025 2.821(USD Billion)
MARKET SIZE 2035 8.554(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 11.73% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled John Deere (US), Trimble (US), AG Leader Technology (US), Raven Industries (US), BASF (DE), CNH Industrial (GB), Yara International (NO), Deere & Company (US), Topcon Positioning Systems (JP)
Segments Covered Farm Size, Crop Type, Automation Level, Application, Regional
Key Market Opportunities Integration of artificial intelligence and automation enhances efficiency in the Smart Harvest Market.
Key Market Dynamics Technological advancements drive efficiency in the Smart Harvest Market, reshaping competitive dynamics and consumer preferences.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

What is the projected market valuation of the Smart Harvest Market by 2035?

The Smart Harvest Market is projected to reach a valuation of 8.554 USD Billion by 2035.

What was the market valuation of the Smart Harvest Market in 2024?

In 2024, the Smart Harvest Market had a valuation of 2.525 USD Billion.

What is the expected CAGR for the Smart Harvest Market during the forecast period 2025 - 2035?
The expected CAGR for the Smart Harvest Market during the forecast period 2025 - 2035 is 11.73%.
Which companies are considered key players in the Smart Harvest Market?
Key players in the Smart Harvest Market include John Deere, Trimble, AG Leader Technology, and BASF, among others.
How does the Smart Harvest Market segment by farm size?
The Smart Harvest Market segments by farm size into Small Farms, Medium Farms, and Large Farms, with valuations ranging from 0.505 to 4.117 USD Billion.
What crop types are included in the Smart Harvest Market segmentation?
The Smart Harvest Market segments by crop type, including Fruits and Vegetables, Grains and Pulses, and Oilseeds and Nuts, with valuations from 0.7575 to 3.2615 USD Billion.
What are the automation levels in the Smart Harvest Market?
The Smart Harvest Market is segmented by automation level into Semi-Automated and Fully Automated, both valued at 1.2625 to 4.277 USD Billion.
What applications are covered in the Smart Harvest Market?
Applications in the Smart Harvest Market include Harvesting, Planting, Cultivation, and Irrigation, with valuations ranging from 0.505 to 2.6465 USD Billion.
What is the significance of the Smart Harvest Market's growth from 2024 to 2035?
The Smart Harvest Market is expected to grow significantly from 2.525 USD Billion in 2024 to 8.554 USD Billion by 2035, indicating robust demand.
How do the valuations of different farm sizes compare in the Smart Harvest Market?
In the Smart Harvest Market, Large Farms are valued at 4.117 USD Billion, Medium Farms at 2.662 USD Billion, and Small Farms at 1.775 USD Billion.
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Co-Author Co-Author Profile Tejas Chaudhary Research Analyst Level II
I have a degree in Engineering (Civil), with masters in Business Administration (Marketing). With more than 4 years of experience in market research and consulting, I am involved in end-to-end process of market research, proposals, project kickoffs and delivery. I have research knowledge and expertise in consumer goods/packaging domain. Also I have worked for various other domains like construction & equipment. Effectively managed and delivered more than 60 report studies for regional as well as global clientele.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.