Small Molecule API Market (2026 - 2035)

Small Molecule API Market Research Report: Size, Share, Trend Analysis By Applications (Oncology, Cardiovascular, Diabetes, Neurology), By Types (Generic, Branded, Novel), By Formulation (Oral, Injectable, Topical, Inhalation), By End Use (Pharmaceutical Industry, Research Institutions, Contract Manufacturing Organizations) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/HC/0279-CR 200 Pages Rahul Gotadki, Kinjoll Dey Last Updated: September 15, 2026
Small Molecule API Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.92%
2025 Market SizeUSD 160.24 Billion
2035 Market SizeUSD 335.86 Billion
Key Players
Lonza Group AG
Teva API
Dr. Reddy's Laboratories
Aurobindo Pharma
Sun Pharmaceutical Industries
Divi's Laboratories
Opportunities
  • Friend-Shored Regulated-Market Capacity
  • Peptide and Oligonucleotide Substance Capability
  • Emerging-Market Domestic Substance Manufacturing

Small Molecule API Market Summary

The Small Molecule API Market reached USD 160.24 billion in 2025 and opens the forecast window at USD 183.31 billion in 2026, climbing to USD 335.86 billion by 2035 at a 6.92% CAGR. Two catalysts anchor that trajectory. The first is the chronic disease load — the World Health Organization counted 20.6 million new cancer cases on a 2024 base and projects close to 35 million by 2050 [1]. The second is capital: India's Production Linked Incentive scheme for bulk drugs committed roughly USD 830 million to domestic fermentation and chemical synthesis capacity, and Pfizer alone put USD 465 million into its Kalamazoo, Michigan site [3][7].

Manufacturing itself is evolving. Continuous-flow lines, biocatalytic stages, and process analytical technology that maintain impurity profiles within tightening nitrosamine limits are replacing batch reactor trains constructed for generics in the 1990s. The US FDA's Advanced Manufacturing Technologies designation program, which was established in 2024, has become the practical method for qualifying these installations [4]. Sponsors are increasingly purchasing that capability rather than developing it, which is why the Small Molecule API Market rewards suppliers who possess both complex chemistry and regulated-market compliance.

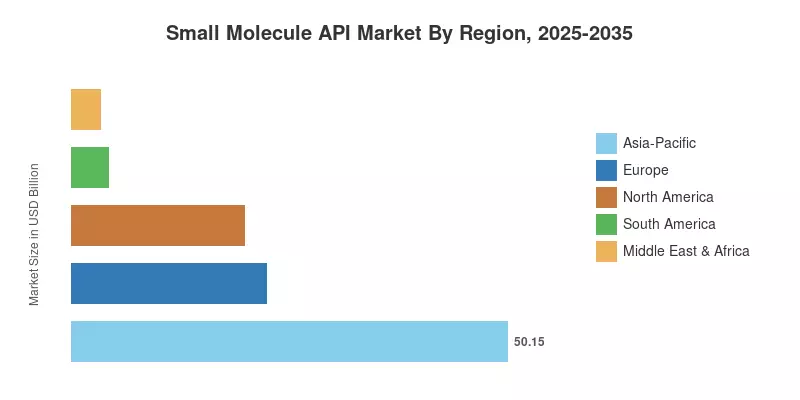
Asia-Pacific is the fastest-growing region in the Small Molecule API Market, with a compound annual growth rate (CAGR) of 7.96%. This is an unusual double lead. Europe maintains a 22.40% market share, which is attributed to the EU pharmaceutical strategy's commitment to the reshoring of critical medicines. The producers who maintain their market share through 2035 will be determined by supply security, not price alone.


Key Report Takeaways

• By Therapeutic Area

  • Oncology led the Small Molecule API Market with a 24.65% share in 2025, reflecting targeted therapy depth and earlier-line adoption.
  • Central nervous system and neurology substances are advancing at 7.41% CAGR through 2035 on the back of neurodegenerative pipelines.
  • Cardiovascular diseases contributed roughly USD 27.10 billion in 2025 volume anchored in long-duration therapy.

• By Region

  • Asia-Pacific holds a 50.15% share of the Small Molecule API Market, the largest regional position globally
  • North America is expected to reach USD 71.85 billion by 2030 as reshoring qualification work accelerates
  • Middle East & Africa is the smallest base but posts a 6.05% CAGR across the forecast window

Market Size and Forecast (2021–2035)

Market Research Future built this series from a bottom-up reconciliation of API export-import filings, DMF and CEP submission counts, audited segment revenue from 40 publicly listed manufacturers, and CDMO order-book disclosures. Historical years were validated against national customs data; forecast years apply therapy-area growth weights to the 2025 base.
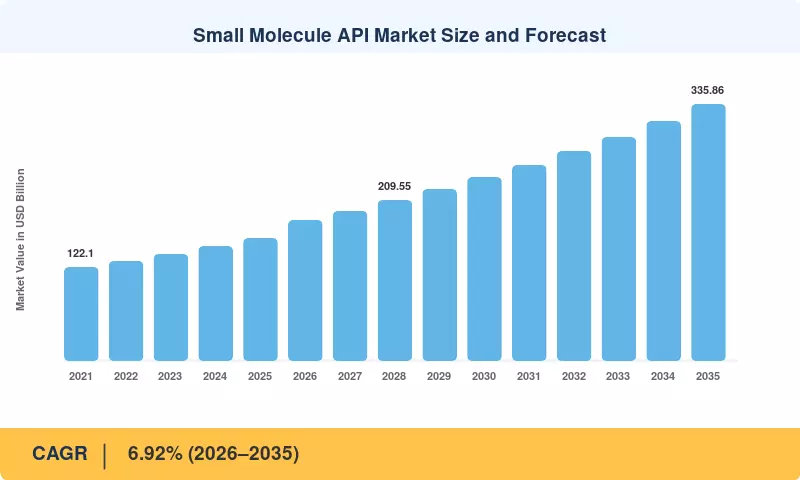
Small Molecule API Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Chronic disease and oncology burden ~1.6% Global Long-term (≥4 yr)
Loss of exclusivity and generic conversion ~1.3% North America, Europe Medium-term (2–4 yr)
CDMO outsourcing by biotech sponsors ~1.2% Global Medium-term (2–4 yr)
Government reshoring incentives ~0.9% US, EU, India Long-term (≥4 yr)
Continuous manufacturing adoption ~0.8% North America, Europe Long-term (≥4 yr)
Emerging-market access expansion ~0.7% Asia-Pacific, Africa Short-term (≤2 yr)
Complex generics and peptide chemistry ~0.6% Global Medium-term (2–4 yr)


Chronic Disease and Oncology Burden

Cancer incidence is the single largest demand pull. WHO recorded 20.6 million new cases on a 2024 base and projects nearly 35 million annually by 2050, a 70% increase that lands squarely on tightly controlled cytotoxic and kinase-inhibitor chemistry [1]. Diabetes adds a parallel load, with the International Diabetes Federation counting 589 million adults living with the condition in 2024 [2]. Both categories require sustained, multi-year API supply rather than episodic dosing.

Loss of Exclusivity and Generic Conversion

Patent expiries between 2025 and 2030 place an estimated USD 251 billion of branded revenue at risk across the innovator sector [5]. Each conversion multiplies API sourcing demand, because a single molecule that had one qualified supplier under exclusivity typically draws six to twelve filers post-expiry. Generic entrants file abbreviated applications that require validated drug master files, pulling qualification work forward by 18 to 24 months ahead of the expiry date.

CDMO Outsourcing by Biotech Sponsors

Sponsors without commercial infrastructure prefer variable cost to fixed asset ownership. Contract development and manufacturing revenue tied to chemical drug substance production has been expanding faster than the underlying market, with outsourced work projected at roughly 8.80% CAGR through 2035 [9]. Venture-funded oncology and CNS programs drive most of this, since a Phase II sponsor cannot justify a dedicated multipurpose plant. Dual sourcing rather than full insourcing remains the standard sponsor response.

Government Reshoring Incentives

India's Production Linked Incentive scheme for bulk drugs committed approximately USD 830 million toward 41 fermentation and synthesis projects targeting key starting materials [7]. The European Commission's Critical Medicines Act proposal, tabled in 2025, adds procurement preference for EU-manufactured substances. In the United States, the Defense Production Act Title III awards have funded domestic precursor capacity. These programs shift where capacity sits rather than how much total demand exists.

Continuous Manufacturing Adoption

FDA's Advanced Manufacturing Technologies designation, established under FDORA and operational from 2024, gives sponsors a formal review pathway for continuous-flow and process-intensified routes [4]. Facilities converting from batch report footprint reductions near 70% and solvent consumption cuts around 40%. That economics change matters most for high-volume cardiovascular and anti-infective substances where margin pressure is chronic, and capital efficiency determines whether a line stays commercially viable.

Emerging-Market Access Expansion

Middle-income health systems are widening formularies. The Global Fund and Unitaid procurement pipelines committed over USD 2.1 billion to antimicrobial and antiviral finished products in the 2023–2025 replenishment cycle, nearly all sourced from Indian and Chinese substance producers [10]. Domestic reimbursement expansion in Indonesia, Vietnam, and Brazil adds a second layer. Volume rather than price drives this contribution, so it lands early in the forecast window.

Complex Generics and Peptide Chemistry

Solid-phase and hybrid liquid-phase peptide synthesis has moved from niche to mainstream as incretin and oligonucleotide programs scale. Capital announcements for peptide-capable capacity exceeded USD 3.4 billion across 2024 and 2025 among the top ten contract manufacturers [11]. These substances carry three to five times the per-kilogram value of conventional chemistry, so even modest tonnage lifts reported value meaningfully within the Small Molecule API Market.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Nitrosamine and impurity control tightening ~-0.8% Global Medium-term (2–4 yr)
Key starting material concentration risk ~-0.7% Global Short-term (≤2 yr)
Price erosion in mature generics ~-0.6% North America, Europe Long-term (≥4 yr)
Environmental compliance and solvent cost ~-0.5% Asia-Pacific Medium-term (2–4 yr)
Regulatory inspection backlogs ~-0.4% Global Short-term (≤2 yr)


Nitrosamine and Impurity Control Tightening

Regulators have progressively lowered acceptable intake limits for nitrosamine drug substance-related impurities, with EMA and FDA requiring risk assessments across all chemically synthesized substances [12]. Remediation forces route redesign, fresh stability studies, and in some cases supplier replacement. Each affected molecule absorbs six to eighteen months of technical work and adds analytical cost that rarely passes through to tender pricing.

Key Starting Material Concentration Risk

A material share of advanced intermediates originates from a narrow geographic base. European Commission supply monitoring flagged single-source dependency in over 40% of surveyed critical medicine chains [13]. When one plant faces an environmental shutdown or logistics disruption, downstream substance production stops. Buyers respond with safety stock and dual qualification, both of which raise working capital without expanding underlying demand.

Price Erosion in Mature Generics

Competitive tendering in Germany, the Netherlands, and US group purchasing organizations has compressed prices on legacy molecules to levels where several producers have formally exited. Roughly 20% of surveyed European generic substances were reported as loss-making or marginal in 2024 [14]. Exit reduces reported value even as volume holds, which caps growth in the cardiovascular and anti-infective portions of the mix.

Environmental Compliance and Solvent Cost

Chinese provincial emission standards and India's Zero Liquid Discharge requirements have added meaningful capital cost per site. Effluent treatment and solvent recovery installations run USD 8–25 million for mid-size plants [15]. Producers unable to fund the upgrade consolidate or close. Solvent price volatility layers on top, since aromatic and chlorinated feedstocks track petrochemical cycles that manufacturers cannot hedge across multi-year supply agreements.

Regulatory Inspection Backlogs

Pandemic-era inspection deferrals left a queue that agencies are still clearing. FDA foreign facility inspections remained below pre-2020 volumes into 2024, delaying approvals for new sites and new substances [16]. A supplier waiting on pre-approval inspection cannot convert qualified capacity into revenue, so commissioned assets sit idle. The drag is temporary but concentrated in the early forecast years.

Small Molecule API Market Opportunities

Friend-Shored Regulated-Market Capacity

Buyers are paying a qualification premium for substances made in jurisdictions with predictable trade treatment. Producers adding capacity in the United States, Ireland, Singapore, and increasingly Mexico can command multi-year take-or-pay terms that traditional spot suppliers cannot. The commercial opening is narrow — it favors companies that already hold regulated-market inspection histories — but contract duration and margin both improve materially against the price-tendered baseline described in.

Peptide and Oligonucleotide Substance Capability

Advanced therapeutic programs require solid-phase synthesis methods that traditional chemical plants lack. With the global peptide and oligonucleotide CDMO market expanding from a baseline value of $7.805 billion toward nearly $39.19 billion by 2035 at a 15.8% compound annual growth rate, sponsors routinely reserve specialized manufacturing slots years prior to commercial product launch dates.


Emerging-Market Domestic Substance Manufacturing

Nations across Africa, Latin America, and the Middle East enforce local-content stipulations to address supply dependencies highlighted in World Health Organization assessments, where low- and middle-income regions historically import up to 70% to 80% of active pharmaceutical requirements. Strategic joint ventures pairing international chemical suppliers with local entities capture these growing regional public procurement preferences successfully.


Process Data and Quality Analytics as a Commercial Service

Continuous manufacturing systems generate vast parametric data streams. With the global continuous manufacturing market projected to expand from $3.28 billion toward $12.09 billion by 2035 at a 13.9% CAGR, contract manufacturers monetize these digital assets. Under frameworks tracked by the US FDA, firms bundle validated real-time quality release profiles into agreements, generating high-margin software-like recurring revenues separate from physical product tonnage.


Biocatalysis and Green Chemistry Route Redesign

Enzymatic synthesis protocols substitute heavy metal catalysts while reducing industrial solvent waste by up to 40%. Innovative green pathways establish proprietary intellectual property rights around mature molecules, granting established chemical producers defensible freedom-to-operate margins against aggressive generic commodity pressure.


Small Molecule API Market Future Outlook

Process Intensification and Continuous Flow

By 2035, Market Research Future expects a meaningful share of new commercial substance lines to be designed as continuous rather than batch. The economics are compelling where volume is stable: intensified processes cut plant footprint substantially and reduce solvent inventory, which lowers both capital and environmental compliance exposure. FDA's Advanced Manufacturing Technologies designation removes the regulatory uncertainty that previously discouraged conversion [4]. The constraint is capital availability among mid-tier producers, many of whom will license technology rather than develop it internally.

Machine Learning in Route Design and Impurity Prediction

Retrosynthesis planning tools and impurity prediction models are shortening route development from months to weeks for well-characterized chemistry. The practical payoff is not novelty but risk reduction — predicting nitrosamine formation potential before a route is committed avoids the remediation cycles described in. Adoption is concentrated among the largest contract manufacturers, which creates a widening capability gap. Expect this to influence sponsor supplier selection more than pricing does by the early 2030s.

Supply Chain Regionalization

Trade policy is reshaping where substances are made independently of cost. Tariff exposure, export licensing, and procurement preference rules are pushing multinationals toward multi-region qualification for their most critical molecules. This raises system-wide cost — duplicate qualification is not free — but buyers have decided the insurance is worth it. The result through 2035 is capacity growth that outpaces demand growth in some geographies while consolidation continues in others.

Sustainability Metrics as Procurement Criteria

Process mass intensity and solvent recovery rates are entering supplier scorecards alongside price and reliability. Large innovators have published Scope 3 reduction commitments that only work if substance suppliers change process design, since chemical synthesis dominates upstream emissions for most oral solid products. Producers with biocatalytic and green-chemistry portfolios will convert this into pricing power. Those without will find themselves excluded from preferred supplier lists before regulation ever requires it.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 50.15% share PLI-funded capacity, fermentation intermediates, export qualification
Europe 22.40% share Critical Medicines Act reshoring, continuous manufacturing conversion
North America 19.85% share Domestic precursor security, peptide capacity, CDMO expansion
South America 4.30% share Local content rules, regional generic hubs
Middle East & Africa 3.30% share Sovereign health funds, antimicrobial local production
Total 100.00%

Asia-Pacific dominates the Small Molecule API Market on installed capacity and cost position, while North America and Europe compete on regulated-market qualification depth rather than volume. The table below discloses one metric per region.


Asia-Pacific

Country Share of Region Key Driver
China 41.20% Intermediate and fermentation scale
India 33.60% PLI scheme and DMF filing depth
Japan 11.40% Domestic innovator substance supply
South Korea 6.80% Peptide and conjugate capability
ASEAN 4.50% Local content procurement
Rest of Asia-Pacific 2.50% Regional tender supply


Asia-Pacific's lead rests on integrated backward chains rather than labour cost alone. China supplies a large share of advanced intermediates that Indian and European finishing plants depend on, which is precisely the concentration risk flagged. India's Production Linked Incentive programme is designed to break that dependency, funding domestic penicillin G, clavulanic acid, and key starting material capacity that had migrated offshore two decades ago [7]. Japanese and Korean producers occupy a different position, focusing on high-specification substances for domestic innovators and export conjugate work rather than volume generics.

Europe

Country Share of Region Key Driver
Germany 24.10% Continuous manufacturing conversion
UK 14.30% Innovator substance development
France 13.50% Critical medicine reshoring grants
Italy 16.80% Contract substance manufacturing base
Spain 9.60% Fermentation and anti-infective capacity
Nordic Countries 8.20% Specialty and peptide chemistry
Russia 5.90% Domestic substitution policy
Rest of Europe 7.60% Regional supply and toll processing


Europe's position is policy-led. The Critical Medicines Act proposal introduces procurement criteria rewarding EU-located substance manufacture, a direct response to shortage episodes in antibiotics and analgesics [13]. Italy holds the largest contract manufacturing base on the continent, concentrated around Lombardy and Lazio, while Germany leads on process technology conversion. The structural constraint is cost: European sites cannot match Asian pricing on legacy molecules, so the realistic strategy is selective reshoring of shortage-prone substances rather than broad repatriation.

North America

Country Share of Region Key Driver
US 84.50% Innovator captive capacity and CDMO growth
Canada 9.20% Biosimilar and specialty substance work
Mexico 6.30% Nearshoring and regional generic supply


North American value concentrates in high-complexity substances tied to innovator pipelines. Pfizer's USD 465 million Kalamazoo commitment illustrates the pattern — internal capacity retained for molecules where supply certainty outweighs unit cost [3]. Federal interest in domestic precursor security has produced Defense Production Act awards and BARDA-funded capacity. However, total volumes remain modest against Asian output. Mexico is the emerging variable, drawing nearshoring investment that pairs USMCA treatment with cost structures Asian producers can still undercut but not by enough to offset logistics risk.

South America

Country Share of Region Key Driver
Brazil 62.40% ANVISA-aligned domestic production
Argentina 21.30% Public health procurement
Rest of South America 16.30% Regional distribution and packaging


Brazil anchors the region through a combination of BNDES industrial financing and preferential public procurement for locally produced substances under the Productive Development Partnership framework. Argentine producers supply the domestic public system and neighbouring markets but face persistent currency and import-licensing friction that complicates raw material sourcing. The regional pattern is import substitution at the finished-dose level first, with substance manufacturing following selectively for high-volume chronic care molecules where scale justifies local investment.

Middle East & Africa

Country Share of Region Key Driver
Saudi Arabia 31.50% Vision 2030 localization mandates
UAE 18.70% Free-zone manufacturing and re-export
South Africa 22.40% Antiretroviral and TB substance demand
Egypt 16.20% Regional generic export hub
Rest of MEA 11.20% Donor-funded procurement


Saudi Arabia's localization targets under Vision 2030 require a defined share of public pharmaceutical spend to route through domestic manufacturing, which has pulled in joint ventures with Indian and European partners. South Africa's demand profile is distinct, weighted toward antiretroviral and tuberculosis substances funded through Global Fund and PEPFAR channels [10]. Egypt has built genuine export capability, serving North African and Gulf tenders. Across the region, substance manufacturing remains early-stage relative to formulation, but sovereign capital is closing that gap faster than commercial economics alone would.

Small Molecule API Market By Region, 2025-2035

Small Molecule API Market Segmentation

By Therapeutic Area

Segment Metric Primary Demand Driver
Oncology 24.65% share Targeted therapy pipeline depth
Cardiovascular Diseases USD 27.10 Billion Long-duration chronic therapy
Central Nervous System and Neurology 7.41% CAGR Neurodegenerative and psychiatric pipelines
Infectious Diseases 12.30% share Antimicrobial tender volume
Metabolic Disorders USD 19.85 Billion Incretin and antidiabetic scale-up
Respiratory Disorders 5.82% CAGR Inhaled and oral maintenance therapy
Gastroenterology 6.20% share PPI and biologic-adjacent oral agents
Ophthalmology 4.15% share Ageing population and chronic eye disease
Dermatology 5.94% CAGR Topical and oral immunomodulators
Urology 3.40% share BPH and overactive bladder therapy
Other Therapeutic Areas 9.75% share Specialty and orphan indications


Oncology leads the Small Molecule API Market on both share and momentum, an unusual combination that reflects how deeply kinase inhibitors and cytotoxic payloads have moved into earlier treatment lines. Cardiovascular diseases and metabolic disorders supply the volume base, since patients stay on these therapies for decades and tonnage is predictable. Central nervous system and neurology posts the fastest growth outside oncology as neurodegenerative programs mature. Infectious diseases and respiratory disorders face the sharpest tender pricing, which caps their value contribution even where volume holds.

Competitive Benchmarking

The Small Molecule API Market is moderately concentrated. Market Research Future estimates a Herfindahl-Hirschman Index in the 400–600 range, with the top five suppliers holding a combined 26–32% of global value. That leaves a long tail of regional and single-molecule producers, particularly in India and China, where several thousand facilities hold at least one active drug master file. Concentration is rising in complex chemistry and falling in commodity categories where exits and consolidation run in parallel.

Company Est. Revenue Share Range Key Offerings for Small Molecule API Market Strategic Positioning
Lonza Group AG ~7–10% Complex chemistry, highly potent APIs, continuous flow Premium regulated-market CDMO with integrated development-to-commercial chains
Teva API (Teva Pharmaceutical Industries) ~6–9% Broad generic substance portfolio, peptides Scale generic supplier with deep DMF library across therapy areas
Dr. Reddy's Laboratories ~4–6% Cardiovascular, CNS, oncology substances Vertically integrated Indian producer with regulated-market inspection depth
Aurobindo Pharma ~4–6% Anti-infectives, cardiovascular, CNS Cost-competitive volume producer expanding into complex chemistry
Sun Pharmaceutical Industries ~3–5% Dermatology, ophthalmology, specialty substances Specialty-weighted portfolio with captive downstream demand
Divi's Laboratories ~3–5% Custom synthesis, generic APIs, nutraceutical intermediates Contract manufacturing specialist with strong innovator relationships
Siegfried Holding AG ~2–4% Controlled substances, sterile and non-sterile synthesis European multi-site CDMO with regulatory-heavy niche focus
Cambrex Corporation ~2–4% Early-phase development, small-volume commercial Development-stage entry point converting into commercial supply
Asymchem Laboratories ~2–4% Continuous flow, biocatalysis, oncology intermediates Technology-forward Chinese CDMO serving Western innovators
Piramal Pharma Solutions ~2–3% Highly potent APIs, antibody-drug conjugate payloads Cross-continental network positioned on potent handling capability
Hikma Pharmaceuticals ~1–3% Injectable and oral solid substances MENA-anchored producer with US and European regulated presence
WuXi STA (WuXi AppTec) ~3–5% Integrated CRDMO chemistry, peptide synthesis End-to-end discovery-through-commercial platform under trade policy scrutiny


Recent News & Developments

  • Pfizer CentreOne (October 2023): Committed USD 465 million to expand its Kalamazoo, Michigan facility, signalling that internal substance capacity remains strategically valuable for supply-critical molecules [3]
  • US FDA (September 2023): Launched the Advanced Manufacturing Technologies designation program under FDORA, creating a formal review pathway for continuous and process-intensified substance manufacturing [4]
  • Government of India (March 2024): Reported commissioning of multiple Production Linked Incentive projects covering penicillin G and key starting materials, reducing import dependency on fermentation-derived intermediates [7]
  • Lonza (July 2024): Acquired the Vacaville, California biologics site from Roche for USD 1.2 billion, part of a broader capacity strategy that also reallocated chemical synthesis assets toward complex substances [17]
  • European Commission (April 2025): Tabled the Critical Medicines Act proposal, introducing procurement preferences for EU-manufactured substances in shortage-prone categories [13]
  • Novo Nordisk (June 2024): Announced USD 4.1 billion in expanded fill-finish and precursor capacity in Clayton, North Carolina, tightening global peptide intermediate availability for third parties [11]
  • Dr. Reddy's Laboratories (February 2025): Expanded its Hyderabad substance capacity with a dedicated peptide block, targeting complex generic launches in the 2027–2030 window [18]
  • EMA (November 2024): Updated nitrosamine acceptable intake guidance, extending risk assessment obligations across additional chemically synthesized substance categories [12]

Small Molecule API Market Report Scope

Parameter Detail
Market Scope Global production and supply of chemically synthesized and semi-synthetic active pharmaceutical ingredients for human therapeutic use, covering in-house and outsourced manufacturing across all therapeutic areas
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.92% (2026–2035)
Market Size Checkpoints 2025: USD 160.24 Billion; 2026: USD 183.31 Billion; 2030: USD 239.56 Billion; 2035: USD 335.86 Billion
Fastest Growing Segments Central nervous system and neurology (7.41% CAGR); Asia-Pacific (7.96% CAGR)
Companies Profiled Lonza Group AG, Teva API, Dr. Reddy's Laboratories, Aurobindo Pharma, Sun Pharmaceutical Industries, Divi's Laboratories, Siegfried Holding AG, Cambrex Corporation, Asymchem Laboratories, Piramal Pharma Solutions, Hikma Pharmaceuticals, WuXi STA
Valuation Currency USD Billion

FAQs

What due diligence should a sponsor run before qualifying a new supplier in the Small Molecule API Market?
Review the supplier's inspection history across FDA, EMA, and PMDA, then verify key starting material sourcing two tiers upstream. Site audits should confirm impurity control capability, not just GMP compliance [16].
How do tariffs and export controls change sourcing strategy in the Small Molecule API Market?
Trade measures push buyers toward multi-region qualification for critical molecules, which raises total cost but reduces single-jurisdiction exposure. Contracts increasingly include tariff pass-through clauses and alternate-site provisions [13].
Is dual sourcing worth the added qualification cost?
For molecules with a single upstream intermediate source, yes — the qualification expense is small against a stockout. For commodity substances with many qualified filers, spot purchasing usually remains more economical [13].
What distinguishes a development-stage CDMO from a commercial supplier?
Development partners optimize for speed and route flexibility at small scale. Commercial suppliers optimize for validated repeatability and regulatory filing support. Few companies execute both well across the same asset base [9].
How does peptide chemistry differ commercially from conventional synthesis?
Per-kilogram values run three to five times higher, and capacity is reserved years ahead through take-or-pay agreements. Buyers negotiate on availability rather than price [11].
What signals a supplier at risk of exiting a molecule in the Small Molecule API Market?
Watch for deferred capital maintenance, narrowing DMF renewals, and repeated allocation notices. Producers typically signal exit through service degradation eighteen months before formal discontinuation [14].
Do sustainability metrics actually affect supplier selection today?
Increasingly yes among large innovators, where upstream chemistry dominates Scope 3 emissions. Process mass intensity now appears on scorecards alongside price, though it rarely overrides reliability [15].
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory guidance documents, pharmacopeial standards, chemical databases, and pharmaceutical manufacturing literature. Key sources included the International Council for Harmonisation (ICH) Quality Guidelines (Q7, Q8, Q9, Q11), US Food & Drug Administration (FDA) Drug Master File (DMF) database and Orange Book, European Medicines Agency (EMA) Active Substance Master File (ASMF) registry and Certificates of Suitability (CEP), World Health Organization (WHO) Prequalified Active Pharmaceutical Ingredients List, National Institutes of Health (NIH) PubChem Database and NCBI BioAssay archives, United States Pharmacopeia (USP) and European Pharmacopeia (Ph. Eur.) reference standards, Japanese Pharmacopeia (JP) and International Pharmacopeia (Ph. Int.), Active Pharmaceutical Ingredients Committee (APIC) guidance documents, European Fine Chemicals Group (EFCG) manufacturing reports, Pharmaceutical Research and Manufacturers of America (PhRMA) and International Federation of Pharmaceutical Manufacturers Associations (IFPMA) industry statistics, IQ Consortium technical reports, FDA Compliance Program Guidance Manual for Active Pharmaceutical Ingredients (7356.002F), European Directorate for the Quality of Medicines (EDQM) Certification database, national regulatory databases from China's NMPA, India's CDSCO, Japan's PMDA, and Brazil's ANVISA, peer-reviewed journals including Journal of Pharmaceutical Sciences, Organic Process Research & Development, Chemical Reviews, and Molecular Pharmaceutics, and commercial pharmaceutical databases including IQVIA MIDAS, Cortellis, and Evaluate Pharma. These sources were used to collect DMF filing statistics, ASMF/CEP certification data, manufacturing capacity metrics, regulatory inspection findings, therapeutic area production volumes, synthesis technology trends, and competitive landscape intelligence for synthetic APIs, high-potency APIs (HPAPIs), biologically sourced small molecules, and fermentation-derived APIs.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources comprised CEOs, Chief Scientific Officers (CSOs), VPs of Manufacturing and Operations, leaders of Process Chemistry, regulatory affairs directors, and commercial leaders from API manufacturing facilities, CDMOs/CMOs, and chemical intermediate suppliers. Demand-side sources comprised Chief Procurement Officers, Heads of API Sourcing and External Manufacturing, Quality Assurance directors, and supply chain leads from innovator pharmaceutical companies, generic drug manufacturers, biotechnology firms, and virtual pharma companies. Primary research has confirmed the timelines of complex small molecules and peptidomimetics in the product pipeline, validated market segmentation across captive and outsourced manufacturing models, and gathered insights on the adoption of process optimization (continuous flow chemistry, biocatalysis), CDMO partnership strategies, quality agreement structures, and API pricing dynamics that are influenced by regulatory compliance costs and capacity constraints.

Primary Respondent Breakdown:

By Designation: C-level Executives (32%), VP/Director Level (30%), Managers/Technical Leads/Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue triangulation and production volume analysis across the value chain. The methodology included:

Identification of 55+ key API manufacturers and CDMOs across North America, Europe, Asia-Pacific, and Latin America

Product mapping across branded/innovator APIs, generic/merchant APIs, high-potency APIs (HPAPIs), and sterile small-molecule injectables

Manufacturing mode analysis distinguishing captive/in-house production vs. outsourced/CDMO manufacturing

Analysis of reported and modeled annual revenues specific to API portfolios, including Type II DMF filings, ASMF registrations, and CEP certifications

Coverage of manufacturers representing 75-80% of global small molecule API market share in 2024

Extrapolation using bottom-up (API production volume × ASP by therapeutic area and geography) and top-down (manufacturer revenue validation, CDMO contract values, pharmaceutical R&D procurement data) approaches to derive segment-specific valuations for oncology APIs, cardiovascular/metabolic APIs, CNS APIs, anti-infective APIs, and emerging therapeutic areas

Cross-verification against WHO prequalified API volumes, national import/export pharmaceutical statistics, and pharmaceutical excipient ratio analysis to confirm API-to-formulation market sizing

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















