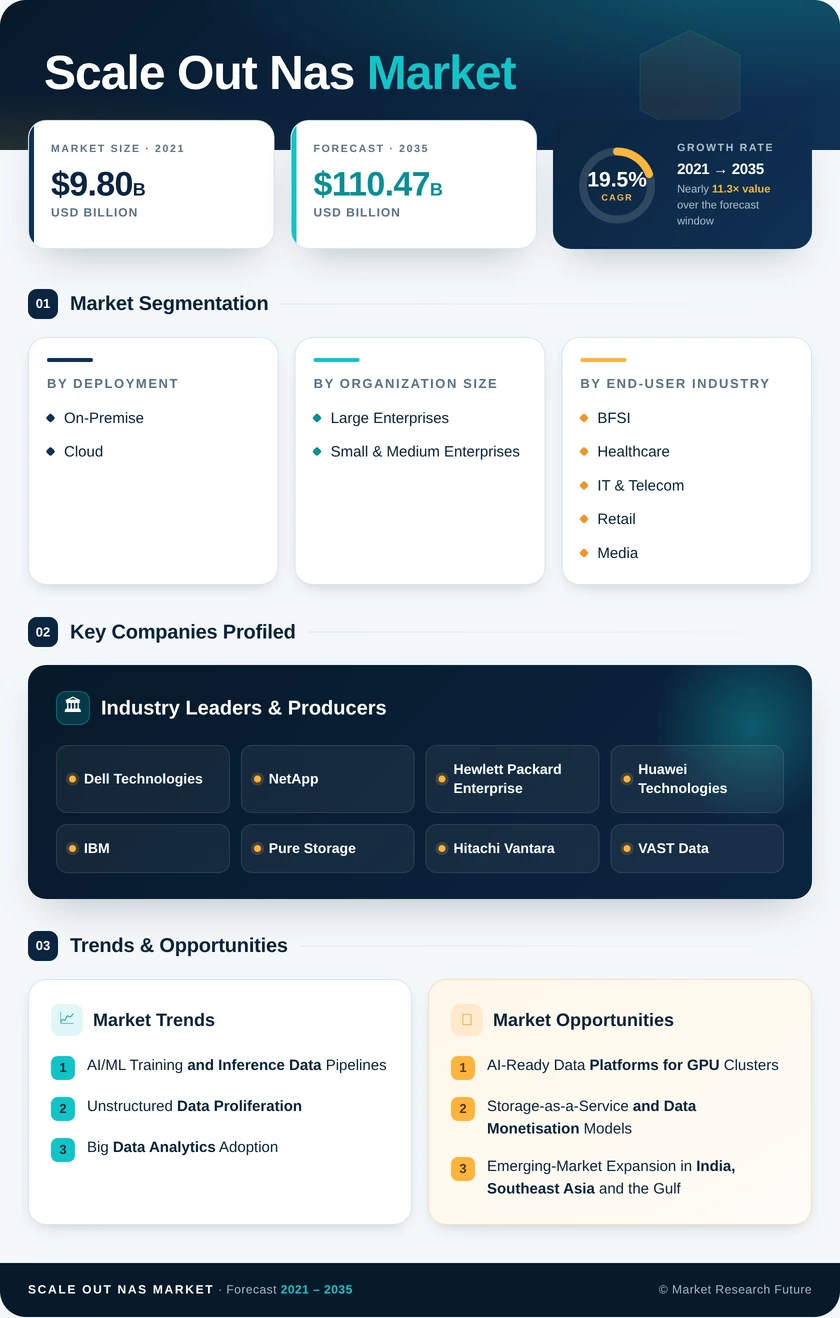
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Deployment | On-Premise; Cloud | On-Premise (58.5% share) | Cloud (24.3% CAGR) |
| By Organization Size | Large Enterprises; Small & Medium Enterprises | Large Enterprises (67.0% share) | Small & Medium Enterprises (22.8% CAGR) |
| By End-user Industry | BFSI; Healthcare; IT & Telecom; Retail; Media and Entertainment; Other End-user Industries | IT & Telecom (24.5% share) | Healthcare (23.6% CAGR) |
| By Region | North America; Europe; Asia-Pacific; Rest of the World | North America (38.5% share) | Asia-Pacific (23.1% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| On-Premise | GPU-adjacent all-flash clusters on RDMA fabrics for AI training |
| Cloud | Managed file services sold through hyperscaler marketplaces |
On-Premise leads with a 58.5% share because training clusters need storage on the same low-latency network as the GPUs, and regulated data often cannot leave customer facilities. Cloud grows fastest at a 24.3% CAGR as consumption-billed file services let teams burst analytics and recovery workloads without buying hardware. Most large buyers are converging on hybrid estates that span both models under one namespace.
| Sub-Segment | Key Trend |
|---|
| Large Enterprises | Multi-petabyte consolidation tied to AI infrastructure programmes |
| Small & Medium Enterprises | Entry-level node bundles and managed-service subscriptions |
Large Enterprises hold a 67.0% share, backed by multi-petabyte estates, in-house storage specialists and budgets sized for AI build-outs. Small & Medium Enterprises grow fastest at a 22.8% CAGR because few-node starter clusters and pay-as-you-grow subscriptions remove the upfront capital and staffing barriers. Managed service providers are becoming the main channel for reaching these smaller buyers.
| Sub-Segment | Key Trend |
|---|
| BFSI | Immutable snapshots and rapid recovery for DORA compliance |
| Healthcare | Genomics and digital pathology archives moving to shared file platforms |
| IT & Telecom | AI service delivery and 5G network analytics |
| Retail | Customer analytics and in-store video data retention |
| Media and Entertainment | 8K editing, rendering and visual-effects pipelines |
| Other End-user Industries | Manufacturing simulation and energy exploration datasets |
IT & Telecom leads with a 24.5% share as AI service providers and operators handling 5G network data need sustained parallel throughput. Healthcare grows fastest at a 23.6% CAGR, driven by genomics output heading toward exabyte scale and HIPAA-governed imaging archives. BFSI remains a major buyer, spending USD 3.74 Billion in 2025 on recovery-focused platforms, while Media and Entertainment depends on scale-out bandwidth for high-resolution production.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA