Probiotic Drinks Market (2026 - 2035)

Probiotic Drinks Market Size, Share, Industry Trend & Analysis Research Report By Product Type (Yogurt Drinks, Fermented Milk Drinks, Kombucha, Kefir, Probiotics Juices, Other Product Types), By Flavor (Flavored, Unflavored), By Packaging (Bottles, Cans, Tetra Packs, Others), By Distribution Channel (On-Trade, Off-Trade) – Forecast Till 2035
ID: MRFR/FnB/3566-HCR 128 Pages Snehal Singh Last Updated: September 17, 2026
Probiotic Drinks Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.74%
2025 Market SizeUSD 33.22 Million
2035 Market SizeUSD 76.40 Million
Key Players
Danone S.A.
Yakult Honsha Co., Ltd.
Nestlé S.A.
PepsiCo, Inc.
Meiji Holdings Co., Ltd.
Groupe Lactalis
Opportunities
  • Ambient Shelf-Stable Formats for Emerging Markets
  • Clinical-Grade Positioning Through the Pharmacy Channel
  • Microbiome Data Monetisation and Subscription Models

Probiotic Drinks Market Summary

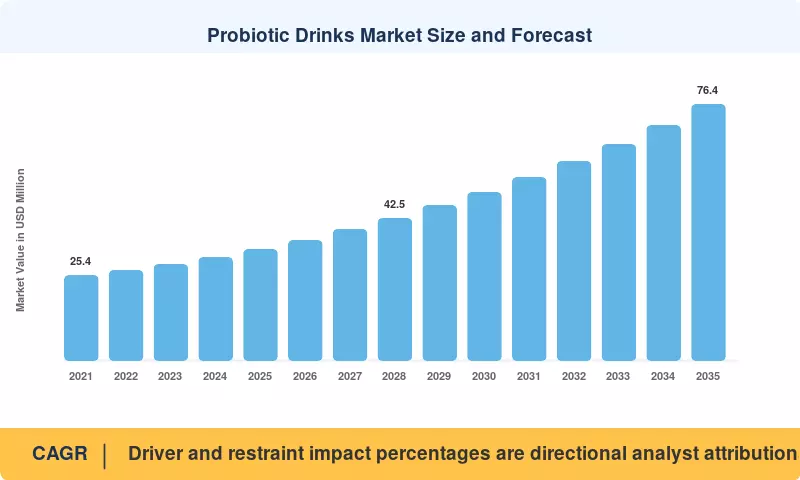
The Probiotic Drinks Market was valued at USD 33.22 Million in 2025 and is projected to open the forecast period at USD 35.94 Million in 2026 before reaching USD 76.40 Million by 2035, expanding at a CAGR of 8.74% between 2026 and 2035. Two catalysts anchor that trajectory. The first is the codification of strain-level evidence standards under the FAO/WHO probiotic framework, which pushed regulators in Japan, India, and Canada toward documented-strain approval pathways [1][11]. The second is capital: PepsiCo's USD 1.95 billion acquisition of Poppi in March 2025 repriced the entire fermented-beverage shelf and pulled strategic buyers into a category that venture money had dominated since 2020 [15].

Formulation science is displacing the older production model. Legacy batch fermentation with generic *Lactobacillus* blends and refrigerated-only distribution is giving way to microencapsulated, strain-identified cultures that survive acidic juice matrices and ambient logistics. Novonesis and Chr. Hansen legacy assets alone supply cultures into an estimated 60% of branded volume, and capital spending on precision fermentation capacity across Europe exceeded USD 700 million between 2023 and 2025 [8][19]. Cold-chain independence is the commercial prize.

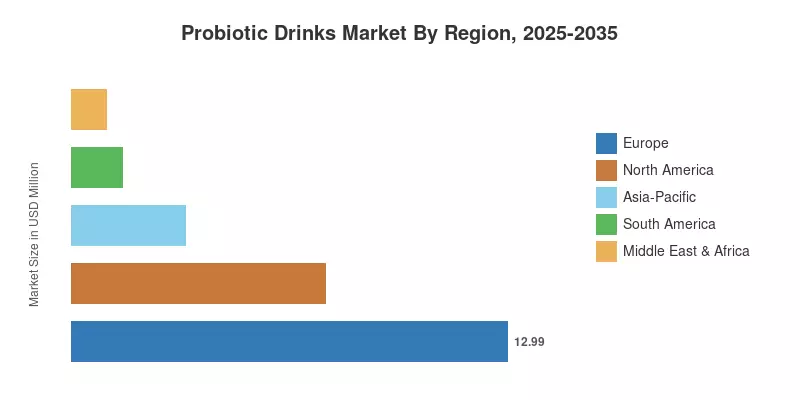
Regionally, Europe holds 39.1% of the Probiotic Drinks Market on the strength of entrenched daily-dose habits in France, Germany, and the Nordics. Asia-Pacific is the fastest-growing region at a 10.19% CAGR, propelled by modern-trade expansion in India and Indonesia. North America ranks second by value, where kefir and canned probiotic sodas are converting soft-drink occasions. Through 2035, competitive advantage in the Probiotic Drinks Market will accrue to firms that own clinically documented strains rather than flavour portfolios.

Key Report Takeaways

• By Product Type

  • Yogurt Drinks led the Probiotic Drinks Market with a 26.95% revenue share in 2025, sustained by decades of habitual consumption in France, Japan and South Korea
  • Probiotics Juices are forecast to post a 9.86% CAGR through 2035 as lactose-free and fruit-forward formats widen the buyer base

• By Flavor

  • Flavored variants accounted for 63.06% of the Probiotic Drinks Market in 2025, with fruit and botanical masking driving repeat purchase
  • Unflavored formats are advancing at a 9.54% CAGR on clean-label and culinary-use demand

• By Packaging

  • Bottles captured 46.51% share in 2025 across PET and glass formats
  • Cans are expanding at a 9.64% CAGR, supported by aluminium recycling rates above 70% in Europe and North America

• By Distribution Channel

  • Off-Trade channels held 78.5% share in 2025, with refrigerated grocery aisles carrying the bulk of volume
  • On-Trade outlets are growing at a 9.35% CAGR as cafés and juice bars add fermented pours

• By Region

  • Europe retained 39.1% share in 2025
  • Asia-Pacific is registering a 10.19% CAGR through 2035
  • North America generated USD 7.57 Million in 2025

Market Size and Forecast (2021–2035)

Estimates below combine bottom-up brand-level revenue reconstruction across 14 producing countries, customs data on cultured-dairy and fermented-beverage HS codes, retail scanner panels covering modern trade, and audited disclosures from listed producers. Historical values for 2021–2024 are actuals; 2025 is the base year; 2026–2035 are modelled forecasts. Currency effects are neutralised to constant 2025 US dollars.
Probiotic Drinks Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Microbiome science literacy and preventive nutrition spend 1.6 Global Medium-term (2–4 yr)
Modern-trade and cold-chain build-out in urban Asia 1.3 Asia-Pacific Medium-term (2–4 yr)
Strain-level regulatory clarity and claim pathways 1.1 Europe, Japan, India Long-term (≥4 yr)
Pharmacy and drug-store channel premiumisation 0.9 Europe, North America Short-term (≤2 yr)
Microencapsulation and ambient-stable technology 0.8 Global Long-term (≥4 yr)
Strategic M&A and category capital inflow 0.7 North America Short-term (≤2 yr)
Lactose-free and plant-based base extensions 0.5 North America, Asia-Pacific Medium-term (2–4 yr)


Microbiome Science Literacy and Preventive Nutrition Spend

The number of published trials including live cultures has increased significantly, and through 2025, the International Scientific Association for Probiotics and Prebiotics recorded over 1,400 registered human intervention studies [1]. Instead of advertising, clinicians recommended that evidence base to consumers. Between 2021 and 2024, household spending on preventive nutrition increased by 11% in all OECD economies [2]. The annual per-buyer value of gut health beverages has about doubled as a result of the change from sporadic to everyday purchases.


Modern-Trade and Cold-Chain Build-Out in Urban Asia

Between 2022 and 2025, Indonesia added over 3,000 modern-trade stores, while India's refrigerated retail floorspace grew at a rate of about 14% per year [16]. The binding constraint had been distribution rather than demand. Measurable improvements in both markets' World Bank logistics performance rankings reduced spoiling losses on chilled dairy shipments. In 2024, Yakult's daily delivery network in India surpassed 500,000 households, proving that direct models may grow in areas with limited retail cold chains [10].


Strain-Level Regulatory Clarity and Claim Pathways

Japan's Foods for Specified Health Uses framework and India's FSSAI probiotic strain list gave manufacturers defined routes to substantiated claims [11]. Approval costs are high — a FOSHU dossier typically exceeds USD 400,000 — but the resulting label protection is durable and blocks undifferentiated entrants. Health Canada's natural health product monographs achieved a similar effect at lower cost. Regulatory certainty raises willingness to invest in proprietary strains rather than commodity blends.

Pharmacy and Drug-Store Channel Premiumisation

Pharmacy listings reframe fermented beverages as adjuncts to antibiotic therapy and irritable-bowel management. European pharmacy chains reported average selling prices 34% above grocery equivalents for the same culture counts in 2024 [12]. Chain buyers demand clinical dossiers, which favours Danone, Yakult and Bio-K Plus over emerging brands. The channel remains small by volume but contributes disproportionately to category margin and to physician-mediated trial.

Microencapsulation and Ambient-Stable Technology

Encapsulation using alginate and protein matrices now sustains viable counts above 10⁸ CFU per serving through 90 days at ambient temperature in validated systems [19]. Cost per litre for encapsulated cultures fell roughly 22% between 2022 and 2025 as fermentation capacity expanded. Ambient stability removes the single largest barrier to distribution across South Asia, Africa and interior Latin America, where refrigerated retail penetration remains under 30%.

Strategic M&A and Category Capital Inflow

PepsiCo's USD 1.95 billion purchase of Poppi in March 2025 was the clearest signal that large beverage platforms view fermented functional drinks as a soft-drink replacement rather than a niche [15]. Disclosed category transaction value across 2023–2025 exceeded USD 3.4 billion. Acquisition activity lifts marketing spend, accelerates national distribution for acquired brands, and validates valuations for the remaining independent producers.

Lactose-Free and Plant-Based Base Extensions

Roughly 68% of the global adult population shows reduced lactase persistence, concentrated in East Asia, Africa, and Latin America [9]. Oat, coconut, and water-kefir bases open those populations without a dairy conversion. Lifeway's 2025 Probiotic Smoothie + Collagen line and multiple oat-base launches in the United Kingdom illustrate the direction. Plant bases also carry lower carbon intensity, aligning the Probiotic Drinks Market with retailer sustainability scorecards.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Cold-chain dependency and distribution cost -0.9 Asia-Pacific, MEA, South America Medium-term (2–4 yr)
Restrictive health-claim regulation in the EU -0.7 Europe Long-term (≥4 yr)
Sugar taxation and reformulation burden -0.6 Europe, Latin America Short-term (≤2 yr)
Private-label price compression -0.5 Europe, North America Short-term (≤2 yr)
Live-culture viability loss across shelf life -0.4 Global Medium-term (2–4 yr)


Cold-Chain Dependency and Distribution Cost

Compared to ambient beverages, refrigerated distribution increases landed costs per case by an estimated 19–24%, and spoiling in tropical markets can surpass 6% of transported volume [16]. For that reason, cold listings are usually rejected by retailers in secondary cities in Nigeria and India. Until ambient formats achieve commercial parity, the restriction prevents rural penetration and limits growth to metropolitan contemporary trade.


Restrictive Health-Claim Regulation in the EU

Nearly no probiotic-specific health claims have been allowed under Regulation (EC) No 1924/2006, and the phrase itself is still prohibited on packaging in a number of member states [7]. As a result, manufacturers promote tradition and taste more than benefits, which reduces price premiums. Mid-sized producers spend six figures a year on compliance reviews. Clinical funding is instead directed toward North America and Japan due to the asymmetry.


Sugar Taxation and Reformulation Burden

Sugar-sweetened beverage levies now operate in more than 100 jurisdictions, and flavoured fermented drinks frequently fall within scope [2]. Reformulating with stevia, monk fruit or allulose raises ingredient cost by 8–12% and can suppress culture activity during fermentation. Several European producers absorbed the levy rather than risk taste degradation, compressing gross margin by roughly two percentage points.

Private-Label Price Compression

European grocers now offer store-brand cultured drinks at 20–30% below branded equivalents with comparable declared CFU counts [4]. Because most shoppers cannot evaluate strain differences at shelf, price becomes the deciding variable. Branded share in German and UK chilled dairy has eroded steadily since 2022. Defending margin requires clinically documented strains that private-label suppliers cannot replicate cheaply.

Live-Culture Viability Loss Across Shelf Life

Declared counts at filling routinely overstate what reaches the consumer; independent testing has found end-of-life viability shortfalls above 40% in poorly managed chains [8]. Regulators in the United States and Canada have opened enquiries into label accuracy. Producers respond with overdosing at fill, which raises culture cost, or with stability investment. Either path erodes near-term profitability.

Probiotic Drinks Market Opportunities

Ambient Shelf-Stable Formats for Emerging Markets

Removing refrigeration from the value chain is the single largest addressable opportunity. Encapsulated and post-biotic formats already ship ambient in Tetra Pak formats across Indonesia and the Philippines, cutting distribution cost per case by roughly 18% [17]. That economics unlocks tier-two Indian cities, Nigeria, Egypt, and interior Brazil, where refrigerated retail is scarce. First movers who accept lower declared counts in exchange for reach can build habit before premium chilled entrants arrive.

Clinical-Grade Positioning Through the Pharmacy Channel

Pharmacies convert a beverage into a therapy adjunct. Chains across France, Germany and Canada now stock antibiotic-companion formats with documented strains, achieving repeat-purchase rates roughly double grocery equivalents [12]. Building this position requires published trials and pharmacist education rather than media spend, which favours patient capital. The channel also insulates brands from grocery price wars described in.

Microbiome Data Monetisation and Subscription Models

At-home microbiome sequencing has fallen below USD 90 per test, enabling brands to pair diagnostics with strain-matched beverage subscriptions [20]. Recurring revenue carries gross margins well above retail and generates longitudinal outcome data that strengthens future claim dossiers. Several European start-ups now bundle quarterly testing with monthly delivery. Data assets built this way become defensible entry barriers in the Probiotic Drinks Market.

Plant-Based and Water-Kefir Line Extensions

Dairy-free bases address lactose-intolerant populations and vegan buyers simultaneously. Oat and coconut kefir launched across UK and Australian grocery in 2024–2025, and water kefir is gaining shelf space in North American natural channels [9]. Ingredient costs remain 15–20% above dairy, but retail pricing supports the gap. Plant bases also lower Scope 3 emissions, easing compliance with retailer sustainability reporting.

Aluminium Packaging and Circular-Economy Alignment

Aluminium recycling exceeds 70% across Europe and North America, and cans protect cultures from ultraviolet degradation [7]. As single-use plastic restrictions tighten under the EU Packaging and Packaging Waste Regulation, canned formats convert a compliance cost into a marketing asset. The constraint is thermal processing: producers must validate that filling and seaming preserve viability.

Probiotic Drinks Market Future Outlook

Precision Fermentation and Strain Engineering

Production economics will shift as precision fermentation capacity expands. European and North American investment in the technology surpassed USD 700 million across 2023–2025, much of it convertible to culture production [19]. Engineered strains selected for acid tolerance and bile resistance allow formulators to place live organisms into juice and carbonated matrices that previously killed them within days. By 2030, strain IP rather than brand equity will determine which producers command premium pricing in the Probiotic Drinks Market.

Subscription Platforms and Direct Channel Economics

Retail margin structures cap profitability at roughly 30–35% gross for chilled beverages, whereas direct subscription models routinely clear 55% [20]. Yakult's delivery network demonstrated the model decades before digital commerce; app-based successors now replicate it at lower fixed cost. Expect hybrid architectures in which grocery drives trial and subscription captures the repeat buyer. The strategic value lies in consumption data that supports future clinical dossiers.

Packaging Regulation and Circularity Mandates

The EU Packaging and Packaging Waste Regulation sets binding recyclability and recycled-content targets through 2030, and comparable rules are advancing in Canada and several US states [7]. Aluminium's recycling rate above 70% gives cans a structural advantage over PET for compliance reporting. Glass retains a premium halo but carries freight penalties of 10–15%. Format choice is becoming a regulatory decision rather than a marketing one.

Convergence of Clinical Evidence and Consumer Claims

Regulatory divergence between the permissive Japanese and Canadian regimes and the restrictive European one is unsustainable for global brands. Codex Alimentarius work on probiotic definitions and ongoing EFSA reassessment point toward partial harmonisation later this decade [1][7]. Producers holding randomised controlled trial evidence will convert it into on-pack claims across multiple jurisdictions at once. That convergence is the most credible upside scenario for the Probiotic Drinks Market beyond 2030.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 7.57 Million Canned probiotic sodas, kefir expansion, clinical claims
Europe 39.1% share Private-label defence, pharmacy premiumisation, packaging compliance
Asia-Pacific 10.19% CAGR (2026–2035) Modern-trade rollout, direct delivery networks, ambient formats
South America USD 1.53 Million Dairy-cooperative partnerships, urban chilled retail
Middle East & Africa 3.1% share Halal certification, ambient distribution, Gulf premium retail
Total USD 33.22 Million —

Regional distribution in the Probiotic Drinks Market reflects consumption heritage more than income. Europe and Northeast Asia built daily-dose habits over four decades; South Asia and Africa are building them now against weaker cold chains.


North America

Country Metric Key Driver
US 78.4% of region Canned probiotic soda mainstreaming and club-channel listings
Canada USD 0.92 Million Natural health product monographs enabling on-pack claims
Mexico 9.71% CAGR Modern-trade expansion and traditional fermented-drink heritage


United States demand is being reshaped by soft-drink substitution rather than dairy growth. PepsiCo's Poppi acquisition and Lifeway's 2024 expansion into BJ's Wholesale Club, Publix, and Target moved fermented beverages out of specialty aisles into mainstream grocery [6][15]. Canada's regulatory environment is comparatively permissive: Health Canada monographs allow specified strain claims without individual dossiers, which is why Bio-K Plus scaled clinical positioning there first [13]. Mexico contributes the fastest national growth in the region, aided by familiarity with traditional cultured beverages.

Europe

Country Metric Key Driver
Germany 21.4% of region Discounter penetration and strong cultured-dairy tradition
UK USD 2.24 Million Plant-based kefir launches and pharmacy listings
France 19.6% of region Actimel heritage and daily-dose consumption habit
Italy 8.55% CAGR Pharmacy channel growth and functional-dairy reformulation
Spain USD 0.98 Million Modern retail chilled expansion
Nordic Countries 7.2% of region High per-capita fermented-dairy intake
Russia USD 0.71 Million Domestic kefir production base
Rest of Europe 8.32% CAGR Central European modern-trade catch-up


European volumes are stable, but value growth is constrained by Regulation (EC) No 1924/2006, which blocks most benefit messaging [7]. Producers compete on heritage, taste and format instead. Germany illustrates the resulting squeeze: discounter private label matches declared culture counts at materially lower prices, forcing Danone and Müller toward clinically documented strains and pharmacy distribution. The EU Packaging and Packaging Waste Regulation adds a second axis of competition, pushing recyclable-format investment ahead of the 2030 compliance deadlines.

Asia-Pacific

Country Metric Key Driver
China 32.8% of region Ambient lactic-acid beverage scale and e-commerce
India 11.42% CAGR Direct-delivery networks and modern-trade cold-chain build-out
Japan USD 2.32 Million FOSHU-certified daily-dose consumption
South Korea 10.6% of region Convenience-store distribution and functional-dairy culture
ASEAN 10.88% CAGR Ambient formats and rising urban disposable income
Rest of Asia-Pacific USD 0.81 Million Emerging chilled retail infrastructure


Asia-Pacific carries the highest structural growth in the Probiotic Drinks Market because habit formation and infrastructure investment are occurring simultaneously. Japan's FOSHU system, operating since 1991, remains the world's most developed functional-claim regime and sustains per-capita consumption far above Western levels [11]. India offers the sharpest contrast: Yakult's household delivery model surpassed 500,000 daily deliveries in 2024 by bypassing retail cold chains entirely [10]. ASEAN growth depends almost wholly on ambient-stable formats reaching cost parity.

South America

Country Metric Key Driver
Brazil 58.9% of region Dairy-cooperative distribution and urban chilled retail
Argentina USD 0.29 Million Established cultured-dairy consumption base
Rest of South America 8.96% CAGR Andean modern-trade expansion


Brazil anchors the region through cooperative dairy structures that already operate refrigerated routes into major cities, lowering incremental distribution cost for cultured beverages [18]. Currency volatility remains the principal commercial risk, since imported cultures are dollar-denominated while retail pricing is local. Argentina's consumption base is mature but constrained by inflation-driven trading down toward private label. Interior markets across the region remain effectively unserved pending ambient formats.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 29.4% of region Premium grocery expansion and Halal-certified dairy
UAE USD 0.24 Million Expatriate demand and modern retail density
South Africa 9.18% CAGR Formal retail penetration and functional-dairy interest
Egypt 13.2% of region Traditional fermented-dairy heritage and population scale
Rest of MEA USD 0.19 Million Nascent chilled distribution


Gulf markets behave as premium import destinations, where Halal certification and refrigerated hypermarket retail support pricing above European levels [14]. Saudi Vision 2030 food-security programmes have funded domestic dairy processing capacity, some of which is being converted to cultured formats. Sub-Saharan opportunity is larger by population but gated entirely on ambient technology; Nigeria and Kenya show meaningful traditional fermented-dairy consumption that branded producers have yet to capture at scale.

Probiotic Drinks Market By Region, 2025-2035

Probiotic Drinks Market Segmentation

By Product Type

Segment Metric Primary Demand Driver
Yogurt Drinks 26.95% share (2025) Habitual daily consumption in Europe and Northeast Asia
Fermented Milk Drinks USD 7.44 Million (2025) Ambient lactic-acid formats in China and Southeast Asia
Kombucha 9.42% CAGR (2026–2035) Sparkling functional soda substitution
Kefir USD 4.85 Million (2025) Multi-strain microbial diversity positioning
Probiotics Juices 9.86% CAGR (2026–2035) Lactose-free and fruit-forward flavour access
Other Product Types 6.60% share (2025) Water kefir, plant bases and shot formats


Yogurt Drinks lead the Probiotic Drinks Market on installed habit: Actimel, Yakult and their regional analogues occupy fixed refrigerated facings that new entrants cannot easily displace. Danone's 2024 Actimel+ Triple Action launch, adding vitamin D and zinc, shows how incumbents defend share through fortification rather than price [5]. Probiotics Juices grow fastest because they sidestep dairy entirely, though microencapsulation remains necessary to keep cultures viable in acidic matrices. Kefir is the swing category in North America.

By Flavor

Segment Metric Primary Demand Driver
Flavored 63.06% share (2025) Sensory masking of fermentation sourness drives trial
Unflavored 9.54% CAGR (2026–2035) Clean-label purity and culinary versatility


Flavored variants dominate the Probiotic Drinks Market because sourness is the primary barrier to first purchase; fruit essences, vanilla, and botanicals convert triers into repeat buyers. Lifeway's ten-strong 2024 Flavor Fusions range, including mango-turmeric and blueberry-lavender, targeted exactly that conversion [6]. Unflavored formats grow faster from a smaller base, appealing to ingredient-conscious European and North American buyers who use kefir in cooking. Sugar reformulation is the tension point between the two.

By Packaging

Segment Metric Primary Demand Driver
Bottles 46.51% share (2025) Established filling lines and product visibility
Cans 9.64% CAGR (2026–2035) Recyclability, UV protection, and on-the-go occasions
Tetra Packs USD 6.69 Million (2025) Ambient distribution across Asia-Pacific and MEA
Others 9.04% share (2025) Pouches, multi-serve jugs and shot vials


Bottles retain leadership because PET and glass lines are already amortised and shoppers associate transparency with freshness. Glass carries a premium image at a 10–15% freight and shelf-price penalty, while PET dominates mass-market yogurt drinks at sub-USD 0.10 packaging cost per unit. Cans grow fastest in the Probiotic Drinks Market, pulled by sparkling probiotic sodas and kombucha, though thermal processing during seaming can reduce viable counts unless carefully validated.

By Distribution Channel

Segment Metric Primary Demand Driver
Off-Trade 78.5% share (2025) Refrigerated grocery aisles and pharmacy wellness sets
On-Trade 9.35% CAGR (2026–2035) Cafés, juice bars and hospitality functional pours


Off-Trade carries the volume of the Probiotic Drinks Market, and within it, supermarkets and hypermarkets alone represent 51.90% of total category revenue through refrigerated-aisle placement beside yogurt and milk [6]. Pharmacies and drug stores are the fastest-moving sub-channel at roughly 8.76% CAGR, converting the product into a therapy adjunct at prices well above grocery. On-Trade grows quickly from a narrow base as foodservice operators add fermented pours to wellness menus.

Competitive Benchmarking

Concentration is moderate. The top five producers hold an estimated 38–44% of global revenue, and the calculated Herfindahl-Hirschman Index sits near 640 — comfortably within unconcentrated territory. Two structural forces keep it that way: regional dairy incumbents defend home markets that global brands cannot economically enter, and low technical barriers to basic fermentation allow craft kombucha and kefir producers to proliferate. Consolidation is nonetheless accelerating as beverage majors acquire growth brands outright.

Company Est. Revenue Share Range Key Offerings for Probiotic Drinks Market Strategic Positioning
Danone S.A. ~11–14% Actimel, Activia drinkable, DanActive Clinical-strain leadership and global chilled distribution
Yakult Honsha Co., Ltd. ~9–12% Yakult, Yakult 1000, Yakult Light Proprietary *L. casei* Shirota strain and direct delivery
Nestlé S.A. ~5–7% Nesvita, LC1, regional cultured lines Emerging-market reach and nutrition science platform
PepsiCo, Inc. ~4–6% Poppi, KeVita Soft-drink substitution and mainstream shelf conversion
Meiji Holdings Co., Ltd. ~4–6% Meiji Probio yogurt drinks, R-1 FOSHU-certified claims and Northeast Asian strength
Groupe Lactalis ~3–5% Parmalat cultured drinks, regional kefir Dairy asset scale and private-label supply capability
Lifeway Foods, Inc. ~3–5% Kefir, Flavor Fusions, Probiotic Smoothie + Collagen Kefir category leadership in North America
Arla Foods Amba ~2–4% Cultura, Arla kefir range Nordic heritage and cooperative supply integration
GT's Living Foods ~2–4% GT's Kombucha, Synergy Raw kombucha authenticity and natural-channel dominance
Suja Life, LLC ~1–3% Suja probiotic shots and juices Cold-pressed juice crossover and clean-label positioning
Health-Ade LLC ~1–3% Health-Ade Kombucha Premium craft positioning and flavour innovation
Kerry Group (Bio-K Plus) ~1–2% Bio-K+ drinkable probiotics Clinically documented strains for pharmacy channels


Recent News & Developments

  • PepsiCo (March 2025): Completed the USD 1.95 billion acquisition of Poppi, bringing a canned prebiotic-probiotic soda brand into a national distribution system and signalling mainstream soft-drink substitution [15]
  • Lifeway Foods (February 2025): Launched Probiotic Smoothie + Collagen, combining kefir cultures, fruit purées and collagen peptides to target dual gut and skin benefits in the US natural channel [6]
  • Danone (September 2024): Introduced Actimel+ Triple Action across European markets with added vitamin D and zinc, positioning fortification as the answer to private-label CFU parity [5]
  • Lifeway Foods (June 2024): Secured expanded listings at BJ's Wholesale Club, Publix, and Target, materially widening refrigerated facings for kefir in US mass retail [6]
  • FSSAI, India (November 2024): Published an updated list of permitted probiotic strains for food and beverage use, giving domestic manufacturers a defined compliance pathway for label claims [11]
  • Yakult Honsha (May 2024): Reported that its India direct-delivery network passed 500,000 daily household deliveries, validating cold-chain bypass models in emerging markets [10]
  • European Commission (January 2024): Advanced implementing measures under the Packaging and Packaging Waste Regulation, setting recyclability thresholds that affect PET and multilayer carton formats used in chilled beverages [7]
  • Novonesis (October 2023): Announced expanded fermentation capacity in Denmark and the US to serve rising demand for encapsulated, acid-tolerant cultures used in juice and carbonated formats [8]

Probiotic Drinks Market Report Scope

Parameter Detail
Market Scope Global market for ready-to-drink fermented and cultured beverages containing live or documented probiotic cultures, spanning dairy and non-dairy bases, sold through on-trade and off-trade channels
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.74% (2026–2035)
Market Size Checkpoints USD 33.22 Million (2025); USD 35.94 Million (2026); USD 54.64 Million (2031); USD 76.40 Million (2035)
Fastest Growing Segments Probiotics Juices (9.86% CAGR); Cans (9.64% CAGR); Unflavored (9.54% CAGR); On-Trade (9.35% CAGR); Asia-Pacific (10.19% CAGR)
Companies Profiled Danone, Yakult Honsha, Nestlé, PepsiCo, Meiji Holdings, Groupe Lactalis, Lifeway Foods, Arla Foods, GT's Living Foods, Suja Life, Health-Ade, Kerry Group (Bio-K Plus)
Valuation Currency USD Million, constant 2025 prices
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst attributions of relative influence. They are not additive components of the headline CAGR and should not be summed

FAQs

How should investors assess entry valuations in the Probiotic Drinks Market?
Strain ownership drives multiples more than volume. Brands controlling proprietary, clinically documented cultures have cleared roughly 4–6x forward revenue, while contract-manufactured labels trade materially lower [15].
What contract terms matter most when sourcing cultures from suppliers?
Lock guaranteed counts at end of shelf life rather than at fill. Require strain-level identification and stability data across the full distribution temperature band [8].
Which certifications carry the most weight for exporters in the Probiotic Drinks Market?
FSSC 22000 and Halal certification open the widest buyer base across Asia and the Gulf. Japanese FOSHU status commands premium placement but demands clinical dossiers costing above USD 400,000 [11][14].
How do private-label programmes reshape retailer negotiations?
Grocers use declared-CFU parity to press branded margins down by 20–30% [4]. The effective counter is clinically documented strains that store-brand suppliers cannot source cheaply.
What integration problems appear when adding cultures to existing beverage lines?
Shared filling equipment risks cross-contamination between cultures and requires dedicated clean-in-place cycles. Converters typically budget USD 2–4 million for aseptic retrofits before commercial runs [19].
Where is the Probiotic Drinks Market most exposed to litigation risk?
United States consumer class actions target count discrepancies and unsubstantiated immunity messaging. Regulators in Canada have opened parallel label-accuracy enquiries [13].
How does ambient shelf-stable technology change unit economics?
Removing refrigeration cuts distribution cost per case by roughly 18%, opening rural South Asian and African routes [17]. The trade-off is lower viable counts, which constrains premium pricing.
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of food safety regulatory databases, peer-reviewed nutrition and microbiology journals, clinical publications, and authoritative food and beverage industry organizations. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), US Department of Agriculture (USDA), Japan Ministry of Health Labour and Welfare (MHLW) for Foods for Specified Health Uses (FOSHU) regulations, International Probiotics Association (IPA), International Food Information Council (IFIC), National Institutes of Health (NIH) Office of Dietary Supplements, National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Global Health Observatory, Food and Agriculture Organization (FAO) of the United Nations CODEX Alimentarius, European Commission Directorate-General for Health and Food Safety (DG SANTE), Health Canada Natural and Non-prescription Health Products Directorate (NNHPD), Food Standards Australia New Zealand (FSANZ), MRFR, MRFR Global New Products Database (GNPD), and national food and beverage association reports from key markets including the International Dairy Foods Association (IDFA), European Dairy Association (EDA), and China Health Care Association. These sources were used to collect consumption statistics, regulatory approval data (including Qualified Health Claims and Nutrient Content Claims), clinical efficacy studies on probiotic strains (Lactobacillus, Bifidobacterium, Saccharomyces), microbiome research, demographic consumption trends, and competitive landscape analysis for dairy-based probiotic drinks, non-dairy/plant-based alternatives, kombucha, kefir, and fortified functional beverages.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. Executives from probiotic beverage companies, dairy conglomerates, functional drink startups, and contract manufacturing organizations (CMOs) were among the supply-side sources. They included VPs of fermentation technology and innovation, regulatory affairs managers, and global category presidents. Registered dietitians, gastroenterologists, beverage category buyers, distribution partners, and procurement managers from retail chains (supermarkets, convenience stores, e-commerce platforms) made up the demand-side sources. Consumer adoption patterns, premium pricing strategies, clean-label trends, and regulatory compliance dynamics across different geographies were uncovered through primary research, which also validated market segmentation across product types (dairy-based, plant-based/vegan, kombucha, water kefir), distribution channels (mass retail, specialty health stores, direct-to-consumer), and probiotic strain categories. The research also confirmed product development pipelines and fermentation technology timelines.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (40%), Director Level (25%), Others (35%)

• By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and consumption volume analysis. The methodology included:

• Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa, encompassing multinational dairy corporations, specialized probiotic beverage companies, kombucha brewers, and plant-based drink innovators

• Product mapping across dairy-based probiotic drinks (yogurt drinks, fermented milk), non-dairy alternatives (oat-based, almond-based, coconut-based probiotic beverages), kombucha, water kefir, and fortified functional juices

• Analysis of reported and modeled annual revenues specific to probiotic drink portfolios, including SKU-level pricing data and volume shipments

• Coverage of manufacturers representing 72-78% of global market share in 2024

• Extrapolation using bottom-up (consumption volume × Average Selling Price by country/region, adjusted for channel margins) and top-down (manufacturer revenue validation against trade association data) approaches to derive segment-specific valuations by product type, probiotic strain, packaging format, and distribution channel

Copy

• Triangulation of data points from import-export statistics (UN Comtrade, national customs data), retail audit data (MRFR, IRI), and company financial disclosures to reconcile market estimations

• Adjustment for regional variations in probiotic classification (supplements vs. foods) and associated regulatory pathways affecting market access and pricing structures

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















