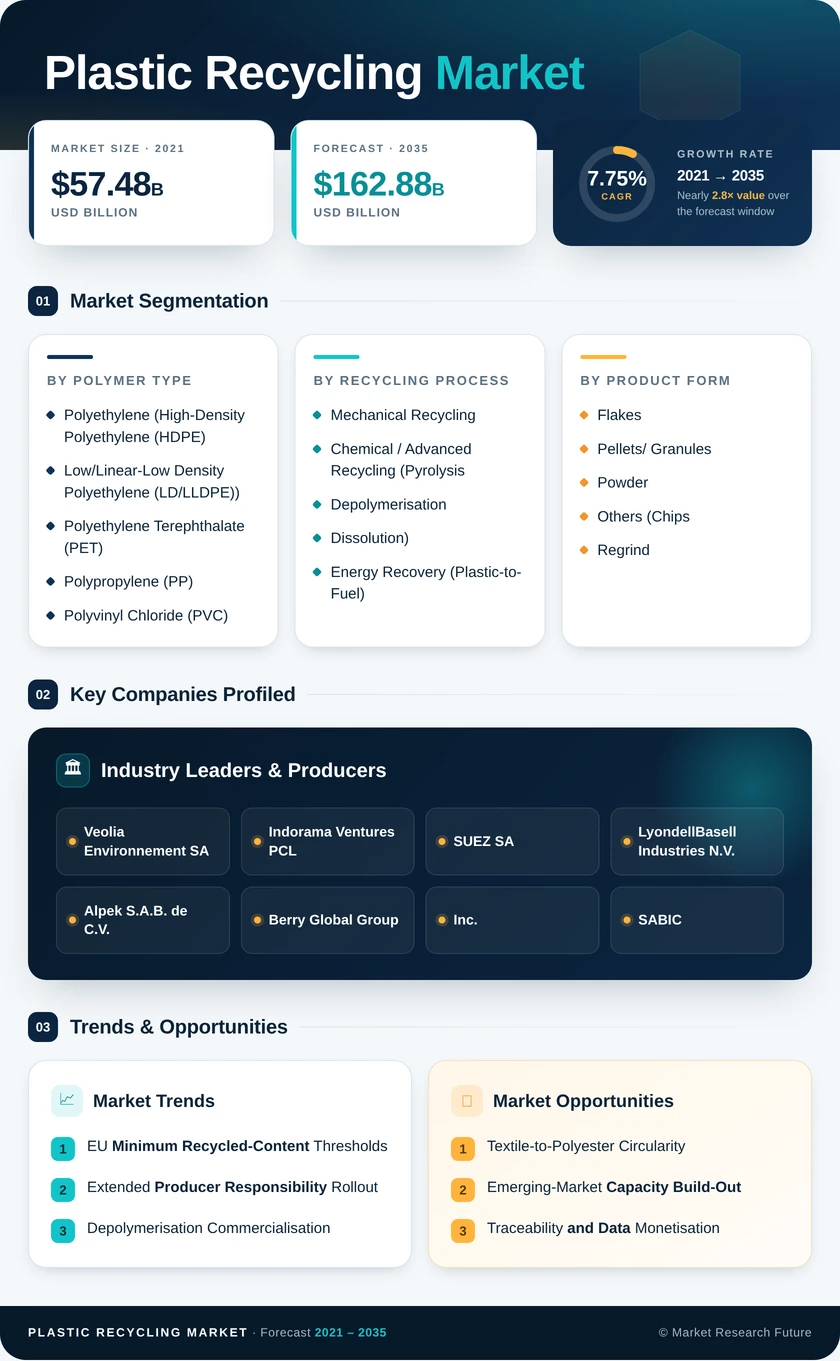
Market Segmentation Analysis
By Polymer Type
9.1.1 Polyethylene
9.1.2 Polyethylene Terephthalate (PET)
9.1.3 Polypropylene (PP)
9.1.4 Polyvinyl Chloride (PVC)
9.1.5 Polystyrene (PS)
9.1.6 Other Plastics (ABS, PC, PA, etc.)
By Recycling Process
9.2.1 Mechanical Recycling
9.2.2 Chemical / Advanced Recycling (Pyrolysis, Depolymerisation, Dissolution)
9.2.3 Energy Recovery (Plastic-to-Fuel)
9.2.4 Others (Biological - enzymatic/ microbial)
By-product Form
9.3.1 Flakes
9.3.2 Pellets/ Granules
9.3.3 Powder
9.3.4 Others (Chips, Regrind, Sheets, etc.)
By End-Use Application
9.4.1 Packaging
9.4.2 Building & Construction
9.4.3 Automotive
9.4.4 Electrical & Electronics
9.4.5 Textiles & Apparel
9.4.6 Consumer Products
9.4.7 Agriculture & Horticulture
9.4.8 Other Applications (General Manufacturing, Medical Devices, etc.)
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Polymer Type | Polyethylene (High-Density Polyethylene (HDPE), Low/Linear-Low Density Polyethylene (LD/LLDPE)); Polyethylene Terephthalate (PET); Polypropylene (PP); Polyvinyl Chloride (PVC); Polystyrene (PS); Other Plastics (ABS, PC, PA, etc.) | Polyethylene (31.2% share, 2025) | Other Plastics (ABS, PC, PA, etc.) (9.78% CAGR) |
| By Recycling Process | Mechanical Recycling; Chemical / Advanced Recycling (Pyrolysis, Depolymerisation, Dissolution); Energy Recovery (Plastic-to-Fuel); Others (Biological - enzymatic/ microbial) | Mechanical Recycling (75.8% share, 2025) | Chemical / Advanced Recycling (Pyrolysis, Depolymerisation, Dissolution) (9.32% CAGR) |
| By Product Form | Flakes; Pellets/ Granules; Powder; Others (Chips, Regrind, Sheets, etc.) | Flakes (71.1% share, 2025) | Pellets/ Granules (8.44% CAGR) |
| By End-Use Application | Packaging (Food-Grade, Non-Food Grade); Building & Construction; Automotive; Electrical & Electronics; Textiles & Apparel; Consumer Products; Agriculture & Horticulture; Other Applications (General Manufacturing, Medical Devices, etc.) | Packaging (41.5% share, 2025) | Automotive (10.94% CAGR) |
Market Segmentation Overview
By Polymer Type
| Sub-Segment | Key Trend |
| Polyethylene | Mature HDPE and LD/LLDPE reclamation infrastructure with headroom for higher throughput |
| Polyethylene Terephthalate (PET) | Food-grade bottle-to-bottle loops expanding under content mandates |
| Polypropylene (PP) | Purification routes unlocking food-contact and flexible packaging use |
| Polyvinyl Chloride (PVC) | Construction profile and pipe reuse constrained by additive legacy |
| Polystyrene (PS) | Niche recovery limited by collection density and low bale value |
| Other Plastics (ABS, PC, PA, etc.) | Engineering grades substituting virgin resin in vehicles and electronics. |
Polyethylene leads because both High-Density Polyethylene (HDPE) and Low/Linear-Low Density Polyethylene (LD/LLDPE) already move through established wash and extrusion lines with predictable bale economics. Other Plastics (ABS, PC, PA, etc.) grow fastest on a smaller base, pulled by automotive and electronics buyers who need structural and appearance-critical performance that commodity streams cannot deliver. Polyethylene Terephthalate (PET) sits between the two — large, regulated, and increasingly supply-constrained on food-grade quality rather than tonnage.
By Recycling Process
| Sub-Segment | Key Trend |
| Mechanical Recycling | Large installed base with utilisation limited by inbound bale quality |
| Chemical / Advanced Recycling (Pyrolysis, Depolymerisation, Dissolution) | Commercial plants commissioning against contracted offtake |
| Energy Recovery (Plastic-to-Fuel) | Defined role for genuinely non-recoverable residual fractions |
| Others (Biological - enzymatic/ microbial) | Enzymatic routes moving from pilot toward first commercial output |
Mechanical Recycling retains the dominant position because capital is sunk and unit costs are low wherever contamination stays within tolerance. Chemical / Advanced Recycling (Pyrolysis, Depolymerisation, Dissolution) grows fastest by processing what mechanical lines reject and by producing output that clears food-contact migration testing without separate decontamination validation. Energy Recovery (Plastic-to-Fuel) is not a competing growth story but a residual sink, and Others (Biological - enzymatic/ microbial) remains early-stage in commercial terms.
By Product Form
| Sub-Segment | Key Trend |
| Flakes | Lowest-cost intermediate for rigid container and thermoform conversion |
| Pellets/ Granules | Preferred where colour, melt index and odour tolerances are tight |
| Powder | Rotomoulding and compounding additive applications |
| Others (Chips, Regrind, Sheets, etc.) | Construction and general manufacturing with looser specification |
Flakes dominate on volume because bottle-to-bottle and thermoform converters can process them directly without an intermediate compounding step. Pellets/ Granules expand faster as converters running food-contact and automotive lines demand specification consistency that flakes cannot guarantee, and because advanced conversion routes yield pellets natively. Powder serves a defined rotomoulding niche, so the meaningful competition in this dimension is between flake cost and pellet reliability.
By End-Use Application
| Sub-Segment | Key Trend |
| Packaging | Content mandates and brand targets drive Food-Grade and Non-Food Grade demand. |
| Building & Construction | Steady baseload volume with minimal certification burden |
| Automotive | OEM qualification of interior and underbody components accelerating |
| Electrical & Electronics | Housing and enclosure substitution under producer obligations |
| Textiles & Apparel | Fibre-to-fibre and bottle-to-fibre routes scaling with collection schemes |
| Consumer Products | Durable goods and houseware substitution on brand commitments |
| Agriculture & Horticulture | Film, pot and irrigation component recovery in structured schemes |
| Other Applications (General Manufacturing, Medical Devices, etc.) | Industrial component substitution where specification permits |
Packaging leads because content thresholds apply directly to it, and demand splits between Food-Grade formats gated by migration testing and Non-Food Grade formats that adopted post-consumer material far earlier. Automotive grows fastest as end-of-life vehicle rules push OEMs to qualify polypropylene and HDPE in interior trim and underbody parts on multi-year validation cycles. Building & Construction absorbs the material both channels reject, providing the volume floor beneath the segment.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA