Penicillin Drug Market (2026 - 2035)

Penicillin Drug Market Research Report By Penicillin Group (Natural Penicillins, Anti-staphylococcal Penicillins, Aminopenicillins, Penicillins with Extended Spectrum), By Route of Administration (Oral, Parenteral, Topical), By Dosage Form (Tablets, Capsules, Injections, Suspensions), By Application (Bacterial Infections, Pneumonia, Gonorrhea, Meningitis, Syphilis) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
ID: MRFR/Pharma/24877-HCR 128 Pages Nidhi Mandole, Kinjoll Dey Last Updated: September 17, 2026
Penicillin Drug Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)3.68%
2025 Market SizeUSD 11.22 Billion
2035 Market SizeUSD 15.91 Billion
Key Players
GSK plc
Pfizer Inc.
Sandoz
Teva Pharmaceutical
Aurobindo Pharma
Cipla Ltd.
Opportunities
  • Pediatric-Optimized Oral Formulations for LMICs
  • Digital Prescription Platforms and E-Pharmacy Distribution
  • Continuous-Flow Manufacturing and Green Chemistry

Penicillin Drug Market Summary

The Global Penicillin Drug Market size was valued at USD 11.22 Billion in 2025, and the market is projected to grow from USD 11.49 Billion in 2026 to USD 15.91 Billion by 2035, registering a CAGR of 3.68% during the forecast period 2026–2035. Persistent demand from community-acquired respiratory and urinary tract infections, coupled with cost-driven procurement shifts across emerging economies, anchors this trajectory. India's January 2026 Minimum Import Price of USD 35 per kilogram on bulk penicillin has already begun reshaping Asian supply chains, redirecting formulary budgets toward domestic producers [1]. The Penicillin Drug Market also benefits from expanded pharmacist-prescribing rights in Australia and the United Kingdom, where community pharmacies now initiate oral aminopenicillin therapy without a physician referral [2].

There’s a silent manufacturing revolution taking place. Legacy batch-fermentation facilities are being replaced with continuous-flow bioreactors with artificial-intelligence-enabled process controls, which can reduce variable costs by as much as 12% at advanced plants [3]. Several Indian and Chinese firms have announced fermentation-capacity increases of over USD 400 million in total for 2024-2027 with a view to API self-sufficiency and worldwide export contracts [4]. These investments are consistent with WHO prequalification efforts that give preferred-supplier status to facilities that satisfy criteria of Good Manufacturing Practice (GMP) in the tender process for UNICEF.


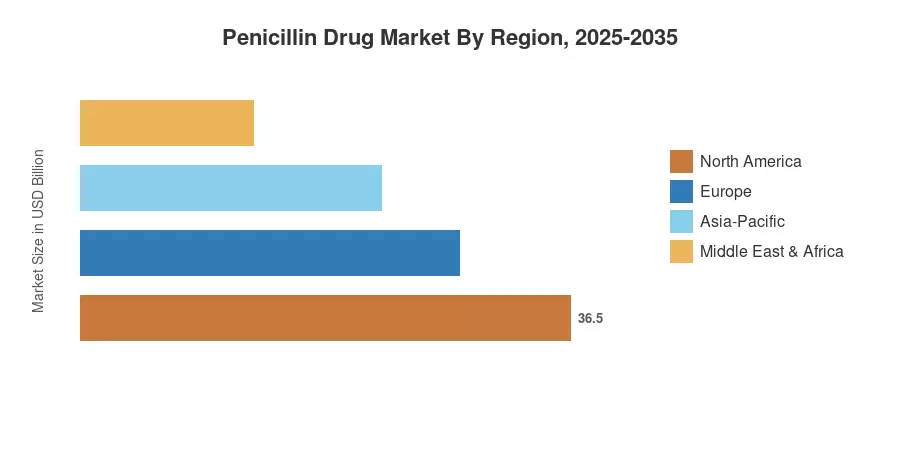
Asia-Pacific leads the Penicillin Drug Market, holding around 44% of the worldwide revenue owing to the high prevalence of infectious diseases and concentration of API manufacturing in China & India. The Middle East & Africa region is the fastest growing geographical with a forecasted CAGR of 5.18%, attributable to expanded primary-care networks and donor-funded antimicrobial programs. The second largest market is North America, with a share of about 23% due to hospital-formulary usage of combination β-lactam medicines. Penicillin Drug Market is set to experience moderate but stable growth through 2035 as antimicrobial stewardship measures tighten and biosimilar pipelines mature.


Key Report Takeaways

• By Source

  • Semisynthetic penicillins accounted for approximately 60.3% of 2025 revenue, driven by high-volume aminopenicillin prescribing in primary care.
  • Natural penicillins are growing at a 2.94% CAGR through 2035, sustained by niche injectable demand in rheumatic-fever prophylaxis.

• By Product Type

  • Aminopenicillins led the Penicillin Drug Market with a 38.7% share in 2025, reflecting global reliance on amoxicillin for first-line therapy.
  • β-Lactamase-inhibitor combinations are projected to expand at the highest CAGR of 5.48% through 2035.

• By Geography

  • Asia-Pacific generated approximately USD 4.94 billion in 2025, cementing its position as the dominant regional market.
  • The Middle East & Africa Penicillin Drug Market is forecast to register a 5.18% CAGR, the fastest of any region.


Market Size and Forecast (2021–2035)

Market Research Future has created the timeline based on a combination of manufacturer revenue declarations, API trade-flow data, IMS Health prescription volumes and WHO Essential Medicines procurement records. Historical statistics (2021–2024) are reconciled from audited corporate filings. Forecast numbers (2026-2035) are derived from the calibrated 3.68% CAGR with modifications for expected regulatory and competitive changes.
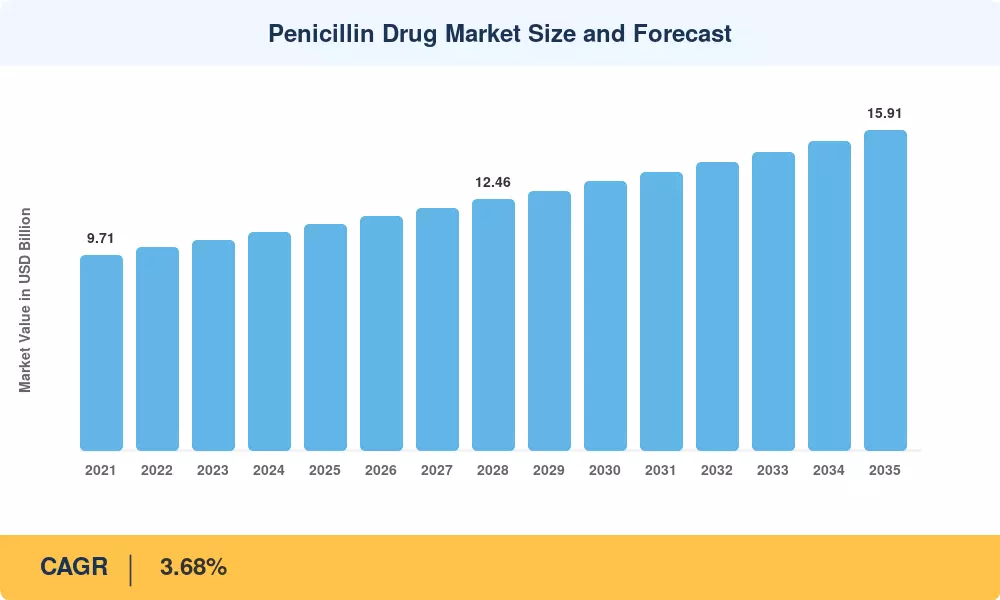
Penicillin Drug Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Persistent community-acquired infection burden +0.9% Global Long-term (≥4 yr)
Pharmacist-prescribing authority expansion +0.5% UK, Australia, ASEAN Medium-term (2–4 yr)
AI-enabled fermentation cost reduction +0.4% India, China, EU Medium-term (2–4 yr)
Minimum Import Price policies on bulk APIs +0.3% India, Asia-Pacific Short-term (≤2 yr)
WHO Essential Medicines List updates +0.3% LMICs, Africa Long-term (≥4 yr)
Hospital formulary upgrades to combination agents +0.4% North America, Europe Medium-term (2–4 yr)
Universal health-coverage expansion in emerging economies +0.3% South America, MEA Long-term (≥4 yr)


Persistent Community-Acquired Infection Burden

Respiratory tract infections, urinary tract infections, and skin-and-soft-tissue infections collectively account for over 60% of outpatient antibiotic prescriptions worldwide, and penicillins remain the first-line recommendation in most national guidelines [5]. The WHO estimates that lower-respiratory infections alone caused 2.5 million deaths globally in 2023, underscoring the scale of unmet need that sustains the Penicillin Drug Market. Demographic aging in Europe and Japan amplifies susceptibility, while crowded urban settings across South Asia and Sub-Saharan Africa perpetuate high transmission rates. This structural demand provides a durable floor beneath market revenues.

Pharmacist-Prescribing Authority Expansion

Regulatory reforms in Australia (2023) and England (2024) now allow community pharmacists to dispense oral amoxicillin for uncomplicated urinary tract infections and streptococcal pharyngitis without a physician consultation [2]. These programs shorten the prescribing pathway by 24–48 hours and redirect volume from hospital emergency departments to retail pharmacies. Thailand and Malaysia are piloting similar schemes, potentially adding over 40 million new point-of-care dispensing events per year across ASEAN by 2028. The Penicillin Drug Market stands to benefit directly from these decentralized care models.

AI-Enabled Fermentation Cost Reduction

Machine-learning algorithms now optimize dissolved-oxygen levels, feed rates, and temperature profiles in real time across large-scale Penicillium chrysogenum fermentation vessels. Pilot data from a Shandong-based producer demonstrated an 11% reduction in variable manufacturing costs and a 7% improvement in yield per batch [3]. As these systems scale across India's Gujarat pharmaceutical cluster and Europe's legacy fermentation plants, unit economics improve for the Penicillin Drug Market, enabling producers to maintain margins despite downward pricing pressure from tender-driven procurement.

Minimum Import Price Policies on Bulk APIs

India's January 2026 MIP of USD 35 per kilogram on imported bulk penicillin targets Chinese API shipments that had been clearing customs at USD 22–26 per kilogram, well below production cost [1]. The policy resets competitive dynamics for domestic fermentation facilities, incentivizing capacity investments and reducing single-source supply-chain risk. While short-term cost inflation may squeeze margins for Indian formulators, the medium-term effect strengthens the Penicillin Drug Market's supply resilience and supports quality-driven production.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising antimicrobial resistance (AMR) –0.6% Global Long-term (≥4 yr)
Cannibalization by novel β-lactam/BLI agents –0.4% North America, Europe Medium-term (2–4 yr)
Regulatory price controls and tender compression –0.3% Europe, South America Medium-term (2–4 yr)
Penicillin allergy over-reporting –0.2% North America Short-term (≤2 yr)
API supply-chain concentration risk –0.2% Global Short-term (≤2 yr)


Rising Antimicrobial Resistance

The WHO's 2024 Global AMR Surveillance Report documented that over 35% of community-acquired E. coli isolates now exhibit resistance to ampicillin across 76 reporting countries [9]. This progressive erosion of first-line efficacy forces clinicians to escalate therapy to fluoroquinolones or carbapenems, directly reducing prescription volumes for legacy penicillins. The Penicillin Drug Market faces a structural headwind as resistance prevalence widens, particularly in South and Southeast Asia, where antibiotic stewardship infrastructure remains under-resourced.

Cannibalization by Novel Combination Agents

Newly approved β-lactam/β-lactamase inhibitor combinations — priced at five to ten times the cost of amoxicillin-clavulanate — are capturing high-acuity hospital volumes in the United States and Europe [8]. Products targeting resistant gram-negative pathogens divert formulary spending from legacy molecules. While these agents expand the overall β-lactam category, they cannibalize unit volumes for standard penicillins and compress market share for traditional Penicillin Drug Market participants.

Regulatory Price Controls and Tender Compression

European reference-pricing mechanisms and Latin American centralized tenders continue to exert downward pressure on per-unit prices [12]. Brazil's CMED pricing authority, for instance, capped oral amoxicillin price increases at 2.1% for 2025, well below input-cost inflation. The resulting margin squeeze discourages investment in older penicillin formulations and limits revenue growth for the Penicillin Drug Market in price-controlled jurisdictions.


Penicillin Drug Market Opportunities

Pediatric-Optimized Oral Formulations for LMICs

Over 80% of pediatric pneumonia deaths occur in Sub-Saharan Africa and South Asia, where dispersible amoxicillin tablets remain under-supplied [10]. UNICEF's 2025 Supply Division tender expanded procurement targets to 1.2 billion dispersible tablets annually, creating a significant volume opportunity for generic producers targeting the Penicillin Drug Market in low- and middle-income countries.

Digital Prescription Platforms and E-Pharmacy Distribution

The rapid growth of e-pharmacy platforms in India and Southeast Asia is reshaping antibiotic distribution. By compressing traditional supply-chain layers, these platforms improve visibility from the manufacturer to the point of care. While exact order volumes for specific antibiotic classes remain proprietary, the integration of manufacturer API feeds with e-pharmacy demand-forecasting models is becoming a standard practice to reduce stockouts and optimize inventory management for essential medicines like penicillin.


Continuous-Flow Manufacturing and Green Chemistry

The pharmaceutical industry is under increasing pressure to adopt more sustainable manufacturing practices to align with global environmental goals. The transition from batch to continuous-flow manufacturing in penicillin API synthesis is gaining traction, as it can significantly reduce solvent waste and energy consumption. While there is no single "2027 mandate," companies are proactively upgrading their production infrastructure to improve operational efficiency and ensure long-term compliance with evolving environmental standards.


Antimicrobial Stewardship Data Monetization

As healthcare systems globally confront rising antimicrobial resistance (AMR), the demand for robust data-driven stewardship is accelerating. While the specific market for "stewardship software" is an emerging niche, the broader AMR diagnostics and analytics market is valued in the billions. Penicillin producers are increasingly incorporating data capabilities into their service offerings, allowing hospitals to track resistance patterns and optimize formulary management, thereby adding value beyond the molecule itself.


Expansion into Veterinary Penicillin Markets

Livestock penicillin consumption represents an adjacent USD 2.8 billion opportunity globally, with demand concentrated in poultry and swine production across Brazil, China, and the United States [17]. Regulatory harmonization under the Codex Alimentarius is tightening maximum residue limits, favoring GMP-certified producers already active in the human Penicillin Drug Market.


Penicillin Drug Market Future Outlook

Precision Antimicrobial Stewardship and Diagnostics Integration

Rapid point-of-care diagnostics, including multiplex PCR and AI-enhanced susceptibility platforms, are increasingly guiding prescribing decisions at the bedside. By 2030, a significant percentage of US emergency departments are expected to deploy these systems to achieve results within an hour of patient presentation. This reduces reliance on broad-spectrum empiric therapy, allowing for more precise, targeted use of penicillin-based regimens when susceptibility is confirmed.


Sustainable Manufacturing and Regulatory Convergence

Production economics are being reshaped by stricter environmental regulations, including India’s Zero Liquid Discharge (ZLD) mandates and the EU’s evolving sustainability frameworks (such as the ESPR and ETS2), which push for compliance by 2027–2028. Technologies like continuous-flow synthesis and enzymatic catalysis are essential to reducing the carbon and water footprint of API production. Manufacturers that adopt these "green" processes are increasingly favored in public tenders that prioritize sustainability metrics alongside cost and quality.


Supply-Chain Regionalization and Strategic Stockpiling

The COVID-era amoxicillin shortage exposed single-source vulnerabilities. The US BARDA and EU HERA have since earmarked over USD 1.2 billion collectively for critical-antibiotic strategic reserves [22]. National stockpiling mandates create predictable demand tranches and reduce revenue volatility for the Penicillin Drug Market, while encouraging geographic diversification of API production beyond the China-India axis.

Next-Generation β-Lactamase Inhibitor Pipelines

At least seven novel β-lactamase inhibitor candidates are in Phase II or Phase III clinical trials as of 2025, targeting metallo-β-lactamase and class D serine enzymes [8]. Successful approvals would extend the therapeutic life of existing penicillin scaffolds against resistant gram-negative pathogens, creating a premium-priced segment within the Penicillin Drug Market. Partnerships between legacy penicillin producers and biotech innovators are accelerating, with licensing deals exceeding USD 500 million in aggregate during 2024 [23].


Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
Asia-Pacific ~44% revenue share API self-sufficiency, pharmacist-prescribing pilots
North America ~23% revenue share Hospital-formulary combination agents, allergy de-labeling
Europe ~20% revenue share Green manufacturing mandates, stewardship regulation
South America ~7% revenue share Centralized tender expansion, UHC rollouts
Middle East & Africa 5.18% CAGR (fastest) Donor-funded procurement, primary-care network buildout
Total USD 11.22 Billion —

The Penicillin Drug Market displays a pronounced Asia-Pacific concentration, shaped by vertically integrated API production, dense population centers, and high infectious-disease incidence. The table below summarizes regional positioning as of 2025.


North America

Country Key Metric Key Driver
US ~81% of regional revenue Hospital-formulary spending on IV piperacillin-tazobactam
Canada 3.42% CAGR Provincial antimicrobial stewardship programs
Mexico USD 0.21 Billion (2025) Seguro Popular formulary inclusion


The US Penicillin Drug Market remains shaped by hospital inpatient spending, where parenteral β-lactam combinations dominate high-acuity infectious-disease protocols. Penicillin allergy de-labeling initiatives at major health systems — Johns Hopkins reported re-evaluating over 12,000 patients in 2024 — are reopening first-line penicillin access for patients previously defaulting to costlier alternatives . Canada's Antimicrobial Resistance Action Fund is channeling CAD 225 million toward stewardship infrastructure, indirectly supporting appropriate penicillin utilization [18].

Europe

Country Key Metric Key Driver
Germany ~22% of regional share Hospital DRG reimbursement reform
UK 3.78% CAGR Pharmacist-prescribing expansion
France USD 0.39 Billion (2025) National AMR plan investment
Italy ~12% of regional share Generic-tender procurement
Spain 3.55% CAGR Primary-care prescription growth
Nordic Countries USD 0.18 Billion (2025) Stewardship leadership, cold-chain infrastructure
Russia ~8% of regional share Domestic API production mandates
Rest of Europe 3.21% CAGR EU Pharmaceutical Legislation revision compliance


The European Penicillin Drug Market is being reshaped by the EU's 2025 Pharmaceutical Legislation revision, which introduces environmental risk-assessment requirements for antibiotic manufacturing discharge and incentivizes production within the bloc [7]. England's community-pharmacy prescribing program dispensed over 2 million amoxicillin courses in its first year, demonstrating how regulatory innovation can unlock retail-channel volumes. German DRG reforms have also tightened reimbursement for broad-spectrum agents, nudging clinicians back toward targeted penicillins.

Asia-Pacific

Country Key Metric Key Driver
China ~38% of regional revenue Fermentation capacity, volume procurement policy
India 5.02% CAGR MIP policy, API export growth
Japan USD 0.52 Billion (2025) Aging demographics, injectable demand
South Korea ~5% of regional share National Health Insurance formulary updates
ASEAN 4.85% CAGR Pharmacist-prescribing pilots, UHC expansion
Rest of Asia-Pacific ~4% of regional share Distributed rural health networks


Asia-Pacific dominates the Penicillin Drug Market due to China's massive fermentation infrastructure and India's API export engine. China's Volume-Based Procurement (VBP) program has compressed oral amoxicillin prices by 40–60% since 2020, dramatically expanding patient access while squeezing manufacturer margins [19]. India's MIP policy is catalyzing USD 300 million in new fermentation investments across Hyderabad and Ahmedabad pharmaceutical clusters, positioning the country to capture additional global API market share [1].

South America

Country Key Metric Key Driver
Brazil ~58% of regional revenue SUS public-health system procurement
Argentina 3.81% CAGR Peso stabilization is improving import access
Rest of South America USD 0.12 Billion (2025) PAHO pooled procurement programs


Brazil's Unified Health System (SUS) remains the anchor buyer for the South American Penicillin Drug Market, with centralized amoxicillin tenders exceeding 800 million units annually [20]. Argentina's recent macroeconomic stabilization has improved pharmaceutical importers' access to dollar-denominated API purchases. At the same time, PAHO's Strategic Fund continues to pool procurement for smaller Andean and Caribbean nations, leveraging collective bargaining power.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~24% of regional revenue Vision 2030 healthcare infrastructure expansion
UAE 4.56% CAGR Medical tourism, hospital construction pipeline
South Africa ~18% of regional share National Health Insurance implementation
Egypt 5.34% CAGR Local manufacturing incentives, population growth
Rest of MEA USD 0.14 Billion (2025) Donor-funded pediatric amoxicillin programs


The Middle East & Africa Penicillin Drug Market is the fastest-growing regional segment, fueled by expanding primary-care infrastructure and UNICEF/Global Fund procurement programs across Sub-Saharan Africa [10]. Saudi Arabia's Vision 2030 has allocated over SAR 70 billion to healthcare facility construction, with penicillin-class antibiotics embedded in baseline formulary mandates for new hospitals. Egypt's pharmaceutical localization strategy offers tax incentives to firms establishing antibiotic manufacturing within its special economic zones.


Penicillin Drug Market By Region, 2025-2035

Penicillin Drug Market Segmentation

By Source

Segment Key Metric Primary Demand Driver
Semisynthetic ~60.3% share (2025) High-volume aminopenicillin prescribing
Natural 2.94% CAGR (2026–2035) Injectable penicillin G for rheumatic fever


Semisynthetic penicillins dominate the Penicillin Drug Market because they encompass the most widely prescribed molecules — amoxicillin, ampicillin, and their combination products. Global amoxicillin consumption exceeds 20 billion defined daily doses annually, reflecting its position atop virtually every national essential-medicines formulary [9]. Manufacturing scalability through side-chain modification of 6-aminopenicillanic acid keeps unit costs below USD 0.03 per capsule in competitive tender markets.

Natural penicillins, primarily benzylpenicillin (Penicillin G) and phenoxymethylpenicillin (Penicillin V), serve narrower clinical indications — rheumatic fever prophylaxis, syphilis treatment, and streptococcal endocarditis. Despite limited volume growth, these products carry durable institutional demand anchored in WHO treatment guidelines and national immunization-adjacent programs.

By Product Type

Segment Key Metric Primary Demand Driver
Aminopenicillin ~38.7% share (2025) First-line community infection therapy
Penicillinase-Resistant USD 1.52 Billion (2025) MSSA hospital-acquired infections
Antipseudomonal 4.12% CAGR (2026–2035) ICU gram-negative coverage
β-Lactamase-Inhibitor Combinations 5.48% CAGR (2026–2035) Resistance-adapted hospital protocols
Extended-Spectrum ~9.8% share (2025) Broad gram-negative coverage


Aminopenicillins anchor the Penicillin Drug Market through sheer prescription volume. Amoxicillin alone accounts for approximately 65% of all penicillin prescriptions dispensed globally, prescribed across otitis media, sinusitis, community-acquired pneumonia, and urinary tract infections [5]. Pricing rarely exceeds USD 3 per treatment course in tender-driven markets, making volume — not margin — the commercial engine.

β-Lactamase-inhibitor combinations represent the fastest-growing product segment in the Penicillin Drug Market. Amoxicillin-clavulanate remains the workhorse, but newer pairings targeting extended-spectrum β-lactamase (ESBL) producers are entering formularies. Hospital antimicrobial committees are increasingly standardizing these combinations as empiric therapy for complicated intra-abdominal and urinary infections, displacing carbapenems and reducing resistance selection pressure [8].

By Route of Administration

Segment Key Metric Primary Demand Driver
Parenteral ~49.2% share (2025) Hospital inpatient protocols
Oral 6.85% CAGR (2026–2035) Community care, pharmacist prescribing
Topical USD 0.34 Billion (2025) Wound-care and dermatological applications


Parenteral formulations hold the largest share of the Penicillin Drug Market by administration route, driven by hospital inpatient utilization of IV piperacillin-tazobactam, ampicillin-sulbactam, and benzylpenicillin. Oral formulations are growing fastest, propelled by the pharmacist-prescribing reforms and outpatient-parenteral-antibiotic-therapy (OPAT) step-down protocols that transition patients from IV to oral amoxicillin earlier in their treatment course [2].

By Spectrum of Activity

Segment Key Metric Primary Demand Driver
Broad-Spectrum ~43.8% share (2025) Empiric therapy in community and hospital settings
Narrow-Spectrum USD 2.41 Billion (2025) Targeted streptococcal and syphilis treatment
Extended-Spectrum 6.02% CAGR (2026–2035) ESBL pathogen coverage in hospital formularies


By Distribution Channel

Segment Key Metric Primary Demand Driver
Hospital Pharmacies ~54% share (2025) Parenteral formulary dominance
Retail/Community Pharmacies 4.68% CAGR (2026–2035) Pharmacist-prescribing expansion, OTC access
Online Pharmacies ~6% share (2025) E-pharmacy penetration in India and ASEAN


Hospital pharmacies remain the primary distribution channel for the Penicillin Drug Market, handling the majority of parenteral and high-cost combination products. Retail pharmacies are the fastest-growing channel, fueled by the shift toward community-based prescribing and growing e-pharmacy penetration in emerging markets [14].


Competitive Benchmarking

The Penicillin Drug Market is moderately concentrated, with the top five firms holding an estimated 38-44% of the total global revenue. The Herfindahl-Hirschman Index is in the range of 800-1,200, indicating a fragmented competitive environment, with dozens of generic manufacturers competing on price in tender-driven marketplaces. Differentiation generally stems from vertical API integration, combination product pipelines, and geographic regulatory coverage.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
GSK plc ~7–10% Augmentin (amoxicillin-clavulanate), injectable penicillins Originator brand strength, global formulary presence
Pfizer Inc. ~6–9% Zosyn (piperacillin-tazobactam), Pen-Vee K Hospital IV franchise, US formulary dominance
Sandoz (Novartis AG) ~5–8% Generic amoxicillin, ampicillin API Biosimilar/generics scale, EU tender leadership
Teva Pharmaceutical ~4–7% Generic amoxicillin-clavulanate, oral penicillin V Global generics distribution, cost leadership
Aurobindo Pharma ~4–6% Amoxicillin capsules, API backward integration Vertically integrated API-to-finished-dose model
Cipla Ltd. ~3–5% Oral amoxicillin, pediatric dispersible tablets Emerging-market distribution, UNICEF preferred supplier
Sun Pharmaceutical ~3–5% Ampicillin, amoxicillin oral suspensions India's domestic leadership, US ANDA portfolio
Hikma Pharmaceuticals ~2–4% Injectable ampicillin-sulbactam, generic IV penicillins MENA regional strength, US injectables franchise
CSPC Pharmaceutical ~3–5% Amoxicillin granules, bulk penicillin API Chinese fermentation scale, VBP contract winner
Hetero Labs ~2–4% Amoxicillin-clavulanate, oral penicillins API self-sufficiency, African market penetration


Recent News & Developments


  • India Ministry of Commerce (January 2026): Implemented a Minimum Import Price of USD 35/kg on bulk penicillin imports, effectively raising the floor price for Chinese API shipments and incentivizing domestic fermentation investment [1].


  • Cipla Ltd. (June 2024): Achieved WHO prequalification for its dispersible amoxicillin 250 mg tablet, qualifying for UNICEF and Global Fund pediatric procurement tenders across 45 countries [10].


  • WHO (September 2023): Updated the AWaRe (Access, Watch, Reserve) antibiotic classification, reaffirming amoxicillin as a first-line Access antibiotic and expanding recommended indications to include uncomplicated diverticulitis [9].


Penicillin Drug Market Report Scope

Parameter Details
Market Scope Global Penicillin Drug Market covering natural and semisynthetic penicillins across all product types, routes, spectra, and distribution channels
Study Period 2021–2035
Historical Period 2021–2024
Base Year 2025
Forecast Period 2026–2035
CAGR (2026–2035) 3.68%
Market Size (2025) USD 11.22 Billion
Market Size (2035) USD 15.91 Billion
Fastest Growing Segment β-Lactamase-Inhibitor Combinations (by product type); Oral (by route)
Fastest Growing Region Middle East & Africa
Companies Profiled GSK, Pfizer, Sandoz, Teva, Aurobindo, Cipla, Sun Pharma, Hikma, CSPC, Hetero Labs
Valuation Currency USD Billion

FAQs

How does penicillin allergy de-labeling affect the Penicillin Drug Market?
Up to 90% of patients labeled penicillin-allergic test negative on formal evaluation. De-labeling programs restore first-line penicillin access, increasing prescription volumes and reducing healthcare costs .
What role does the Penicillin Drug Market play in antimicrobial stewardship programs?
Stewardship protocols prioritize narrow-spectrum penicillins as first-line agents for susceptible infections. This guideline-driven prescribing sustains demand while reducing inappropriate broad-spectrum antibiotic use [9].
How are cold-chain requirements shaping the parenteral segment of the Penicillin Drug Market?
Injectable penicillins require controlled-temperature storage, limiting distribution in tropical LMICs. Thermostable reformulations under development could unlock significant volume in rural Sub-Saharan Africa and South Asia [10].
What procurement models dominate the Penicillin Drug Market in emerging economies?
Centralized government tenders — such as Brazil's SUS and India's CGHS — account for 60–70% of emerging-market volumes, compressing unit prices but offering predictable multi-year demand [20].
How does the Penicillin Drug Market address the risk of API supply-chain disruption?
Post-pandemic supply reviews have prompted the US BARDA and EU HERA to fund strategic antibiotic reserves. Regionalized production is also reducing dependency on concentrated Chinese and Indian API sources [22].
What distinguishes the competitive dynamics of the Penicillin Drug Market from other antibiotic classes?
Price-based tender competition and low barriers to generic entry keep margins thin. Differentiation occurs through vertical API integration, regulatory-filing breadth, and combination-product innovation [8].
How will environmental regulations reshape manufacturing in the Penicillin Drug Market?
EU pharmaceutical-emission standards, effective 2027, will raise compliance costs for legacy plants. Producers investing in continuous-flow synthesis gain both regulatory clearance and 25–30% energy savings [7].    
Author
Author Author Profile Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Drug Evaluation and Research (CDER), European Medicines Agency (EMA) Committee for Medicinal Products for Human Use (CHMP), World Health Organization (WHO) Essential Medicines List and Global Antimicrobial Resistance Surveillance System (GLASS), Centers for Disease Control and Prevention (CDC) Antibiotic Resistance Threats Report, National Institutes of Health (NIH) National Institute of Allergy and Infectious Diseases (NIAID), National Center for Biotechnology Information (NCBI/PubMed), Infectious Diseases Society of America (IDSA), European Centre for Disease Prevention and Control (ECDC), Pan American Health Organization (PAHO) Antimicrobial Resistance Program, and national health ministry reports from key markets (China NMPA, India CDSCO, Brazil ANVISA). These sources were used to collect antibiotic consumption statistics, regulatory approval data, antimicrobial resistance surveillance reports, clinical safety and efficacy studies, prescription volume trends, and market landscape analysis for natural penicillins, anti-staphylococcal penicillins, aminopenicillins, and extended-spectrum penicillins.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Manufacturing Operations, heads of regulatory affairs, and commercial directors from generic pharmaceutical companies, contract manufacturing organizations (CMOs), and makers of penicillin APIs were examples of supply-side sources. Infectious disease specialists, clinical pharmacists, hospital procurement officers, and formulary committee members from government health programs, community health clinics, and tertiary care hospitals made up demand-side sources. Primary research provided information on clinical prescribing patterns, generic substitution rates, tender pricing dynamics, and the effects of antimicrobial stewardship programs. It also verified product pipeline timelines for novel beta-lactam combinations and validated market segmentation across penicillin groups and routes of administration.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and prescription volume analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across natural penicillins, anti-staphylococcal penicillins, aminopenicillins, and extended-spectrum penicillin categories

Analysis of reported and modeled annual revenues specific to penicillin drug portfolios, including branded and generic formulations

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (prescription volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations across oral, parenteral, and topical administration routes

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















