Passenger Ferries Market (2026 - 2035)

Passenger Ferries Market Research Report By Ferry Type (Ro-Pax, Passenger-Only Conventional, High-Speed Craft (Catamaran/Monohull), Hydrofoil & Hovercraft), By Propulsion Technology (Diesel & Diesel-Mechanical, Battery-Electric & Hybrid, LNG Dual-Fuel, Hydrogen & Methanol), By Application (Island & Remote Connectivity, Commuter & Public Transit, Tourism & Leisure), By Passenger Capacity Class (Below 100 Passengers, 100–400 Passengers, Above 400 Passengers) - Forecast to 2035
ID: MRFR/AT/20955-HCR
128 Pages
Shubham Munde, Garvit Vyas
Last Updated: September 04, 2026
Passenger Ferries Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.6%
2025 Market SizeUSD 17.8 Billion
2035 Market SizeUSD 30.7 Billion
Key Players
Damen Shipyards Group
Austal Limited
Fincantieri
Incat Tasmania
HD Hyundai Mipo
Cochin Shipyard
Opportunities
  • Route-Level Electrification Retrofits
  • Emerging-Market Archipelagic Connectivity
  • Data Monetisation and Mobility-as-a-Service

Passenger Ferries Market Summary

The Passenger Ferries Market reached USD 17.8 billion in 2025 and opens the forecast window at USD 18.8 billion in 2026, climbing to USD 30.7 billion by 2035 at a 5.6% CAGR. Two catalysts anchor that trajectory. Coastal cities from Kochi to Copenhagen have discovered that a waterborne corridor costs a fraction of an equivalent bridge or tunnel, and the International Maritime Organization's Net-Zero Framework, approved at MEPC 83 in April 2025, put a price signal on every litre of marine gasoil burned on a scheduled route [1][2].

Diesel mechanical drivelines that have propelled short-sea vessels for six decades are giving way to hybrid and full-battery architectures, LNG dual-fuel gensets, and early methanol conversions. Norway alone has commissioned more than 80 battery or plug-in hybrid ferries since 2015, and the European Union's FuelEU Maritime regulation, effective January 2025, requires a 2% cut in greenhouse gas intensity that tightens to 80% by 2050 [3][4]. Shipyards have responded by re-tooling around aluminium and lightweight steel hull forms.

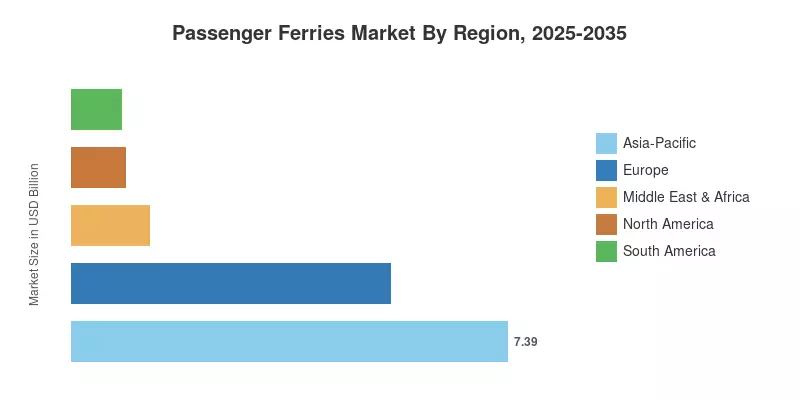
Asia-Pacific holds roughly 41.5% of the Passenger Ferries Market, built on archipelagic geographies in Indonesia, the Philippines and Japan. Middle East & Africa grows fastest at about 7.4% CAGR as Gulf tourism corridors and Red Sea developments commission new fleets. Europe ranks second, powered by Nordic zero-emission tender requirements that now make electrification a bid qualification rather than a bonus. The next decade belongs to operators who solve shore power before they order steel.


Key Report Takeaways

• By Propulsion Type

  • Diesel and diesel-mechanical propulsion still commands 68% of installed capacity across the Passenger Ferries Market, though its share erodes every tender cycle.
  • Battery-electric and plug-in hybrid systems post the strongest expansion at roughly 14.2% CAGR through 2035
  • LNG dual-fuel installations represent approximately USD 2.1 billion of 2025 vessel value, concentrated in Baltic and Mediterranean Ro-Pax fleets

• By Application

  • Inter-island and regional connectivity services account for about 38% of demand.
  • Urban commuter transit grows at close to 7.1% CAGR as municipal transit agencies fold waterborne links into integrated fare systems.
  • Tourism and leisure operations contribute roughly USD 5.0 billion in 2025

• By Region

  • Asia-Pacific anchors the Passenger Ferries Market with a 41.5% share
  • Middle East & Africa expands fastest at approximately 7.4% CAGR
  • Europe generates close to USD 5.4 billion in 2025 vessel and service value


Market Size and Forecast (2021–2035)

Figures below blend shipyard orderbook data, classification society fleet registers, operator capital expenditure disclosures, and national transport ministry procurement records, then reconcile them against delivered-tonnage counts to avoid double-counting options and letters of intent. Historical years are actuals; 2026 onward reflects contracted orderbook plus modelled replacement demand.

Passenger Ferries Market Size and Growth, 2021–2035
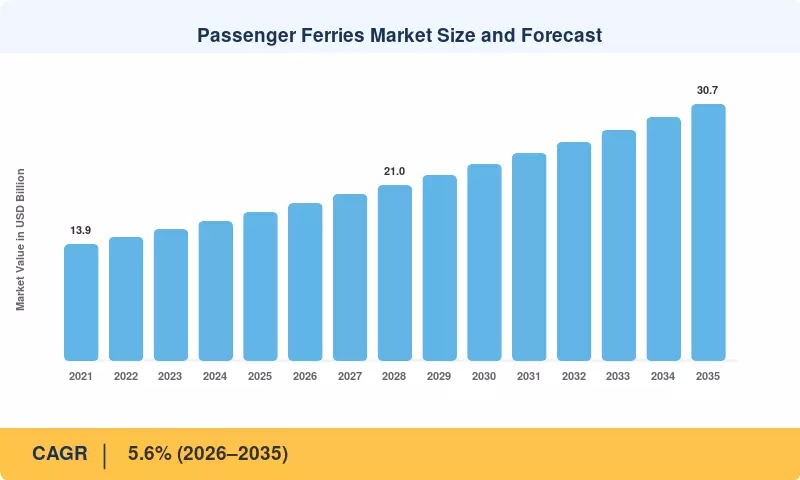
Passenger Ferries Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Coastal urbanisation and congestion relief programmes 1.3 Asia-Pacific, Europe Medium-term (2–4 yr)
IMO and regional decarbonisation mandates 1.1 Global Long-term (≥4 yr)
Battery cost decline and shore-charging build-out 0.9 Europe, North America Medium-term (2–4 yr)
Coastal and island tourism recovery 0.8 MEA, South America Short-term (≤2 yr)
Ageing fleet replacement cycle 0.7 Global Long-term (≥4 yr)
Public transit capital funding programmes 0.6 North America, Europe Short-term (≤2 yr)
Lightweight aluminium hull cost-performance gains 0.4 Asia-Pacific Medium-term (2–4 yr)


Congestion Relief Economics Favour Water

The same result is consistently reached by municipal transport planners: a waterborne corridor provides capacity at about a twentieth the capital cost of a comparable permanent crossing. With a project cost of around INR 1,137 crore, Kochi Water Metro was put into service in April 2023 and presently operates battery-electric boats on 15 routes that serve ten islands. In its first two years of operation, ridership exceeded 3 million [12]. In 2024, New York City Ferry carried over 6.5 million people on a network constructed at a quarter of the cost of subway extensions [10]. The blueprint is being copied by planners in Dhaka, Manila, and Lagos.


Regulation Now Sets the Specification

The focus of compliance has shifted from operating costs to design constraints. FuelEU Maritime's 2% reduction in greenhouse gas intensity starting in January 2025 will increase to 6% in 2030 and 14.5% in 2035. Additionally, ships that call at EU ports larger than 5,000 GT will be subject to pooling fines, which operators will incorporate into charter charges [4]. Combustion-only vessels are essentially prohibited from high-value tourism routes by the Norwegian Maritime Authority's zero-emission standards for World Heritage fjords, which go into effect in 2026 [13]. The fuel channel is now where specification writing starts.


Alternative Fuels Move From Pilot to Series

Battery systems dominate short routes, but longer crossings need chemical energy density. Norled's MF Hydra has operated as the world's first liquid-hydrogen-powered vessel since 2023, cutting roughly 95% of route CO₂ against its diesel baseline [14]. The economics of a hydrogen fuel cell passenger ferry still depend on subsidy — delivered green hydrogen above USD 6/kg keeps lifecycle cost roughly 40% above diesel equivalents — yet DNV's Alternative Fuels Insight register recorded steady growth in methanol and hydrogen-ready newbuild orders through 2025 [9].


Restraints Impact Analysis

Restraint weightings reflect analyst assessment of how strongly each constraint suppresses achievable growth in the Passenger Ferries Market. Values are directional drag estimates, not subtractable inputs to the headline CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Shipyard capacity constraints and long lead times −0.7 Europe, Asia-Pacific Medium-term (2–4 yr)
Shore power and charging infrastructure gaps −0.6 Global Medium-term (2–4 yr)
High capital intensity and operator financing limits −0.5 South America, MEA Long-term (≥4 yr)
Crew shortage and certification bottlenecks −0.4 Global Short-term (≤2 yr)
Alternative fuel availability and bunkering cost −0.3 Global Long-term (≥4 yr)


Yards Are the Bottleneck, Not Demand

Orderbook coverage of more than 30 months is reported by aluminum fast-craft manufacturers in Australia, Vietnam, and the United Arab Emirates; output is determined by the availability of specialized welders rather than steel or capital. Short-sea passenger vessel delivery slippage averaged four to seven months in 2024, according to data [15]. When yards slip, operators bidding on public contracts with set service-commencement dates absorb liquidated damages, which forces some agencies to choose life-extension refits over newbuilds.


The Charger Arrives After the Vessel

Grid work is frequently underestimated in electrification programs. In North America and parts of Southern Europe, utility connections for a 2-4 MW berth charger typically take 18 to 30 months, which is longer than the hull build time on smaller vessels [8]. Sequential delays are caused by substation renovations, quay-side transformer siting, and harbor authority approval. In order to completely avoid grid reinforcement, a number of European operators have added shoreside battery buffers at capital cost surcharges of roughly 15–20% of the charging package.


Passenger Ferries Market Opportunities

Route-Level Electrification Retrofits

The quickest way for operators to comply with 2030 intensity checkpoints is to retrofit existing hulls with hybrid drivelines, which usually cost 30–45% of newbuild expenditure and deliver within a year. Fleets constructed between 2005 and 2015 have enough hull life left to make the investment worthwhile.


Emerging-Market Archipelagic Connectivity

Thousands of underprivileged island pairs without access to roads are the focus of Indonesia's Tol Laut initiative and the expansion of the Philippine nautical highway. Multilateral lenders are increasingly bundling vessel purchases with terminal improvements through concessional financing, which reduces private operators' effective cost of capital by 200–300 basis points [16].


Data Monetisation and Mobility-as-a-Service

Ticketing platforms, occupancy telemetry and berth-slot data create a services layer worth capturing. Operators integrating into municipal MaaS apps report 8–14% ridership uplift from fare bundling, while anonymised movement data supports tourism board contracts and dynamic pricing engines.

Gulf and Red Sea Tourism Fleets

Saudi Arabia's Red Sea development, NEOM marine transit plans and UAE waterfront transit expansion have created a procurement corridor for premium low-emission craft with luxury interiors — a segment where European and Australian builders hold clear design advantage.

Standardised Modular Platforms

Series-built platforms with modular battery skids and interchangeable interiors cut unit cost 12–18% versus bespoke design. Yards offering configurable hull families win repeat municipal orders and lock in aftermarket revenue across the fleet lifecycle.


Passenger Ferries Market Future Outlook

Autonomy Reaches Commercial Waters

Crew cost represents 35–45% of operating expense on short routes, which makes automation commercially attractive well before it becomes technically routine. An autonomous ferry navigation system now typically operates in supervised mode, handling berthing and collision avoidance while a reduced bridge team retains authority. Norwegian and Japanese trials have demonstrated full docking cycles, and classification societies published provisional notation frameworks that let operators build toward reduced manning without losing certification [17].

The Electrification Supercycle

Battery pack prices fell below USD 100/kWh at cell level during 2024, and marine-certified system pricing follows with a two-to-three-year lag [8]. Once installed system cost approaches USD 400/kWh, routes under 40 minutes become cheaper to run electric than on diesel across most European and North American energy price bands. Fleet turnover then accelerates independently of subsidy.

Fuel Pathway Divergence

Long crossings will not electrify this decade. Methanol dual-fuel and hydrogen retain the advantage above roughly 90 minutes, and IRENA analysis projects green methanol production capacity scaling sharply after 2030, easing the bunkering constraint that currently caps adoption [19]. Operators are hedging by specifying fuel-flexible engine rooms with reserved space and weight for later conversion.

Disclosure Becomes a Procurement Filter

Corporate charterers, tourism boards and public authorities now request Scope 3 emissions data at tender stage. The EU Corporate Sustainability Reporting Directive pulled thousands of transport buyers into mandatory disclosure, and operators without per-passenger-kilometre emissions accounting lose access to contracts before price is discussed [20].


Passenger Ferries Market Segmentation

By Vessel Type

Vessel architecture defines cost structure across the Passenger Ferries Market, since hull form dictates propulsion options, speed envelope and berth requirements.

Segment Metric Primary Demand Driver
Ro-Pax 44% share Vehicle-carrying lifeline and Baltic routes
Passenger-Only Conventional USD 4.6 Billion Urban commuter and river transit
High-Speed Craft (Catamaran/Monohull) 6.8% CAGR Tourism and time-sensitive crossings
Hydrofoil and Hovercraft 8% share Niche high-speed island links


Ro-Pax vessels dominate by value because they carry the most steel, the most systems and the highest per-unit price, and because national lifeline route obligations in Greece, Italy, Japan and Indonesia guarantee replacement demand regardless of tourism cycles. High-speed aluminium craft grow faster in unit terms, driven by tourism operators competing on journey time and by Gulf procurement programmes willing to pay for premium interiors.

By Propulsion Technology

Propulsion choice has become the central procurement decision in the Passenger Ferries Market, reshaping supplier relationships across the value chain.

Segment Metric Primary Demand Driver
Diesel and Diesel-Mechanical 68% share Installed base and long-route economics
Battery-Electric and Hybrid 14.2% CAGR Short-route mandates and falling cell cost
LNG Dual-Fuel USD 2.1 Billion Baltic and Mediterranean Ro-Pax renewal
Hydrogen and Methanol 3% share Long-crossing decarbonisation pilots


Diesel's share falls every year without falling in absolute terms, because fleet growth in emerging archipelagic economies offsets European retirements. Battery-electric adoption concentrates where three conditions coincide — crossing under 45 minutes, reliable grid at both berths, and a public authority willing to underwrite the charging asset — which explains why Norway, Denmark and coastal India lead while Greece and Indonesia lag.

By Application

Application patterns determine service frequency and vessel utilisation within the Passenger Ferries Market.

Segment Metric Primary Demand Driver
Inter-Island and Regional Connectivity 38% share Lifeline obligations and archipelagic geography
Urban Commuter Transit 7.1% CAGR Congestion relief and MaaS integration
Tourism and Leisure USD 5.0 Billion Cruise-adjacent excursions and coastal travel


Connectivity services provide the demand floor. These routes run under public service obligation contracts with defined frequency, which insulates them from tourism volatility and makes them attractive to lenders. Commuter services grow fastest because municipal transit agencies have started treating water as a lane rather than a novelty, integrating ferry fares into unified transit cards in New York, Brisbane, Copenhagen and Kochi.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 41.5% share Archipelagic connectivity, urban water transit, aluminium fast craft
Europe USD 5.4 Billion Zero-emission tenders, Ro-Pax renewal, shore power
North America 5.1% CAGR Transit agency capital grants, hybrid conversions
South America 4.8% share Amazon river transit, coastal tourism
Middle East & Africa 7.4% CAGR Tourism fleets, Red Sea and Gulf marine transit
Total USD 17.8 Billion

Geography shapes the Passenger Ferries Market more directly than in almost any other transport equipment category, because demand follows coastline, archipelago structure and estuary form rather than GDP alone.


Asia-Pacific

Country Metric Key Driver
China 24% share of region Coastal city water transit and island tourism
Indonesia USD 1.3 Billion Tol Laut inter-island connectivity
Japan 6.4% CAGR Ageing fleet replacement, hybrid adoption
Philippines 11% share of region Nautical highway network expansion
India 9.8% CAGR Water metro and inland waterways programmes
South Korea USD 0.6 Billion Coastal route modernisation
Australia 7% share of region Harbour transit and tourism craft
Rest of Asia-Pacific USD 0.9 Billion Regional connectivity projects


Scale here comes from necessity. Indonesia operates thousands of routes across 17,000 islands, and its Ministry of Transportation has tied vessel subsidy eligibility to safety retrofits following repeated overloading incidents. India's Ministry of Ports, Shipping and Waterways has pushed electric vessel procurement through Cochin Shipyard, whose Kochi Water Metro boats are now referenced in tender documents from Varanasi to Guwahati [12].

Europe

Country Metric Key Driver
Norway 17% share of region Zero-emission fjord mandates
Greece USD 0.8 Billion Aegean island network renewal
Italy 12% share of region Mediterranean tourism and Sicily links
United Kingdom 5.4% CAGR Estuary transit and Scottish lifeline routes
Denmark USD 0.4 Billion Electric municipal ferry conversions
Germany 8% share of region Baltic Ro-Pax renewal
Rest of Europe 6.1% CAGR Cross-border short-sea services


Regulation drives everything on this continent. Norway's development contract model, which underwrote the world's first battery ferry in 2015, has been copied by Denmark, Sweden and Scotland, and Transport Scotland's small vessel replacement programme now specifies electric propulsion as default for routes under 45 minutes [13]. Greek operators face a harder equation, with long crossings and thin grid capacity at island ports slowing electrification.

North America

Country Metric Key Driver
United States 82% share of region Transit agency capital grants and hybrid conversions
Canada USD 0.42 Billion BC Ferries and Great Lakes fleet renewal
Mexico 6.9% CAGR Caribbean and Baja tourism routes


Public money dominates procurement. Washington State Ferries, operator of the largest US fleet, advanced its hybrid-electric conversion and newbuild programme with a five-vessel plan supported by state appropriation and Federal Transit Administration ferry grant funding [10]. Canada's approach runs through provincial operators, where BC Ferries has moved island-class hulls toward full-electric operation as terminal charging capacity comes online.

Middle East & Africa

Country Metric Key Driver
United Arab Emirates 31% share of region Dubai and Abu Dhabi marine transit expansion
Saudi Arabia 11.2% CAGR Red Sea tourism and NEOM marine mobility
Egypt USD 0.16 Billion Nile and Red Sea crossings
Rest of MEA 22% share of region West African coastal and lagoon transit


Ambition here outpaces installed base, which is precisely why growth rates lead the world. Roads Transport Authority marine services in Dubai have expanded abra and water bus fleets alongside premium routes, while Saudi Red Sea destinations have specified low-emission craft with high interior fit-out value. Lagos State ferry services in Nigeria represent a different opportunity — high latent demand constrained by jetty infrastructure and safety certification capacity.

South America

Country Metric Key Driver
Brazil 46% share of region Amazon river transit and Rio bay services
Argentina USD 0.19 Billion River Plate cross-border routes
Chile 6.7% CAGR Patagonian archipelago connectivity
Rest of South America 13% share of region Coastal tourism and lake services


River transport carries the continent. Amazonian communities depend on passenger vessels for basic mobility, and Brazilian federal safety regulation tightened after successive capsizing incidents, forcing hull and capacity certification upgrades that generate replacement demand. Argentina's cross-river services to Uruguay took a technology leap when Incat Tasmania launched Hull 096 for Buquebus in May 2025, the largest battery-electric vessel yet built [18].


Passenger Ferries Market By Region, 2025-2035

Competitive Benchmarking

Supply remains fragmented. The estimated HHI sits near 620, with the top five builders accounting for roughly 34–38% of delivered value, because vessel procurement is regional, specification-heavy and frequently tied to domestic content requirements. European yards dominate large Ro-Pax; Australian, Vietnamese and Emirati yards dominate aluminium fast craft; Asian yards compete aggressively on standardised commuter hulls.

Company Est. Revenue Share Range Key Offerings for Passenger Ferries Market Strategic Positioning
Damen Shipyards Group ~8–11% Standardised ferry platforms, electric road ferries Series-build modularity, global service network
Austal Limited ~7–10% Aluminium catamarans, trimarans, hybrid fast craft Fast-craft technology leadership
Fincantieri ~6–9% Large Ro-Pax, LNG dual-fuel vessels Premium newbuild and Mediterranean base
Incat Tasmania ~4–6% Large lightweight electric and diesel fast ferries Record-scale battery-electric builds
HD Hyundai Mipo ~4–6% Mid-size Ro-Pax and coastal passenger vessels Cost-competitive Asian capacity
Cochin Shipyard ~3–5% Electric water metro boats, hybrid ferries Public programme delivery in South Asia
Brødrene Aa ~2–4% Carbon-fibre electric passenger vessels Lightweight composite specialisation
Strategic Marine ~2–4% Fast crew and passenger craft Southeast Asian aluminium capacity
Wight Shipyard Co. ~1–3% High-speed commuter catamarans UK and European urban transit niche
Astilleros Armon ~1–3% Ro-Pax and regional passenger vessels Iberian and Atlantic route supply


Recent News & Developments

  • International Maritime Organization (April 2025): MEPC 83 approved the Net-Zero Framework combining a marine fuel intensity standard with an economic mechanism, giving operators their first global carbon price signal for scheduled services [1].
  • European Commission (January 2025): FuelEU Maritime entered application, requiring a 2% greenhouse gas intensity reduction and shifting compliance planning into vessel specification rather than bunker purchasing [4].
  • Incat Tasmania (May 2025): Launched Hull 096 for Buquebus, the largest battery-electric vessel built to date, carrying roughly 2,100 passengers on River Plate crossings and proving scale feasibility for electric propulsion [18].
  • Norled (2023–2024): MF Hydra completed its first full year of liquid-hydrogen operation in Norwegian waters, delivering commercial validation for fuel cell propulsion on medium-length routes [14].
  • Cochin Shipyard (April 2023 onward): Delivered successive tranches of battery-electric boats for Kochi Water Metro, establishing a domestic reference fleet that has since anchored further Indian urban waterway tenders [12].
  • Washington State Ferries (2024–2025): Advanced its hybrid-electric conversion and newbuild programme, combining state appropriation with federal ferry grant funding to renew the largest US passenger fleet [10].
  • Transport Scotland (2024): Progressed its small vessel replacement programme with electric-first specification for short lifeline crossings, reinforcing the Nordic tender model across the UK [13].
  • DNV (2025): Alternative Fuels Insight reporting showed continued growth in methanol and hydrogen-ready orders across short-sea passenger tonnage, alongside expanded battery installation counts [9].


Passenger Ferries Market Report Scope

Parameter Detail
Market Scope Design, construction, retrofit and lifecycle services for commercial passenger-carrying vessels on scheduled and tourism routes worldwide
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.6% (2026–2035)
Market Size Checkpoints USD 17.8 Billion (2025); USD 18.8 Billion (2026); USD 30.7 Billion (2035)
Fastest Growing Segments Battery-electric and hybrid propulsion; urban commuter transit application
Companies Profiled Damen Shipyards Group, Austal Limited, Fincantieri, Incat Tasmania, HD Hyundai Mipo, Cochin Shipyard, Brødrene Aa, Strategic Marine, Wight Shipyard Co., Astilleros Armon
Valuation Currency USD, constant 2025 prices

FAQs

How should buyers weigh newbuild versus retrofit when entering the Passenger Ferries Market?
Retrofits typically cost 30–45% of a newbuild and deliver in under twelve months, but hull age caps residual value. Newbuilds win when route electrification demands hull-form or weight-distribution changes. [Ref 9]
Which hull material suits short urban routes best?
Marine-grade aluminium dominates because it cuts displacement roughly 25% against steel, extending battery range on the same pack. Carbon composites go lighter still but raise repair cost and classification complexity. [Ref 11]
What contractual terms matter most in Passenger Ferries Market charter agreements?
Availability guarantees, battery capacity-fade warranties and shore-charger uptime clauses shape economics more than headline day rates. Negotiate fade thresholds at 80% retained capacity with defined remediation obligations. [Ref 15]
How do insurers view battery-electric vessels?
Underwriters price thermal-runaway exposure separately, often adding 8–15% to hull premiums until three years of claims history exist. Class-approved battery rooms with fixed suppression narrow that gap materially. [Ref 17]
What integration challenge surprises first-time electric operators?
Grid connection, not the vessel, is usually the critical path — utility interconnection can run 18 to 30 months. Secure the berth power agreement before ordering the hull. [Ref 8]
Where are emerging use cases in the Passenger Ferries Market beyond commuting?
Operators increasingly sell hold space for time-sensitive parcels and medical logistics on island routes, adding 6–12% to route revenue without extra sailings. Regulators generally treat this as ancillary cargo under existing passenger certificates. [Ref 5]
How should procurement teams evaluate shipyard delivery risk?
Check orderbook coverage beyond 24 months, specialist welder headcount, and prior slippage on comparable hulls. Yards running above 90% capacity utilisation miss contractual delivery dates most often. [Ref 15]    
Author
Author
Author Profile
Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author
Co-Author Profile
Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of maritime regulatory databases, peer-reviewed naval architecture journals, industry publications, and authoritative transportation organizations. Key sources included the International Maritime Organization (IMO), European Maritime Safety Agency (EMSA), United States Coast Guard (USCG), Bureau Veritas, Lloyd's Register, American Bureau of Shipping (ABS), International Association of Marine Insurers (IUMI), Interferry (the global trade association for the ferry industry), International Council of Cruise Lines (ICCL), World Maritime University, United Nations Conference on Trade and Development (UNCTAD) Review of Maritime Transport, Organisation for Economic Co-operation and Development (OECD) Transport Statistics, Eurostat Maritime Transport Statistics, Bureau of Transportation Statistics (BTS), National Oceanic and Atmospheric Administration (NOAA), Maritime and Port Authority of Singapore (MPA), Transport Canada, Australian Maritime Safety Authority (AMSA), and national maritime administration reports from key markets. These sources were used to collect vessel registration statistics, regulatory compliance data, safety incident reports, fleet capacity metrics, environmental emission standards, port infrastructure investments, and competitive landscape analysis for monohull, catamaran, SWATH, and hydrofoil ferry technologies across diesel-electric, gas turbine, and hybrid-electric propulsion systems.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Fleet Operations, Chief Naval Architects, heads of regulatory compliance, and commercial directors from shipyards, ferry operators, and maritime OEMs were examples of supply-side sources. Port authority directors, marine transport planners, executives from tourism boards, defense procurement officials, and fleet managers from military maritime commands, commercial operators, and public ferry services were examples of demand-side sources. Primary study acquired information on fuel transition plans, route optimization patterns, and subsidy frameworks, validated market segmentation across hull structures and propulsion systems, and confirmed newbuild delivery timetables.

Primary Respondent Breakdown:

By Designation: C-level Primaries (42%), Director Level (25%), Others (33%)

By Region: North America (28%), Europe (32%), Asia-Pacific (25%), Rest of World (15%)


Market Size Estimation

Global market valuation was derived through fleet value analysis and passenger volume modeling. The methodology included:

Identification of 60+ key ferry operators and shipbuilders across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Vessel mapping across monohull, catamaran, SWATH, and hydrofoil hull structures

Technology assessment across diesel-electric, gas turbine, and hybrid-electric propulsion systems

Analysis of reported and modeled annual revenues specific to passenger ferry operations and newbuild contracts

Coverage of operators and builders representing 75-80% of global fleet capacity in 2024

Extrapolation using bottom-up (passenger volume × fare revenue by route) and top-down (operator revenue validation) approaches to derive segment-specific valuations across capacity ranges (sub-100, 100-300, 300-500, and 500+ passengers) and fuel types (diesel, LNG, Z-drive, azimuth thruster)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.