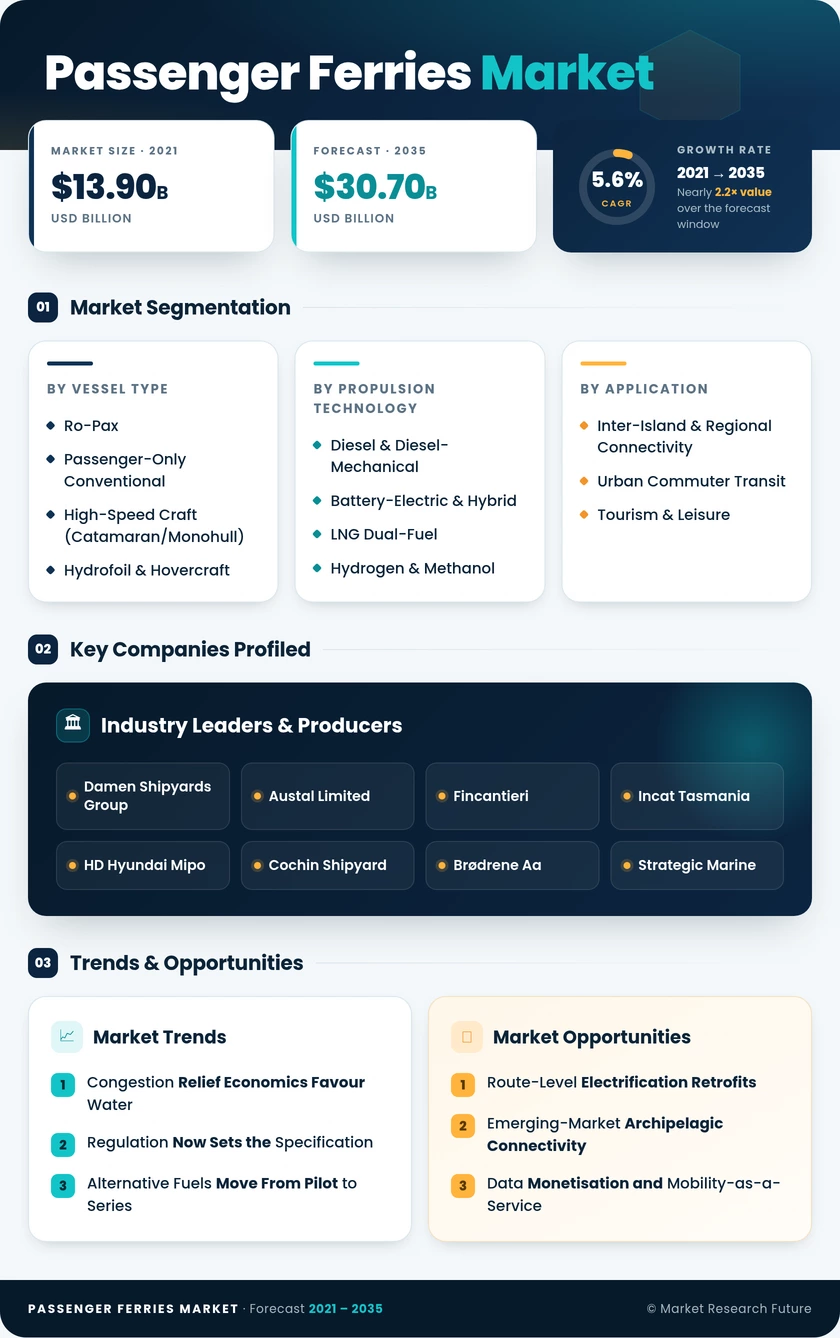
Passenger Ferries Market (2026 - 2035)

ID: MRFR/AT/20955-HCR 128 Pages Shubham Munde Last Updated: September 17, 2026
Passenger Ferries Market Research Report By Ferry Type (Ro-Pax, Passenger-Only Conventional, High-Speed Craft (Catamaran/Monohull), Hydrofoil & Hovercraft), By Propulsion Technology (Diesel & Diesel-Mechanical, Battery-Electric & Hybrid, LNG Dual-Fuel, Hydrogen & Methanol), By Application (Island & Remote Connectivity, Commuter & Public Transit, Tourism & Leisure), By Passenger Capacity Class (Below 100 Passengers, 100–400 Passengers, Above 400 Passengers) - Forecast to 2035
Passenger Ferries Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.6%
2025 Market SizeUSD 17.8 Billion
2035 Market SizeUSD 30.7 Billion
Key Players
Damen Shipyards Group
Austal Limited
Fincantieri
Incat Tasmania
HD Hyundai Mipo
Cochin Shipyard
Opportunities
  • Route-Level Electrification Retrofits
  • Emerging-Market Archipelagic Connectivity
  • Data Monetisation and Mobility-as-a-Service
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Report Takeaways | |
    1. 2.1 Takeaways by Propulsion Type | |
    2. 2.2 Takeaways by Application | |
    3. 2.3 Takeaways by Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Driver Impact Analysis | |
    1. 4.1 Congestion Relief Economics Favour Water | |
    2. 4.2 Regulation Now Sets the Specification | |
    3. 4.3 Alternative Fuels Move From Pilot to Series | |
    4. 4.4 Driver Impact Weighting Matrix | |
  5. 5 Market Dynamics — Restraints Impact Analysis | |
    1. 5.1 Shipyard Capacity Constraints & Lead Times | |
    2. 5.2 Shore Power & Charging Infrastructure Gaps | |
    3. 5.3 Capital Intensity, Crewing & Fuel Availability | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Route-Level Electrification Retrofits | |
    2. 6.2 Emerging-Market Archipelagic Connectivity | |
    3. 6.3 Data Monetisation & Mobility-as-a-Service | |
    4. 6.4 Gulf & Red Sea Tourism Fleets | |
    5. 6.5 Standardised Modular Platforms | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 Asia-Pacific | | |
      1. 7.1.1 China | | |
      2. 7.1.2 Indonesia | | |
      3. 7.1.3 Japan | | |
      4. 7.1.4 Philippines | | |
      5. 7.1.5 India | | |
      6. 7.1.6 South Korea | | |
      7. 7.1.7 Australia | | |
      8. 7.1.8 Rest of Asia-Pacific | |
    2. 7.2 Europe | | |
      1. 7.2.1 Norway | | |
      2. 7.2.2 Greece | | |
      3. 7.2.3 Italy | | |
      4. 7.2.4 United Kingdom | | |
      5. 7.2.5 Denmark | | |
      6. 7.2.6 Germany | | |
      7. 7.2.7 Rest of Europe | |
    3. 7.3 North America | | |
      1. 7.3.1 United States | | |
      2. 7.3.2 Canada | | |
      3. 7.3.3 Mexico | |
    4. 7.4 Middle East & Africa | | |
      1. 7.4.1 United Arab Emirates | | |
      2. 7.4.2 Saudi Arabia | | |
      3. 7.4.3 Egypt | | |
      4. 7.4.4 Rest of Middle East & Africa | |
    5. 7.5 South America | | |
      1. 7.5.1 Brazil | | |
      2. 7.5.2 Argentina | | |
      3. 7.5.3 Chile | | |
      4. 7.5.4 Rest of South America | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomy Reaches Commercial Waters | |
    2. 8.2 The Electrification Supercycle | |
    3. 8.3 Fuel Pathway Divergence | |
    4. 8.4 Disclosure Becomes a Procurement Filter | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Ferry Type | | |
      1. 9.1.1 Ro-Pax | | |
      2. 9.1.2 Passenger-Only Conventional | | |
      3. 9.1.3 High-Speed Craft (Catamaran/Monohull) | | |
      4. 9.1.4 Hydrofoil & Hovercraft | |
    2. 9.2 By Propulsion Technology | | |
      1. 9.2.1 Diesel & Diesel-Mechanical | | |
      2. 9.2.2 Battery-Electric & Hybrid | | |
      3. 9.2.3 LNG Dual-Fuel | | |
      4. 9.2.4 Hydrogen & Methanol | |
    3. 9.3 By Application | | |
      1. 9.3.1 Island & Remote Connectivity | | |
      2. 9.3.2 Commuter & Public Transit | | |
      3. 9.3.3 Tourism & Leisure | |
    4. 9.4 By Passenger Capacity Class | | |
      1. 9.4.1 Below 100 Passengers | | |
      2. 9.4.2 100–400 Passengers | | |
      3. 9.4.3 Above 400 Passengers | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Damen Shipyards Group | | |
      2. 10.3.2 Austal Limited | | |
      3. 10.3.3 Fincantieri | | |
      4. 10.3.4 Incat Tasmania | | |
      5. 10.3.5 HD Hyundai Mipo | | |
      6. 10.3.6 Cochin Shipyard | | |
      7. 10.3.7 Brødrene Aa | | |
      8. 10.3.8 Strategic Marine | | |
      9. 10.3.9 Wight Shipyard Co. | | |
      10. 10.3.10 Astilleros Armon | |
  11. 11 Recent Developments & News (2023–2025) | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Passenger Ferries Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Passenger Ferries Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Weighting Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Weighting Matrix, 2026–2035 | |
  19. TABLE 5 Global Passenger Ferries Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 Asia-Pacific Passenger Ferries Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Passenger Ferries Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 North America Passenger Ferries Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 Middle East & Africa Passenger Ferries Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 South America Passenger Ferries Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Passenger Ferries Market Size, by Vessel Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Passenger Ferries Market Size, by Propulsion Technology, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Passenger Ferries Market Size, by Application, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Passenger Ferries Market Size, by Passenger Capacity Class, 2021–2035 (USD Billion) | |
  29. TABLE 15 Asia-Pacific Passenger Ferries Market Size, by Vessel Type & Propulsion, 2021–2035 (USD Billion) | |
  30. TABLE 16 Europe Passenger Ferries Market Size, by Vessel Type & Propulsion, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Passenger Ferries Market Size, by Vessel Type & Propulsion, 2021–2035 (USD Billion) | |
  32. TABLE 18 Middle East & Africa Passenger Ferries Market Size, by Vessel Type & Propulsion, 2021–2035 (USD Billion) | |
  33. TABLE 19 South America Passenger Ferries Market Size, by Vessel Type & Propulsion, 2021–2035 (USD Billion) | |
  34. TABLE 20 Competitive Benchmarking Matrix — Global Passenger Ferries Market, 2026 | |
  35. TABLE 21 Company Profiles — Key Players, Global Passenger Ferries Market | |
  36. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 | |
  37. TABLE 23 Report Scope & Methodology Summary | |
  38. TABLE 24 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  39. FIGURE 1 Global Passenger Ferries Market — Market Dynamics Snapshot (Drivers, Restraints, Opportunities) | |
  40. FIGURE 2 Industry Value Chain Analysis — Design, Build, Systems, Operations, Aftermarket | |
  41. FIGURE 3 Porter's Five Forces Analysis — Global Passenger Ferries Market | |
  42. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) | |
  43. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) | |
  44. FIGURE 6 Market Share by Vessel Type, 2025 vs 2035 (%) | |
  45. FIGURE 7 Market Share by Propulsion Technology, 2025 vs 2035 (%) | |
  46. FIGURE 8 Market Share by Application, 2025 (%) | |
  47. FIGURE 9 Market Share by Passenger Capacity Class, 2025 (%) | |
  48. FIGURE 10 Regional Market Share Distribution, 2025 (%) | |
  49. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) | |
  50. FIGURE 12 Country-Level Contribution Within Asia-Pacific, 2025 (%) | |
  51. FIGURE 13 Country-Level Contribution Within Europe, 2025 (%) | |
  52. FIGURE 14 Competitive Landscape — Estimated Revenue Share Positioning, 2026 | |
  53. FIGURE 15 Strategic Positioning Matrix — Technology Capability vs Delivery Scale | |
  54. FIGURE 16 Alternative Fuel Adoption Curve, 2021–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Vessel TypeRo-Pax; Passenger-Only Conventional; High-Speed Craft (Catamaran/Monohull); Hydrofoil & HovercraftRo-PaxHigh-Speed Craft (Catamaran/Monohull)
By Propulsion TechnologyDiesel & Diesel-Mechanical; Battery-Electric & Hybrid; LNG Dual-Fuel; Hydrogen & MethanolDiesel & Diesel-MechanicalBattery-Electric & Hybrid
By ApplicationInter-Island & Regional Connectivity; Urban Commuter Transit; Tourism & LeisureInter-Island & Regional ConnectivityUrban Commuter Transit
By Passenger Capacity ClassBelow 100 Passengers; 100–400 Passengers; Above 400 Passengers100–400 PassengersBelow 100 Passengers
By RegionAsia-Pacific; Europe; North America; Middle East & Africa; South AmericaAsia-PacificMiddle East & Africa


Market Segmentation Overview

By Vessel Type

Sub-SegmentKey Trend
Ro-PaxFleet renewal on lifeline routes with LNG dual-fuel and hybrid shaft generators
Passenger-Only ConventionalRapid electrification on short urban and river crossings
High-Speed Craft (Catamaran/Monohull)Lightweight aluminium designs winning tourism and premium transit tenders
Hydrofoil & HovercraftNiche revival on short high-speed island links with efficiency-focused hull forms


Vessel type remains the strongest predictor of unit value. Ro-Pax hulls carry the systems complexity and steel weight that lift average contract price, while passenger-only craft turn over faster and therefore drive unit volume in municipal procurement.

By Propulsion Technology

Sub-SegmentKey Trend
Diesel & Diesel-MechanicalRetained on long crossings; increasingly specified as hybrid-ready
Battery-Electric & HybridFastest adoption on sub-45-minute routes with public charging support
LNG Dual-FuelBaltic and Mediterranean Ro-Pax renewal maintains steady orders.
Hydrogen & MethanolPilot-to-series transition dependent on bunkering cost and subsidy


Propulsion selection now precedes hull design rather than following it. Weight, battery room volume and shore interface requirements cascade into every downstream specification decision.

By Application

Sub-SegmentKey Trend
Inter-Island & Regional ConnectivityPublic service obligation contracts underwrite predictable replacement demand.
Urban Commuter TransitIntegration into unified transit fare systems lifts ridership and utilisation.
Tourism & LeisurePremium interiors and low-emission credentials command fare premiums


Application mix determines financing structure. Contracted lifeline routes attract lower-cost debt, while tourism-exposed operators face cyclical revenue and correspondingly tighter lending terms.

By Passenger Capacity Class

Sub-SegmentKey Trend
Below 100 PassengersHighest growth from urban water taxi and river metro deployments
100–400 PassengersCore commuter and regional workhorse class with broadest yard supply
Above 400 PassengersConcentrated in Ro-Pax and large fast-craft tourism operations


Capacity class correlates tightly with electrification readiness. Smaller hulls electrify first because energy demand per crossing fits within commercially available battery packages without compromising payload.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.