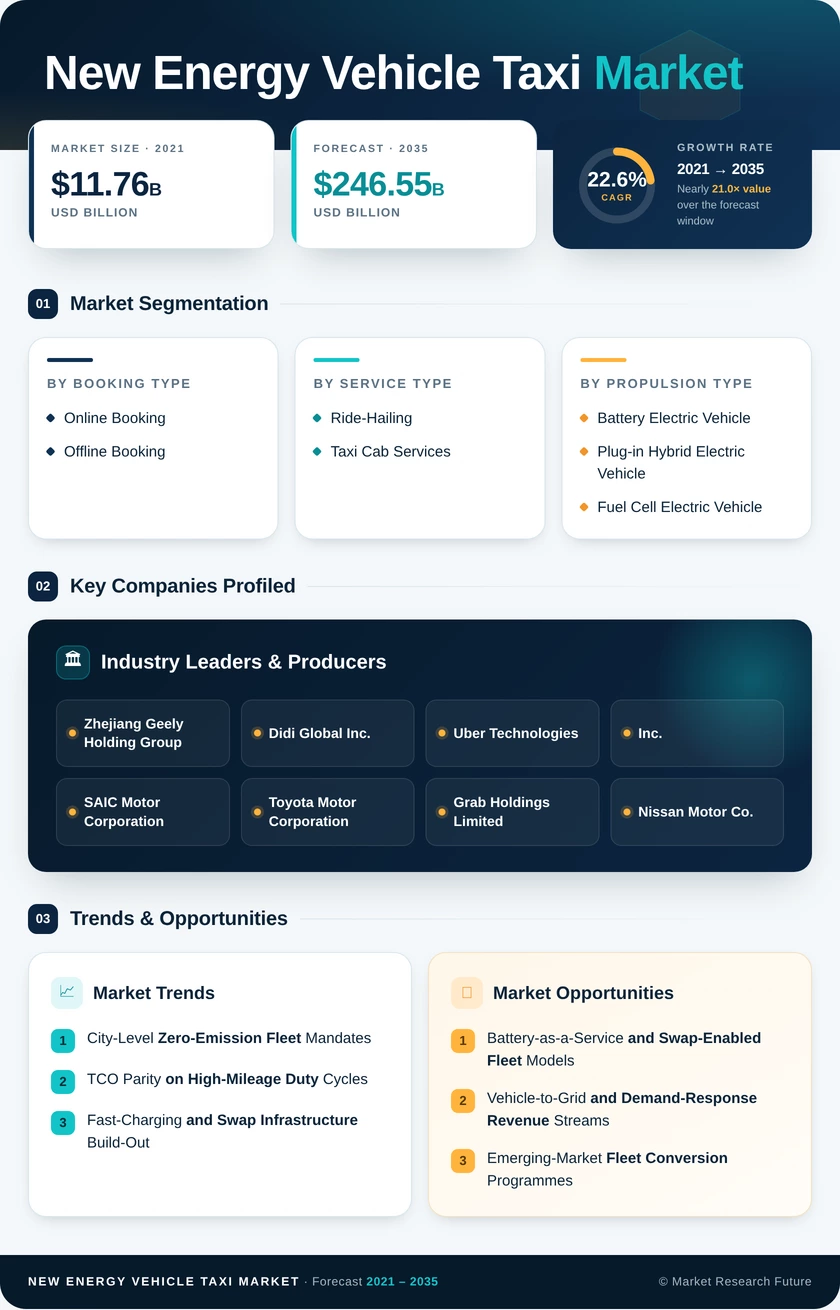
New Energy Vehicle (NEV) Taxi Market (2026 - 2035)

ID: MRFR/AT/9144-HCR 111 Pages Triveni Bhoyar Last Updated: September 16, 2026
New Energy Vehicle (NEV) Taxi Market Research Report By Booking Type (Online Booking, Offline Booking), By Service Type (Ride-Hailing, Taxi Cab Services), By Propulsion Type (Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle), By Vehicle Type (Hatchback, Sedan, Multipurpose Vehicle, Sport Utility Vehicle), By Range Type (Intracity Urban Use, Intercity Long-Distance Use), By Ownership Type (Company-Owned, Driver-Owned, Aggregator-Leased) - Forecast to 2035
New Energy Vehicle (NEV) Taxi Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)22.6%
2025 Market SizeUSD 32.14 Billion
2035 Market SizeUSD 246.55 Billion
Key Players
Zhejiang Geely Holding Group
Didi Global Inc.
Uber Technologies, Inc.
SAIC Motor Corporation
Toyota Motor Corporation
Grab Holdings Limited
Opportunities
  • Battery-as-a-Service and Swap-Enabled Fleet Models
  • Vehicle-to-Grid and Demand-Response Revenue Streams
  • Telematics Data Monetisation and Usage-Based Insurance
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Booking Type | |
    2. 2.2 By Service Type | |
    3. 2.3 By Propulsion Type | |
    4. 2.4 By Vehicle Type | |
    5. 2.5 By Range Type | |
    6. 2.6 By Ownership Type | |
    7. 2.7 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 City-Level Zero-Emission Fleet Mandates | |
    2. 4.2 TCO Parity on High-Mileage Duty Cycles | |
    3. 4.3 Fast-Charging and Swap Infrastructure Build-Out | |
    4. 4.4 Platform Fleet Electrification Commitments | |
    5. 4.5 Declining LFP Cell Costs and Local Manufacturing | |
    6. 4.6 Purchase Subsidies, Licence Quotas, and Tax Exemptions | |
    7. 4.7 Autonomous Dispatch and Labour-Cost Displacement | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Charging Coverage Gaps Outside First-Tier Cities | |
    2. 5.2 Grid Interconnection and Depot Power Limits | |
    3. 5.3 Residual Value Uncertainty and Battery Degradation | |
    4. 5.4 Hydrogen Refuelling Cost and Station Scarcity | |
    5. 5.5 Subsidy Withdrawal and Policy Volatility | |
  6. 6 Opportunities | |
    1. 6.1 Battery-as-a-Service and Swap-Enabled Fleet Models | |
    2. 6.2 Vehicle-to-Grid and Demand-Response Revenue Streams | |
    3. 6.3 Emerging-Market Fleet Conversion Programmes | |
    4. 6.4 Telematics Data Monetisation and Usage-Based Insurance | |
    5. 6.5 Hydrogen Corridors and Regulated Airport Lanes | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Supervised Autonomy Reshapes Cost Structure | |
    2. 8.2 Platform Consolidation of Vehicle Ownership | |
    3. 8.3 Battery Supply and the Electrification Supercycle | |
    4. 8.4 Emissions Disclosure Becomes a Procurement Criterion | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Booking Type | | |
      1. 9.1.1 Online Booking | | |
      2. 9.1.2 Offline Booking | |
    2. 9.2 By Service Type | | |
      1. 9.2.1 Ride-Hailing | | |
      2. 9.2.2 Taxi Cab Services | |
    3. 9.3 By Propulsion Type | | |
      1. 9.3.1 Battery Electric Vehicle | | |
      2. 9.3.2 Plug-in Hybrid Electric Vehicle | | |
      3. 9.3.3 Fuel Cell Electric Vehicle | |
    4. 9.4 By Vehicle Type | | |
      1. 9.4.1 Hatchback | | |
      2. 9.4.2 Sedan | | |
      3. 9.4.3 Multipurpose Vehicle | | |
      4. 9.4.4 Sport Utility Vehicle | |
    5. 9.5 By Range Type | | |
      1. 9.5.1 Intracity Urban Use | | |
      2. 9.5.2 Intercity Long-Distance Use | |
    6. 9.6 By Ownership Type | | |
      1. 9.6.1 Company-Owned | | |
      2. 9.6.2 Driver-Owned | | |
      3. 9.6.3 Aggregator-Leased | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 BYD Company Limited | | |
      2. 10.3.2 Zhejiang Geely Holding Group | | |
      3. 10.3.3 Didi Global Inc. | | |
      4. 10.3.4 Uber Technologies, Inc. | | |
      5. 10.3.5 SAIC Motor Corporation | | |
      6. 10.3.6 Toyota Motor Corporation | | |
      7. 10.3.7 Hyundai Motor Company | | |
      8. 10.3.8 Grab Holdings Limited | | |
      9. 10.3.9 Nissan Motor Co., Ltd. | | |
      10. 10.3.10 ANI Technologies (Ola) | | |
      11. 10.3.11 Bolt Technology OÜ | | |
      12. 10.3.12 HysetCo SAS | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Conversion Basis | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global New Energy Vehicle Taxi Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global New Energy Vehicle Taxi Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Estimated Contribution to CAGR, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Estimated Suppression of CAGR, 2026–2035 | |
  19. TABLE 5 Global New Energy Vehicle Taxi Market Size, by Booking Type, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global New Energy Vehicle Taxi Market Size, by Service Type, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global New Energy Vehicle Taxi Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global New Energy Vehicle Taxi Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  23. TABLE 9 Global New Energy Vehicle Taxi Market Size, by Range Type, 2021–2035 (USD Billion) | |
  24. TABLE 10 Global New Energy Vehicle Taxi Market Size, by Ownership Type, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global New Energy Vehicle Taxi Market Size, by Region, 2021–2035 (USD Billion) | |
  26. TABLE 12 North America New Energy Vehicle Taxi Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 Europe New Energy Vehicle Taxi Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 Asia-Pacific New Energy Vehicle Taxi Market Size, by Country, 2021–2035 (USD Billion) | |
  29. TABLE 15 South America New Energy Vehicle Taxi Market Size, by Country, 2021–2035 (USD Billion) | |
  30. TABLE 16 Middle East & Africa New Energy Vehicle Taxi Market Size, by Country, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America New Energy Vehicle Taxi Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 Europe New Energy Vehicle Taxi Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  33. TABLE 19 Asia-Pacific New Energy Vehicle Taxi Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Competitive Benchmarking Matrix – Global New Energy Vehicle Taxi Market, 2026 | |
  35. TABLE 21 Company Profiles – Key Players, Global New Energy Vehicle Taxi Market | |
  36. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 | |
  37. TABLE 23 Report Scope & Methodology Summary | |
  38. TABLE 24 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  39. FIGURE 1 Market Dynamics – Drivers, Restraints, and Opportunities Snapshot | |
  40. FIGURE 2 Industry Value Chain Analysis – Vehicle Supply to Trip Delivery | |
  41. FIGURE 3 Porter's Five Forces Analysis – New Energy Vehicle Taxi Market | |
  42. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  43. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 (%) | |
  44. FIGURE 6 Market Share by Booking Type, 2025 vs 2035 (%) | |
  45. FIGURE 7 Market Share by Service Type, 2025 (%) | |
  46. FIGURE 8 Market Share by Propulsion Type, 2025 vs 2035 (%) | |
  47. FIGURE 9 Market Share by Vehicle Type, 2025 (%) | |
  48. FIGURE 10 Market Share by Range Type, 2025 (%) | |
  49. FIGURE 11 Market Share by Ownership Type, 2025 (%) | |
  50. FIGURE 12 Regional Market Share Distribution, 2025 (%) | |
  51. FIGURE 13 Regional CAGR Comparison, 2026–2035 (%) | |
  52. FIGURE 14 Country-Level Share within Asia-Pacific, 2025 (%) | |
  53. FIGURE 15 Competitive Landscape – Estimated Revenue Share Positioning, 2026 | |
  54. FIGURE 16 Charging and Swap Infrastructure Density by Region, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Booking TypeOnline Booking; Offline BookingOnline Booking (62.5% share, 2025)Offline Booking (19.8% CAGR)
By Service TypeRide-Hailing; Taxi Cab ServicesRide-Hailing (68.1% share, 2025)Ride-Hailing (68.1% share, 2025)
By Propulsion TypeBattery Electric Vehicle; Plug-in Hybrid Electric Vehicle; Fuel Cell Electric VehicleBattery Electric Vehicle (50.8% share, 2025)Fuel Cell Electric Vehicle (22.8% CAGR)
By Vehicle TypeHatchback; Sedan; Multipurpose Vehicle; Sport Utility VehicleHatchback (44.8% share, 2025)Multipurpose Vehicle (22.7% CAGR)
By Range TypeIntracity Urban Use; Intercity Long-Distance UseIntracity Urban Use (77.5% share, 2025)Intercity Long-Distance Use (22.8% CAGR)
By Ownership TypeCompany-Owned; Driver-Owned; Aggregator-LeasedCompany-Owned (USD 18.77 Billion, 2025)Aggregator-Leased (23.1% CAGR)


Market Segmentation Overview

By Booking Type

Sub-SegmentKey Trend
Online BookingAlgorithmic dispatch and trip metadata enable charging to be scheduled into demand troughs
Offline BookingRegulated rank and street-hail licences preserve a stable floor in Japan and Germany


Online Booking leads this dimension because dispatch software converts an expensive electric asset into a higher-utilisation one, cutting empty-mile ratios and shortening capital payback. Offline Booking posts the higher relative growth rate only because its base is small and licence structures protect it; new entrants launch app-first almost without exception. The practical consequence for fleet planners is that charging schedules are increasingly written by dispatch algorithms rather than by depot managers.

By Service Type

Sub-SegmentKey Trend
Ride-HailingCorporate Scope 3 contracts and airport transfers migrate to app-based dispatch
Taxi Cab ServicesFixed-fare regulation and cooperative ownership slow fleet turnover


Ride-Hailing is both the largest and the fastest-expanding sub-segment, because centralised procurement spreads depot charging capital across thousands of vehicles and pooled algorithms raise seat occupancy without adding units. Taxi Cab Services retain meaningful volume where municipal licensing guarantees fare structures, but fragmented cooperative ownership means each operator funds charging individually. That capital fragmentation, more than vehicle price, explains the conversion gap between the two.

By Propulsion Type

Sub-SegmentKey Trend
Battery Electric Vehicle800 V architectures and swap-compatible LFP packs compress downtime
Plug-in Hybrid Electric VehicleTransitional compliance option in cities with thin charging density
Fuel Cell Electric VehicleThree-to-five-minute refuelling suits cold and hot-climate duty cycles


Battery Electric Vehicle dominates on cell economics: lithium-iron-phosphate chemistry tolerates the repeated fast-charging that taxi shifts demand and delivers thousands of cycles at low cost. Fuel Cell Electric Vehicle grows fastest, winning high-latitude cities where sub-zero operation derates batteries and desert cities where thermal management penalises them. Plug-in Hybrid Electric Vehicle functions as a compliance bridge and loses relevance wherever charging density crosses operator thresholds.

By Vehicle Type

Sub-SegmentKey Trend
HatchbackSmallest pack size and lowest energy consumption per kilometre
SedanPreferred body style for airport and business-travel fare classes
Multipurpose VehicleAccessibility quotas and pooled rides drive seven-seat and ramp-equipped orders
Sport Utility VehiclePremium and tourist fare classes in high-fare cities


Hatchback holds the leading position because value-conscious fleets buy the smallest viable battery, and dense city grids reward a manoeuvrable footprint on short trips. Multipurpose Vehicle grows fastest as jurisdictions mandate a fixed proportion of wheelchair-accessible units per fleet licence and swap networks neutralise the charging-time penalty that once favoured compact bodies. Sedan remains steady on airport lanes, while Sport Utility Vehicle stays niche on list price and energy demand.

By Range Type

Sub-SegmentKey Trend
Intracity Urban UseAverage trip lengths below 15 km with frequent depot returns
Intercity Long-Distance UseCorridor fast-charging obligations and overnight tariff arbitrage


Intracity Urban Use dominates because taxi density concentrates where trips are short and vehicles return to depot several times per shift, making slow overnight charging sufficient. Intercity Long-Distance Use expands fastest as highway charging obligations take effect and electricity spot-market reforms let operators charge cheaply before pre-dawn airport runs. Fuel-cell vehicles have taken an early position in the intercity category because their refuelling pattern mirrors gasoline behaviour drivers already know.

By Ownership Type

Sub-SegmentKey Trend
Company-OwnedDepot infrastructure amortised across large fleets and bulk purchase pricing
Driver-OwnedLicence structures favouring individual operators in India, Brazil, and Europe
Aggregator-LeasedBundled vehicle, energy, insurance, and maintenance subscriptions


Company-Owned leads because a single depot connection and one procurement negotiation serve hundreds of vehicles, which is the cheapest route to charging capital. Aggregator-Leased is the fastest-growing sub-segment, converting drivers who cannot access financing by replacing a purchase decision with a weekly payment. Driver-Owned retains substantial share in licence regimes built around individual operators, but residual-value uncertainty keeps individual borrowing costs high and conversion slow.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.