Molecular Sieves Market (2026 - 2035)

Molecular Sieves Market Research Report Information By Shape (Pelleted, Beaded, and Powdered), By Size (Pore Classification) (Microporous, Mesoporous, and Macroporous), By Product Type (Zeolite, Silica Gel, Carbon, Clay, and Porous Glass), By End-User Industry (Oil and Gas, Waste and Water Treatment, Pharmaceutical, Automotive, Cosmetics and Detergent, and Others), and By Region (North America, Europe, Asia-Pacific, and Rest Of The World) - Forecast Till 2035
ID: MRFR/CnM/6965-CR 215 Pages Chitranshi Jaiswal Last Updated: September 16, 2026
Molecular Sieves Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.9%
2025 Market SizeUSD 4.48 Billion
2035 Market SizeUSD 7.23 Billion
Key Players
Honeywell
BASF SE
Tosoh Corporation
Arkema SA
W.R. Grace & Co.
Zeochem AG
Opportunities
  • Anti-Microbial Zeolite Molecular Sieves
  • Hydrogen Economy and Green-Hydrogen Purification
  • Biogas Upgrading in Emerging Markets
 

Molecular Sieves Market Summary

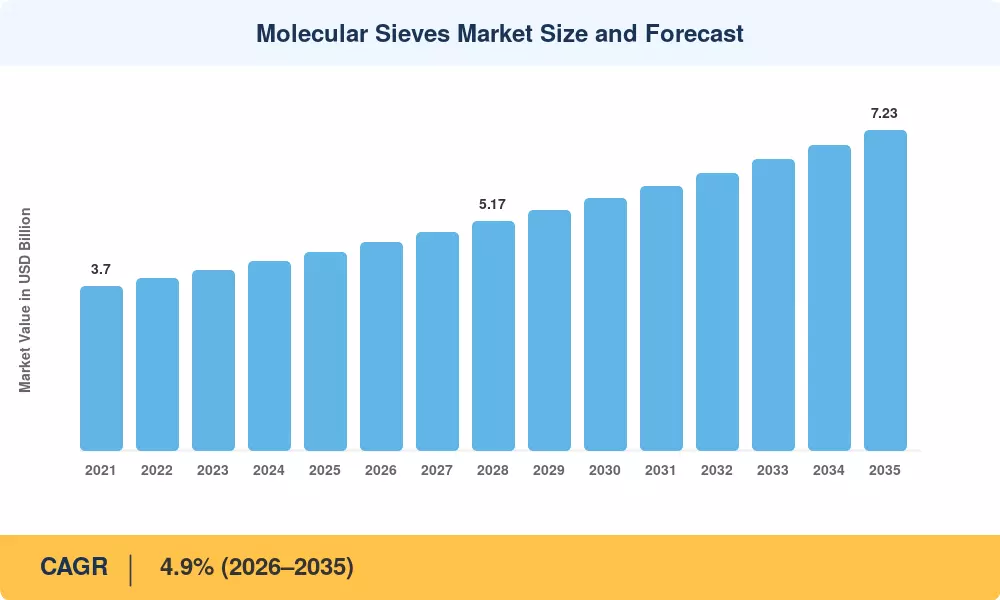
The global Molecular Sieves Market stood at USD 4.48 Billion in 2025 and is projected to reach USD 4.70 Billion in 2026 before climbing to USD 7.23 Billion by 2035, registering a CAGR of 4.9% across the 2026–2035 forecast window. Tightening environmental regulations on volatile organic compound (VOC) emissions, particularly the US EPA's updated National Emission Standards for Hazardous Air Pollutants and China's "Blue Sky" action plan, continue to channel investment toward high-performance adsorption materials and industrial desiccants used in emission abatement and gas purification systems[2].

A generational change in separation technology is ongoing across the petroleum refining and petrochemical industry. Traditional silica-based drying columns are being replaced by a new generation of zeolite materials with improved selectivity and longer regeneration cycles. The International Energy Agency projects that worldwide refining capacity expansions will be 4.7 million barrels per day through 2030 [3][4]. Each of these installations will require catalytic materials and gas drying agents for unit operations ranging from fluid catalytic cracking to hydrocracking.


Asia-Pacific accounts for some 46% of world consumption, driven by China's refinery expansion initiatives and India's rollout of city-gas distribution. The region is also the fastest-growing region with a CAGR of ~5.4%. North America is the second-largest share contributor with around 22% due to the demand for moisture control products and air purification adsorbents in shale gas processing. Europe comes in at around 19%, with the EU’s Circular Economy Action Plan and increased industrial filtering requirements leading the charge. These three blocs together will define the competitive environment of the Molecular Sieves Market up to 2035 [6].


Key Report Takeaways

• By Product Type

  • Zeolite-based molecular sieves account for the dominant share of the Molecular Sieves Market, exceeding 52% of global revenue in 2025, owing to unmatched pore uniformity and thermal stability
  • Carbon-based variants are expanding at the highest CAGR of roughly 6.1%, fueled by biogas upgrading and nitrogen-generation applications

• By End-User Industry

  • Oil and gas remains the largest end-user sector, contributing approximately USD 1.48 Billion in 2025, reflecting the sector's continuous need for gas separation adsorbents and catalytic materials
  • Waste and water treatment ranks as the fastest-growing application, with a forecast CAGR near 5.8%, as municipalities invest in advanced adsorption materials for contaminant removal

• By Region

  • Asia-Pacific leads the Molecular Sieves Market with a 46% share, underpinned by heavy industrial output in China, India, and ASEAN nations
  • South America's CAGR of approximately 5.1% reflects rising petrochemical capacity in Brazil and Argentina


Market Size and Forecast (2021–2035)

The forecast model is an aggregate of revenues from manufacturer disclosures and trade-level import/export data, combined with a top-down cross-validation against macroeconomic factors such as industrial output indices and refinery utilization rates[7].
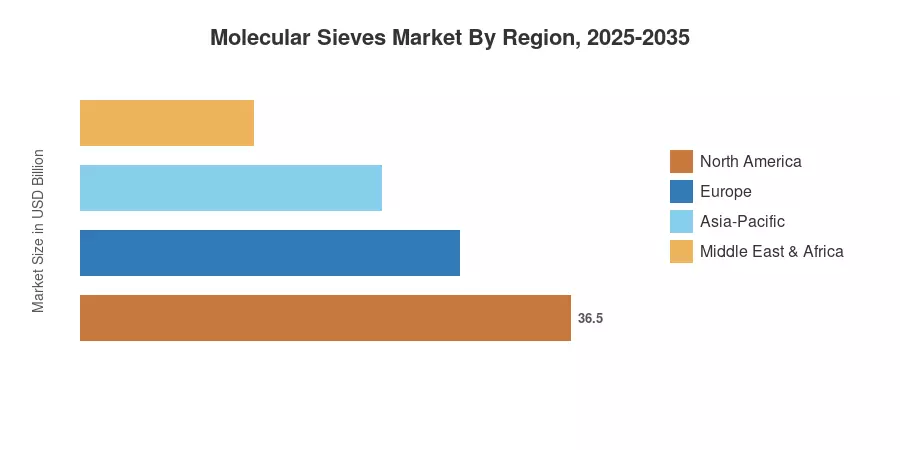
Molecular Sieves Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Petroleum refining capacity expansion +1.2% Global Short-term (≤2 yr)
Stricter VOC and emission regulations +0.9% North America, Europe Medium-term (2–4 yr)
Natural-gas dehydration demand growth +0.8% North America, Middle East Short-term (≤2 yr)
Wastewater treatment mandates +0.7% Asia-Pacific, Europe Medium-term (2–4 yr)
Hydrogen purification requirements +0.5% Europe, Asia-Pacific Long-term (≥4 yr)
Pharmaceutical solvent recovery growth +0.4% North America, India Medium-term (2–4 yr)
Biogas upgrading for renewable natural gas +0.3% Europe, South America Long-term (≥4 yr)


Petroleum Refining and Petrochemical Expansion

Global refining throughput is set to expand by an estimated 6.2 million barrels per day between 2025 and 2032, with over 60% of new capacity concentrated in Asia-Pacific and the Middle East [3]. Every new fluid catalytic cracking or hydrocracking unit requires zeolite materials and industrial desiccants for feed-gas conditioning, catalyst bed regeneration, and product dehydration. China's Zhejiang Petrochemical Phase-III project alone will demand an estimated 4,800 metric tons of molecular sieve inventory upon commissioning, illustrating the scale of demand each mega-refinery generates for the Molecular Sieves Market .

Environmental Emission Regulations

The US EPA finalized revised NESHAP rules for petroleum refineries in 2024, mandating a 35% reduction in fugitive VOC emissions by 2028 [2]. Compliance pathways increasingly rely on pressure-swing adsorption (PSA) and temperature-swing adsorption (TSA) systems loaded with high-performance gas separation adsorbents. In Europe, the Industrial Emissions Directive recast (IED 2.0) proposes binding best-available-technology conclusions that explicitly reference zeolite-based adsorption as a preferred abatement method, creating a regulatory pull for advanced separation technology across the continent [10].

Natural-Gas Processing and Dehydration

The US Energy Information Administration (EIA) projects robust growth for the domestic natural gas sector, with marketed production expected to reach record levels of approximately 124 billion cubic feet per day (Bcf/d) by 2027. This expansion, particularly in the Permian Basin and Haynesville regions, sustains a long-term demand cycle for gas drying agents and dehydration materials essential for cryogenic natural gas liquids (NGL) recovery and pipeline transport. Similar infrastructure developments in Qatar’s North Field and Australian LNG projects reinforce the global requirement for high-durability moisture control materials to prevent hydrate formation and equipment corrosion.


Wastewater and Water Treatment Mandates

Governmental focus on water security and pollution control continues to expand. China’s 14th Five-Year Plan for Ecological and Environmental Protection continues to prioritize investment in water-pollution control infrastructure. Municipal and industrial water-treatment facilities are increasingly adopting adsorption-based tertiary treatment—utilizing zeolite materials and carbon-based media—to remove heavy metals and micropollutants. This segment provides a critical secondary demand channel for the molecular sieves market, offering a level of market stability that is often decoupled from the cyclical fluctuations of the oil-and-gas industry.


Restraints Impact Analysis

The restraint estimates below follow the same directional methodology as Section 4 and represent headwinds that temper the baseline growth trajectory.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Substitution by advanced membrane technologies –0.5% Global Long-term (≥4 yr)
Raw-material price volatility (alumina, silica) –0.4% Global Short-term (≤2 yr)
Energy-intensive regeneration costs –0.3% Europe, North America Medium-term (2–4 yr)
Competition from enzyme-based catalysts –0.2% Europe Long-term (≥4 yr)
Slow regulatory adoption in emerging markets –0.2% South America, Africa Medium-term (2–4 yr)


Membrane Technology Substitution

Polymeric and ceramic membrane systems are maturing rapidly for gas-separation duties that once belonged exclusively to molecular sieve beds. Membrane-based nitrogen generators now achieve 99.5% purity at 30% lower capital expenditure than PSA alternatives in flows under 500 Nm³/h [16]. While membranes remain uncompetitive for large-scale refinery dehydration, their encroachment in mid-scale air purification adsorbent applications and food-packaging gas generation is measurable. The Molecular Sieves Market faces a cumulative revenue displacement estimated at USD 0.18 Billion through 2035 from this vector alone [16][18].

Raw-Material Price Volatility

Synthetic zeolite production depends on high-purity alumina and sodium silicate feedstocks. Alumina spot prices fluctuated between USD 320 and USD 510 per metric ton during 2023–2024, squeezing margins for mid-tier sieve manufacturers that lack backward integration [17]. Such volatility discourages long-term fixed-price contracts and can delay capacity-expansion decisions, constraining supply growth for catalytic materials and industrial desiccants in price-sensitive markets [17].

Energy-Intensive Regeneration

Thermal regeneration of Type 3A and 4A zeolite materials typically requires temperatures of 250–350 °C, translating to significant natural-gas or steam consumption. Under the EU Emissions Trading System Phase IV, carbon costs exceeding EUR 90 per ton make regeneration economics less attractive for smaller operators, pushing some toward disposable desiccant cartridges that bypass the Molecular Sieves Market altogether [18].


Molecular Sieves Market Opportunities

Anti-Microbial Zeolite Molecular Sieves

Silver- and copper-exchanged zeolite materials have demonstrated broad-spectrum antimicrobial efficacy in water treatment and specialized coatings. The global antimicrobial coatings sector is a high-value niche for functionalized adsorption materials, with market valuations estimated at approximately USD 15 billion in 2025. As hygiene awareness and infection control mandates expand, these materials are increasingly utilized as high-performance additives to enhance surface durability and pathogen resistance.


Hydrogen Economy and Green-Hydrogen Purification

Electrolyzer-grade hydrogen demands moisture levels below 1 ppm, a specification best met by high-performance gas drying agents. The IEA projects 130 GW of electrolyzer capacity by 2030, each installation requiring dedicated PSA or TSA molecular sieve units for product-gas polishing. This emerging end-use could add an incremental USD 0.35 Billion to the Molecular Sieves Market by 2035 [12].

Biogas Upgrading in Emerging Markets

Brazil's RenovaBio program mandates blending biomethane into the natural-gas grid, requiring carbon-dioxide removal through catalytic materials and separation technology systems. With over 500 biogas plants expected online by 2030, South America presents a fast-growing greenfield opportunity for suppliers of industrial desiccants and carbon-based molecular sieves [14].

Data-Driven Adsorbent Lifecycle Management

Digital twin platforms and IoT-enabled sieve-bed monitoring allow operators to optimize regeneration cycles, extending bed life by 15–20% and reducing unplanned shutdowns. Licensing predictive analytics software as a service creates a recurring revenue model for sieve manufacturers, complementing traditional product sales within the Molecular Sieves Market.

Pharmaceutical Solvent Recovery

Regulatory guidelines from the FDA and EMA regarding residual solvent limits in active pharmaceutical ingredients continue to drive the use of Type 3A zeolite materials for high-purity ethanol and isopropanol dehydration. India, a global leader in generic medicine production, remains a critical growth pocket; the Indian pharmaceutical sector achieved record exports of approximately USD 30.5 billion in FY2025, reinforcing strong, sustained demand for high-purity separation adsorbents.


Molecular Sieves Market Future Outlook

Hydrogen Economy Integration

Green-hydrogen electrolyzer deployments are projected to exceed 130 GW globally by 2030 (IEA Net Zero Scenario), with each megawatt-scale unit requiring dedicated PSA molecular sieve beds for product-gas polishing to fuel-cell-grade purity [12]. The Molecular Sieves Market stands to capture an incremental USD 0.35–0.50 Billion in cumulative revenue from hydrogen purification alone through 2035, as governments in Europe, Japan, and South Korea execute national hydrogen roadmaps [12].

Digital Operations and Predictive Maintenance

Industrial IoT platforms are transforming sieve-bed management from time-based to condition-based regeneration. Digital twins that model moisture breakthrough curves in real time can extend adsorbent cycle life by 15–20%, reducing both replacement volumes and unplanned downtime. For sieve manufacturers, offering analytics-as-a-service layered on top of product sales creates stickier customer relationships and recurring revenue streams within the Molecular Sieves Market.

Sustainability and Circular-Economy Mandates

The EU's Ecodesign for Sustainable Products Regulation (ESPR), effective from 2026, will require digital product passports for industrial chemicals — including catalytic materials and adsorption materials — documenting lifecycle carbon footprints [10]. Manufacturers investing in low-carbon calcination processes and recycled-alumina feedstocks will secure preferential procurement status under green-public-procurement frameworks, reshaping competitive dynamics in the Molecular Sieves Market [18].

Emerging-Market Industrialization

IRENA estimates that developing economies in Southeast Asia and Sub-Saharan Africa will invest USD 1.4 trillion in energy infrastructure through 2035, encompassing gas-processing plants, LNG regasification terminals, and water-treatment facilities that all require industrial desiccants and gas drying agents . These greenfield markets offer above-average growth for suppliers willing to establish local distribution, technical service, and regeneration support networks.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific ~46% global share Refinery expansion; city-gas distribution; water treatment
North America ~22% global share Shale-gas dehydration; VOC abatement; hydrogen pilots
Europe CAGR ~4.6% IED 2.0 compliance; biogas upgrading; green hydrogen
South America CAGR ~5.1% Biomethane mandates; petrochemical FDI
Middle East & Africa USD 0.28 Billion (2025) LNG mega-projects; desalination pre-treatment
Total USD 4.48 Billion (2025) —

The Molecular Sieves Market exhibits distinct regional demand patterns shaped by industrial maturity, regulatory frameworks, and resource endowments. Asia-Pacific's dominance reflects the region's concentration of refining, petrochemical, and manufacturing capacity, while North America and Europe are driven by regulatory stringency and technological sophistication.


North America

Country Key Metric Key Driver
United States ~74% of regional revenue Permian Basin gas processing; EPA NESHAP compliance
Canada CAGR ~4.5% LNG Canada project; oil-sands upgrader maintenance
Mexico USD 0.06 Billion (2025) PEMEX refinery rehabilitation program


The United States remains the backbone of North American demand for adsorption materials, with natural-gas dehydration consuming the single largest volume of Type 4A and 13X molecular sieves. Canada's LNG Canada facility in Kitimat, British Columbia, scheduled for first cargo in 2025, requires substantial gas drying agents and moisture control materials during commissioning. Mexico's Dos Bocas refinery, while delayed, will add incremental sieve demand once operational [9].

Europe

Country Key Metric Key Driver
Germany ~22% of European revenue Chemical-industry solvent recovery
United Kingdom CAGR ~4.3% North Sea decommissioning; hydrogen blending trials
France USD 0.15 Billion (2025) Nuclear hydrogen program; Arkema domestic supply
Italy ~11% of European share Refinery conversion to biorefineries
Spain CAGR ~4.7% Renewable-gas injection mandates
Nordic Countries USD 0.07 Billion (2025) Biogas-to-grid projects
Russia ~9% of European share Domestic refinery modernization
Rest of Europe CAGR ~4.4% Varied industrial applications


Germany's chemicals sector, the largest in Europe, drives consistent demand for zeolite materials and catalytic materials in solvent-recovery and emission-control applications. The EU's revised Industrial Emissions Directive is accelerating retrofits of existing adsorption systems, creating replacement-cycle demand for air purification adsorbents across the continent. The Molecular Sieves Market in Europe benefits from a mature regulatory environment that rewards performance-grade industrial desiccants [10][18].

Asia-Pacific

Country Key Metric Key Driver
China ~54% of regional revenue Mega-refinery builds; environmental remediation
India CAGR ~6.2% City-gas distribution; pharmaceutical exports
Japan USD 0.18 Billion (2025) Specialty-chemical manufacturing
South Korea ~8% of regional share Petrochemical complex upgrades
ASEAN CAGR ~5.5% Refinery and LNG infrastructure buildout
Rest of Asia-Pacific USD 0.09 Billion (2025) Emerging industrial demand


China accounts for over half of Asia-Pacific consumption of adsorption materials, reflecting the sheer scale of its refining and petrochemical footprint. India's Petroleum and Natural Gas Regulatory Board has authorized 295 city-gas-distribution licenses, each requiring gas drying agents for pipeline-quality specifications. The Molecular Sieves Market in Asia-Pacific is further supported by Japan's specialty-chemicals sector, which consumes premium-grade separation technology products for electronics-grade solvent dehydration [11].

South America

Country Key Metric Key Driver
Brazil ~58% of regional revenue RenovaBio biomethane; Petrobras refinery upgrades
Argentina CAGR ~5.3% Vaca Muerta shale-gas development
Rest of South America USD 0.04 Billion (2025) Small-scale industrial demand


Brazil's RenovaBio program and Petrobras' ongoing refinery-optimization investments sustain the largest pocket of molecular sieve demand in South America. Argentina's Vaca Muerta formation is attracting foreign direct investment in gas processing infrastructure, creating fresh demand for moisture control materials and industrial filtration materials in a region where the Molecular Sieves Market has historically been undersupplied [14].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~34% of regional revenue Saudi Aramco downstream integration
UAE CAGR ~5.0% ADNOC gas-processing expansion
South Africa USD 0.03 Billion (2025) Sasol CTL operations
Egypt CAGR ~4.8% Mediterranean gas-field development
Rest of MEA ~18% of regional share Desalination pre-treatment; small-scale refining


Saudi Aramco's Jafurah unconventional gas program, targeting 2 billion standard cubic feet per day by 2030, will require massive inventories of gas separation adsorbents and zeolite materials for feed conditioning. The Molecular Sieves Market in this region benefits from LNG-export infrastructure buildouts in Qatar and the UAE, both of which depend on industrial desiccants for pipeline-specification moisture removal.


Molecular Sieves Market By Region, 2025-2035
 

Molecular Sieves Market Segmentation

By Shape

Segment Key Metric Primary Demand Driver
Pelleted ~44% market share Preferred for fixed-bed gas dehydration columns
Beaded CAGR ~5.3% Growing use in PSA and TSA systems
Powdered USD 0.67 Billion (2025) Detergent formulations; polymer additive blending


Pelleted molecular sieves dominate the Molecular Sieves Market because their uniform geometry ensures predictable pressure drop and flow distribution in large-diameter adsorption columns found in refineries and gas plants. Beaded forms are gaining traction as separation technology advances favor rapid-cycle PSA units, where spherical geometry minimizes attrition and dust formation during thousands of pressurization–depressurization cycles. The pelleted segment's maturity means incremental growth is moderate, while beaded variants attract premium pricing in high-cycle applications involving air purification adsorbents[9].

By Size (Pore Classification)

Segment Key Metric Primary Demand Driver
Microporous ~62% market share Core zeolite sieve applications (3A, 4A, 5A, 13X)
Mesoporous CAGR ~5.6% Catalytic cracking; pharmaceutical intermediates
Macroporous USD 0.22 Billion (2025) Pre-filtration and guard-bed applications


Microporous sieves — the workhorse Type 3A, 4A, 5A, and 13X designations — constitute the structural core of the Molecular Sieves Market. Their sub-2-nanometer pore openings deliver the sharp size-exclusion selectivity required for moisture control materials in natural-gas dehydration and ethanol purification. Mesoporous variants are the fastest-growing category, driven by their larger pore architecture that accommodates bulky hydrocarbon molecules in catalytic materials used for FCC catalyst support and specialty-chemical synthesis[4].

By Product Type

Segment Key Metric Primary Demand Driver
Zeolite ~52% market share Dominant across refining, gas processing, water treatment
Silica Gel CAGR ~3.8% Cost-sensitive humidity-control applications
Carbon CAGR ~6.1% Biogas upgrading; nitrogen generation
Clay USD 0.18 Billion (2025) Low-cost industrial filtration materials
Porous Glass ~3% market share Niche laboratory and sensor applications


Zeolite molecular sieves retain their commanding position in the Molecular Sieves Market because no competing material matches their combination of thermal stability, regenerability, and tunable pore dimensions. Carbon-based sieves, the fastest-growing product type, benefit from surging biogas-upgrading installations in Europe and South America, where carbon molecular sieves separate methane from carbon dioxide at ambient temperatures without chemical solvents [14][16].

By End-User Industry

Segment Key Metric Primary Demand Driver
Oil and Gas USD 1.48 Billion (2025) Dehydration, sweetening, catalytic processing
Waste and Water Treatment CAGR ~5.8% Micropollutant removal; heavy-metal adsorption
Pharmaceutical ~12% market share Solvent dehydration; API purification
Automotive CAGR ~4.5% Brake-system desiccation; refrigerant drying
Cosmetics and Detergent USD 0.31 Billion (2025) Zeolite builders replacing phosphates
Others ~8% market share Electronics, food packaging, HVAC


Oil and gas operations consume the largest volume of adsorption materials globally, spanning upstream gas dehydration through downstream product purification. The waste-and-water-treatment segment, however, is posting the highest CAGR within the Molecular Sieves Market as governments tighten discharge standards for pharmaceutical residues, PFAS compounds, and heavy metals — contaminants for which zeolite materials and carbon-based gas separation adsorbents have demonstrated strong removal efficiency [10][13].


Competitive Benchmarking

The Molecular Sieves Market is low concentrated, where the top five manufacturers together account for an estimated 35-40% of the revenue share. A Herfindahl-Hirschman Index below 800 indicates a fragmented competitive structure with regional experts and vertically integrated chemical conglomerates coexisting[17].

Company Est. Revenue Share Range Key Offerings for Molecular Sieves Market Strategic Positioning
Honeywell (UOP) ~8–11% MOLSIV™ adsorbents; PSA/TSA system design Vertically integrated technology licensor
BASF SE ~7–10% Type 4A, 13X zeolite beads; catalytic materials Scale-driven cost leader with global logistics
Tosoh Corporation ~5–8% Zeolum® high-silica zeolites; specialty grades Premium positioning in Asia-Pacific markets
Arkema SA (CECA) ~5–7% Siliporite® molecular sieves; gas drying agents Strong European market presence
W.R. Grace & Co. ~4–6% SYLOBEAD® adsorbents; refinery catalysts Integrated refining-catalyst portfolio
Zeochem AG ~3–5% Z10-Series adsorbents; oxygen concentrator sieves Medical and industrial gas specialist
Clariant AG ~3–5% OxyClean® PSA sorbents; moisture control materials Focus on environmental and specialty applications
Hengye Inc. ~2–4% Type 3A/4A/5A/13X pellets and beads Cost-competitive Chinese manufacturer
KNT Group ~2–4% Activated molecular sieves; industrial desiccants CIS and Eastern European distribution network
Luoyang Jianlong ~2–3% High-volume commodity zeolite pellets Domestic Chinese scale with export ambitions


Recent News & Developments


  • BASF SE (January 2025): BASF is currently focusing its major investments at its Ludwigshafen site on the modernization of intermediates production and capacity expansions for alcoholates and additively manufactured catalysts


  • Arkema SA (August 2024): Arkema continues to execute its growth strategy in Specialty Materials, managing capital expenditures of approximately EUR 600 million annually to support innovation and high-value project ramp-ups in North America and Asia.
  • US EPA (June 2024): The US EPA finalized amendments to the Petroleum Refineries NESHAP (National Emission Standards for Hazardous Air Pollutants) on March 15, 2024, to further reduce toxic air emissions.


Molecular Sieves Market Report Scope

Parameter Detail
Market Scope Global Molecular Sieves Market — production, consumption, and trade of molecular sieve products
Study Period 2021–2035
CAGR 4.9% (2026–2035)
Market Size — 2025 USD 4.48 Billion
Market Size — 2035 USD 7.23 Billion
Fastest Growing Segment Carbon molecular sieves (by product type); Waste and Water Treatment (by end user)
Companies Profiled 10 (Honeywell/UOP, BASF, Tosoh, Arkema, W.R. Grace, Zeochem, Clariant, Hengye, KNT Group, Luoyang Jianlong)
Valuation Currency USD Billion

FAQs

What pore-size designation should buyers specify for natural-gas dehydration?
Type 4A (pore opening ~3.8 Å) is the standard for pipeline natural-gas dehydration because it selectively adsorbs water while excluding methane and heavier hydrocarbons [9].
How do regeneration energy costs compare between thermal-swing and pressure-swing systems?
TSA systems consume 2–3× more energy per cycle than PSA but handle higher moisture loads. PSA suits low-moisture, rapid-cycle applications where electricity is cheaper than steam [18].
Which quality certifications should procurement teams require from molecular sieve suppliers?
Insist on ISO 9001 process certification and ASTM D2219 compliance for crush strength and attrition resistance. These standards ensure consistent performance across batch-to-batch deliveries [23].
How does silver-exchanged zeolite pricing compare with conventional Type 4A sieves?
Silver-exchanged grades cost 5–8× more per kilogram but deliver antimicrobial functionality that conventional industrial desiccants cannot match, justifying the premium in water-treatment applications .
What shelf-life considerations apply to stored molecular sieve inventory?
Sealed drums maintain adsorption capacity for 3–5 years. Once opened, exposure to ambient humidity degrades performance within weeks unless the material is thermally reactivated before use [23].
Are carbon molecular sieves suitable for oxygen-enriched atmosphere generation?
Carbon molecular sieves excel at nitrogen generation via kinetic separation but are not effective for oxygen enrichment; zeolite-based gas separation adsorbents using Type 5A or 13X are preferred for that application [16].
What lead times should buyers expect for large-volume molecular sieve orders?
Standard grades ship in 4–6 weeks from major manufacturers, while custom formulations or specialty catalytic materials may require 10–14 weeks, depending on production scheduling [17].    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, chemical manufacturing reports, and authoritative industrial organizations. Key sources included the US Environmental Protection Agency (EPA), Occupational Safety and Health Administration (OSHA), European Chemicals Agency (ECHA), International Energy Agency (IEA), US Energy Information Administration (EIA), International Organization for Standardization (ISO), American Petroleum Institute (API), Society of Automotive Engineers (SAE), National Institute of Standards and Technology (NIST), US Geological Survey (USGS), China Petroleum and Chemical Industry Federation (CPCIF), and national environmental ministry reports from key markets.

For zeolite molecular sieves, activated carbon adsorbents, clay desiccants, and other adsorbent technologies, these sources were used to gather data on industrial production, safety handling procedures, regulatory compliance, application trends, and market landscape analysis.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. Supply-side sources included CEOs, VPs of Manufacturing Operations, R&D heads, and commercial directors from molecular sieve manufacturers, zeolite makers, and adsorbent technology providers. Demand-side sources were procurement managers, process engineers, and technical directors from oil & gas refineries, petrochemical plants, car manufacturers, packaging firms, and water treatment facilities. Primary research validated market segmentation, confirmed capacity development timetables, and gathered information on industry adoption patterns, bulk pricing tactics, and supply chain dynamics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was calculated using revenue mapping and production volume research. The methods included:

Identification of 50+ key producers across North America, Europe, Asia-Pacific, and Middle East Product mapping spanning 4A, 3A, 5A, 13X, Zeolite Y, and other molecular sieve types Analysis of stated and predicted yearly revenues unique to molecular sieve portfolios

Coverage of manufacturers with 65-70% of global market share in 2024

Extrapolation employing bottom-up (production volume × ASP by region/application) and top-down (manufacturer revenue validation) methodologies to derive segment-specific values

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















