Mezcal Market (2026 - 2035)

Mezcal Market Size, Share, Industry Trend & Analysis Research Report: By Product Type (Mezcal Joven, Mezcal Reposado, Mezcal Añejo), By Production Method (Ancestral Mezcal, Artisanal Mezcal, Industrial Mezcal), By Price Range (Mass, Premium/Luxury), By Distribution Channel (On-Trade, Off-Trade), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035.
ID: MRFR/CG/8093-HCR 128 Pages Snehal Singh Last Updated: September 15, 2026
Mezcal Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)10.2%
2025 Market SizeUSD 0.69 Billion
2035 Market SizeUSD 1.82 Billion
Key Players
Pernod Ricard
Diageo
Bacardi Limited
Davide Campari-Milano
William Grant & Sons
Clase Azul
Opportunities
  • Ready-to-Drink Mezcal Cocktails
  • Direct-to-Consumer E-Commerce Channels
  • Agave-Based Sustainability Branding

Mezcal Market Summary

The Mezcal Market was valued at USD 0.69 Billion in 2025 and is projected to grow from USD 0.76 Billion in 2026 to USD 1.82 Billion by 2035, registering a CAGR of 10.2% during the forecast period (2026–2035). This expansion reflects a sustained consumer shift toward provenance-rich spirits, catalyzed by multinational acquisitions in Oaxaca and surrounding denomination-of-origin states. The Consejo Regulador del Mezcal (CRM) certified over 19 million liters in 2024, a figure that continues to climb as export demand outpaces domestic consumption [1].

Production practices across the Mezcal Market are undergoing a measured transformation. While underground pit roasting and clay-pot distillation remain the regulatory baseline for certified expressions, producers are investing in solar-powered facilities and precision fermentation monitoring to reduce batch inconsistency without sacrificing heritage methods. Mexico's Secretaría de Economía allocated MXN 420 million in 2024 toward sustainable agave cultivation programs designed to stabilize raw material supplies over the next decade [2].

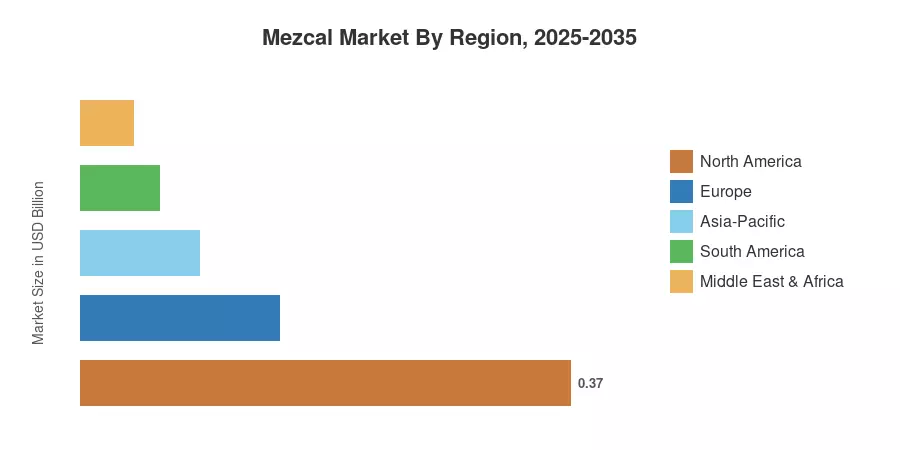
North America commands roughly 53% of global Mezcal Market revenue, anchored by the United States, where mezcal imports surged 18% year-over-year in 2024 [3]. Asia-Pacific is the fastest-growing region, expanding at an estimated 13.1% CAGR through 2035 as cocktail culture takes root in Japan, South Korea, and urban China. Europe holds the second-largest share, driven by premium on-trade penetration across the United Kingdom, Germany, and Spain. As agave maturation cycles tighten supply and premiumization accelerates, the Mezcal Market is poised to transition from a niche category to a mainstream luxury spirit by the mid-2030s.


Key Report Takeaways

• By Product Type

  • Mezcal Joven accounted for approximately 72% of Mezcal Market revenue in 2025, reinforcing its role as the category's gateway expression.
  • Mezcal Añejo is projected to register the fastest CAGR of 13.6% through 2035, driven by collectors and aged-spirit connoisseurs.

• By Production Method

  • Ancestral mezcal dominated the Mezcal Market with an 87% share in 2025.
  • Artisanal mezcal is rising at an 11.9% CAGR as mid-tier brands scale copper-pot distillation.

• By Price Range

  • The mass segment captured 60% of 2025 Mezcal Market sales, though premium offerings are growing at a 12.3% CAGR.


• By Distribution

  • The mass segment captured 60% of 2025 Mezcal Market sales, though premium offerings are growing at a 12.3% CAGR.
  • On-trade venues generated 63% of 2025 value; off-trade channels are outpacing at a 11.2% CAGR.

• By Region

  • North America led the Mezcal Market with a 53% share in 2025.
  • Asia-Pacific is forecast to record a 13.1% CAGR through 2035.


Market Size and Forecast (2021–2035)

Market Research Future's sizing methodology triangulates CRM export certifications, customs trade flow data, and proprietary channel-level surveys across 22 countries. Historical figures reflect actual trade volumes, while forecast estimates incorporate supply-side agave planting cycles, regulatory capacity constraints, and demand elasticity models calibrated to premium spirits benchmarks.
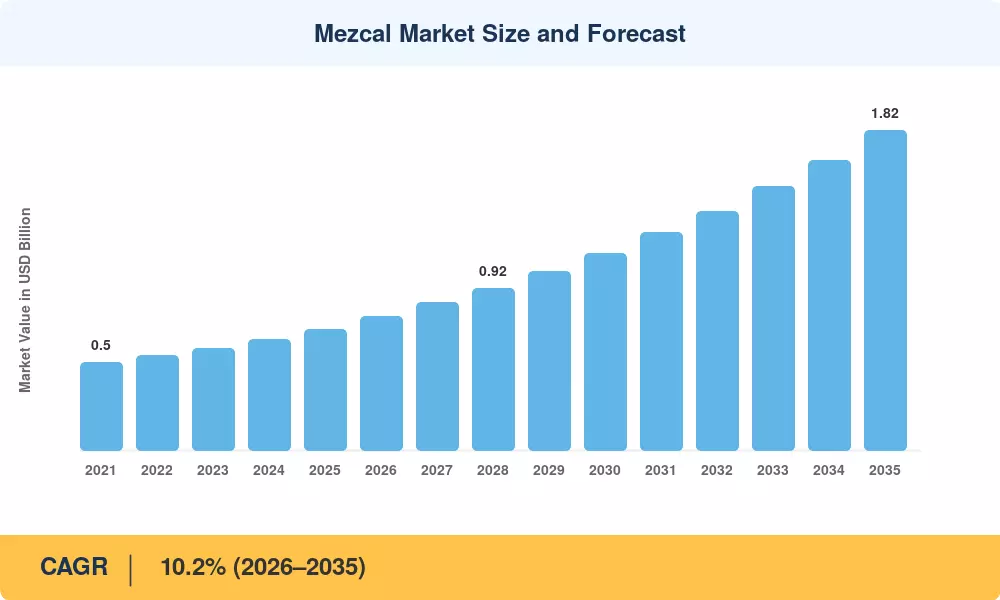
Mezcal Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Premiumization & craft spirit demand +2.8% Global Short-term (≤2 yr)
US cocktail bar mezcal adoption +2.2% North America Short-term (≤2 yr)
CRM denomination-of-origin enforcement +1.5% Mexico, Global Medium-term (2–4 yr)
Asia-Pacific mixology culture expansion +1.4% Asia-Pacific Medium-term (2–4 yr)
Sustainable agave farming investments +1.0% Mexico Long-term (≥4 yr)
E-commerce & DTC spirit platforms +0.8% Global Medium-term (2–4 yr)
Celebrity & brand partnership endorsements +0.5% North America, Europe Short-term (≤2 yr)


Premiumization and Craft Spirit Demand

Consumer willingness to pay for provenance-verified spirits has reshaped the Mezcal Market. The IWSR reported that the global premium-and-above spirits segment outpacing standard categories by a factor of three [5]. Mezcal benefits disproportionately from this shift because its denomination-of-origin requirements embed scarcity into the supply chain. Single-village, single-agave expressions now command USD 80–150 per bottle at retail, and this price ceiling continues to rise as aged variants gain traction among whiskey and cognac collectors.

US Cocktail Bar Adoption

The US distillation industry saw an 18% rise in mezcal imports by value in 2024, becoming the fastest-growing spirits subcategory in the US for the fourth consecutive year (The Distilled Spirits Council of the United States (DISCUS), 2024) [3]. Major metro centers like New York, Los Angeles, Chicago, and Austin have specialized mezcal bars, and big restaurant chains are offering mezcal cocktail menus. This pace in the Mezcal Market’s largest single country is still pushing global growth ahead.


Asia-Pacific Mixology Expansion

Japan’s bar scene took to mezcal before much of the rest of Asia, but South Korea and urban China are closing the gap fast. Between 2022 and 2024, the number of artisan cocktail bars in Seoul increased 24%, and agave-forward drink menus are prominently including mezcal [8]. The double-digit growth trajectory of the Mezcal Market in the region demonstrates both a trial driven by curiosity and a broader regional movement towards imported luxury spirits.


Restraints Impact Analysis

Restraint impacts below are directional estimates of growth-dampening pressure. These figures are not directly subtracted from the CAGR and should be read as relative risk weightings.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Agave maturation cycle (7–12 years) –1.8% Mexico Long-term (≥4 yr)
CRM production capacity limits –1.2% Mexico, Global Medium-term (2–4 yr)
Counterfeit and mislabeled products –0.8% Export markets Short-term (≤2 yr)
High import tariffs in select markets –0.6% Asia-Pacific, MEA Medium-term (2–4 yr)
Consumer confusion with tequila –0.4% Global Short-term (≤2 yr)


Agave Supply Constraints

Espadin agave — the backbone of roughly 85% of certified mezcal — requires 7 to 12 years to reach harvest maturity. Unlike grain-based spirits, producers cannot rapidly scale raw material supplies in response to demand spikes. This biological bottleneck constrains short-term Mezcal Market expansion and pressures input costs upward.

Regulatory Capacity Limits

CRM certification helps as a quality gatekeeper, but it also caps growth pace. Every palenque (distillery) has to have annual inspections and certification backlogs of 6-9 months for new entries. This friction maintains authenticity and the Mezcal Market’s premium positioning but implies supply cannot adapt elastically to demand spikes [1].


Mezcal Market Opportunities

Ready-to-Drink Mezcal Cocktails

Mezcal-based RTD offerings remain nascent, creating a whitespace opportunity. Brands that crack the flavor-stability challenge at scale stand to capture first-mover advantage across the Mezcal Market's mass segment.

Direct-to-Consumer E-Commerce Channels

Online spirits sales in the US grew 34% between 2021 and 2024 [9]. Mezcal producers, many of whom are small-batch operations, can leverage DTC platforms to bypass distributor markups and build brand loyalty. This channel shift is projected to expand the Mezcal Market's off-trade segment meaningfully through 2035.

Agave-Based Sustainability Branding

Consumer surveys indicate that 61% of premium spirit buyers consider sustainability credentials when purchasing [16]. Mezcal producers who invest in reforestation, bat-pollination corridors, and carbon-neutral distillation can differentiate on ESG grounds — a growing priority across European and North American markets.

Emerging Market Penetration in South America and MEA

Brazil's imported spirits market expanded 12% in 2024, and UAE duty-free channels are increasingly stocking premium agave spirits [17]. These regions remain under-penetrated in the Mezcal Market, offering significant headroom for volume growth.

Mezcal Tourism and Experiential Marketing

Oaxaca received 2.3 million domestic and international tourists in 2024, with palenque tours emerging as a top activity [18]. Experiential marketing builds brand affinity and drives repeat purchases, creating a self-reinforcing demand loop for the global Mezcal Market.


Mezcal Market Future Outlook

Supply Chain Digitalization and Traceability

Blockchain traceability systems are coming to the Mezcal Market to verify denomination-of-origin claims and fight counterfeiting. By 2030, an estimated 35% of exported mezcal bottles would have provenance records tied to QR codes monitoring agave procurement, roasting, fermentation, and distillation [19]. Such transparency helps tackle the issue of consumer trust and better justifies premium pricing in all locations.


Premiumization Supercycle in Aged Expressions

Blanco expressions now dominate the Mezcal Market, but Reposado and Añejo expressions are rising at nearly double the category CAGR. With producers investing in barrel programs, including ex-bourbon, ex-wine, and indigenous wood aging, expect the aged category to follow the trajectory witnessed in premium tequila over the past decade. The IWSR expects premium-and-above spirits to make up 15% of volume globally, but 40% of value, by 2032 [5].


Sustainability and Biodiversity Standards

Producers who adopt bat-friendly agave harvesting, rainwater capture, and zero-waste distillation practices will gain preferential access to ESG-conscious European and North American retailers. The Mezcal Market's long-term growth depends on balancing wild agave biodiversity with commercial cultivation.

Cross-Category Convergence

Mezcal is increasingly appearing in non-traditional contexts: mezcal-infused chocolate, mezcal-aged coffee, and mezcal-based botanical spirits. These crossover products expand the addressable Mezcal Market beyond traditional bar consumption and into gourmet food retail, gifting, and experiential dining — channels that collectively represent a multi-billion-dollar global opportunity [20].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 53% share (2025) Import infrastructure, cocktail culture, DTC channels
Europe 22% share (2025) On-trade premiumization, GI recognition
Asia-Pacific 13.1% CAGR (2026–2035) Mixology adoption, duty-free expansion
South America USD 0.06 Billion (2025) Domestic agave spirits crossover
Middle East & Africa 5.1% CAGR (2026–2035) Luxury hospitality, duty-free retail
Total USD 0.69 Billion (2025) —

The Mezcal Market's geographic footprint spans traditional production zones in Mexico through fast-growing consumption markets across five continents.


North America

Country Key Metric Key Driver
US 71% of regional share Cocktail culture, mezcaleria proliferation
Canada 8.6% CAGR Premium spirit import growth
Mexico USD 0.11 Billion Production origin, domestic consumption rise


The US remains the single largest consumption market for mezcal worldwide. DISCUS data shows mezcal imports reached 5.8 million liters in 2024, a record driven by both on-trade cocktail programs and off-trade retail shelf expansion [3]. Mexico, as the sole country of origin, captures production-side value while experiencing a domestic Mezcal Market renaissance as younger consumers rediscover heritage spirits. Canada's provincial liquor boards have expanded mezcal listings by 40% since 2022.

Europe

Country Key Metric Key Driver
Germany 8.4% CAGR Craft bar movement
UK 28% of regional share Premium cocktail culture
France USD 0.02 Billion Sommelier-led adoption
Italy 7.1% CAGR Aperitif crossover interest
Spain 18% of regional share Cultural proximity to Mexican spirits
Nordic Countries 6.8% CAGR Sustainable spirits demand
Russia USD 0.004 Billion Niche premium import
Rest of Europe 12% of regional share Emerging cocktail scenes


The UK leads European Mezcal Market consumption, fueled by London's cocktail bar density and major retailers stocking premium expressions. Spain's cultural ties to Mexico give it an organic advantage, while Germany's burgeoning craft spirits scene is creating new entry points. The EU's pending geographical indication discussions for mezcal could streamline import certification and further boost volumes across the continent [6].

Asia-Pacific

Country Key Metric Key Driver
China 14.2% CAGR Urban premium spirit discovery
India USD 0.005 Billion Early-stage luxury imports
Japan 32% of regional share Established cocktail bar culture
South Korea 13.8% CAGR K-cocktail trend
ASEAN USD 0.006 Billion Tourism and hospitality
Rest of Asia-Pacific 9.4% CAGR Duty-free channels


Japan anchors the Asia-Pacific Mezcal Market thanks to a decades-old bartender culture that prizes ingredient provenance. Tokyo alone hosts over 40 mezcal-focused bars. South Korea's rapid cocktail scene expansion and China's growing appetite for imported luxury spirits are pulling the region's CAGR well above the global average [8].

South America

Country Key Metric Key Driver
Brazil 48% of regional share Imported spirits growth
Argentina 7.9% CAGR Premium bar culture
Rest of South America USD 0.01 Billion Nascent demand


Brazil's São Paulo cocktail scene has embraced mezcal as an alternative to cachaça in smoke-forward drinks, making it the region's primary demand center for the Mezcal Market. Argentina's established wine and spirits culture provides a natural bridge for premium agave expressions.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia USD 0.003 Billion Luxury hospitality
UAE 38% of regional share Duty-free and premium bars
South Africa 6.2% CAGR Craft spirit curiosity
Egypt USD 0.002 Billion Tourism-driven consumption
Rest of MEA 5.8% CAGR Hotel and resort channels


The UAE drives Middle East & Africa Mezcal Market consumption through its duty-free infrastructure and luxury hotel bars. Dubai's cocktail bar count grew 19% in 2024, and mezcal is increasingly featured alongside premium tequila and whiskey offerings in high-end venues [17].


Mezcal Market By Region, 2025-2035

Mezcal Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Mezcal Joven 72% share (2025) Entry-level accessibility, cocktail use
Mezcal Reposado USD 0.09 Billion (2025) Sipping culture, mild oak character
Mezcal Añejo 13.6% CAGR (2026–2035) Collector demand, aged spirit trend


Mezcal Joven dominates the Mezcal Market because its unaged profile makes it versatile for cocktails and accessible at lower price points. Bartenders favor Joven for its clean smoke character and mixability. Añejo expressions, aged 12 months or more, attract consumers migrating from whiskey and cognac who value complexity and barrel influence — explaining their outsized growth trajectory.

By Production Method

Segment Key Metric Primary Demand Driver
Ancestral Mezcal 87% share (2025) CRM heritage requirements
Artisanal Mezcal 11.9% CAGR (2026–2035) Scalable copper-pot production
Industrial Mezcal USD 0.02 Billion (2025) Cost-competitive mass segment


Ancestral production — defined by clay-pot distillation and hand-milled agave — constitutes the backbone of the Mezcal Market. Artisanal methods, which permit copper stills, are growing fastest because they allow mid-scale producers to maintain certified quality while increasing throughput. Industrial mezcal remains a small fraction, constrained by consumer preference for heritage credentials.

By Price Range

Segment Key Metric Primary Demand Driver
Mass 60% share (2025) Volume-driven cocktail demand
Premium/Luxury 12.3% CAGR (2026–2035) Connoisseur and gifting segments


The Mass price range segment leads the Mezcal Market with a dominant 60% share in 2025, driven by surging volume demand across high-volume on-premise bars and restaurants utilizing entry-level artisan expressions for craft cocktail formulation. Meanwhile, the Premium/Luxury segment represents the fastest-growing price category, projecting a market-leading CAGR of 12.3% over the forecast period (2026–2035).

By Distribution Channel

Segment Key Metric Primary Demand Driver
On-Trade 63% share (2025) Bar and restaurant cocktail programs
Off-Trade 11.2% CAGR (2026–2035) E-commerce growth, retail shelf expansion


On-trade venues remain the primary discovery channel for the Mezcal Market, where bartender recommendations drive trial. Off-trade is accelerating as consumers repurchase familiar brands through retail and DTC platforms. The pandemic-era shift toward home cocktail consumption created lasting habits that continue to benefit off-trade growth.


Competitive Benchmarking

The Mezcal Market exhibits medium concentration, with the top five players holding an estimated 35–42% of global revenue. The competitive field blends multinational spirits conglomerates — who entered through acquisitions — with independent Mexican producers who control heritage supply chains. Market fragmentation at the artisanal end ensures that no single company dominates, while brand storytelling and denomination-of-origin provenance serve as key differentiators.

Company Est. Revenue Share Range Key Offerings for Mezcal Market Strategic Positioning
Pernod Ricard (Del Maguey) ~8–11% Single-village mezcal portfolio Heritage-premium positioning
Diageo ~6–9% Multi-brand agave portfolio Global distribution leverage
Bacardi Limited (Ilegal Mezcal) ~5–8% Joven, Reposado, Añejo expressions Bartender-community brand building
Davide Campari-Milano (Montelobos) ~4–7% Organic certified mezcal Sustainability-led branding
William Grant & Sons ~3–6% Premium portfolio expansion Cross-category spirits synergy
Clase Azul ~3–5% Ultra-premium handcrafted bottles Luxury collectible positioning
El Silencio Holdings ~2–4% Contemporary mezcal brand US millennial/Gen Z targeting
Mezcal Amores ~2–4% Single-origin expressions Biodiversity conservation messaging
Bruxo Mezcal ~1–3% Blended agave expressions Accessible premium entry
Ojo de Tigre ~1–3% Flavored and classic mezcal Innovation-forward product line


Recent News & Developments

  • Pernod Ricard (June 2017): Acquired a majority stake in Del Maguey Single Village® Mezcal, securing the top-selling artisanal mezcal brand in the United States and expanding its ultra-premium agave portfolio across global markets.


  • Bacardi Limited (September 2023): Completed the acquisition of Ilegal Mezcal, incorporating the leading super-premium artisanal 100% Espadín mezcal brand into its global distribution network to accelerate international expansion.


  • Davide Campari-Milano (October 2019): Acquired a 51% controlling stake in Montelobos Mezcal, integrating the organic artisanal brand into its luxury portfolio alongside Espolòn Tequila to strengthen its global agave presence.


  • Mexico's Secretaría de Economía (March 2017): Officialized NOM-070-SCFI-2016, establishing strict categories (Ancestral, Artisanal, Industrial) and labeling standards to prevent counterfeiting and guarantee denomination-of-origin authenticity.


Mezcal Market Report Scope

Parameter Detail
Market Scope Global Mezcal Market — production, trade, and consumption
Study Period 2021–2035
CAGR 10.2% (2026–2035)
Market Size (2025) USD 0.69 Billion
Market Size (2035) USD 1.82 Billion
Fastest Growing Segment Mezcal Añejo (by product type); Asia-Pacific (by region)
Companies Profiled 10
Valuation Currency USD Billion

FAQs

How does CRM certification affect new entrants' time to market?
New producers typically face a 6–12 month certification cycle covering palenque inspection, batch testing, and labeling compliance. This timeline extends further for producers outside Oaxaca seeking certification in newer denomination-of-origin states [1].
What barrel types are driving the Mezcal Añejo growth trend?
Ex-bourbon American oak leads aged expressions, but ex-Bordeaux and indigenous Encino wood barrels are gaining traction. These alternative casks create differentiated flavor profiles that justify USD 100+ retail pricing [21].
How does agave species selection influence production costs?
Espadin matures in 7–8 years and offers predictable yields. Wild species like Tobalá or Tepeztate require 15–25 years, making them five to eight times costlier per liter of distillate [11].
What role do mezcal cooperatives play in the supply chain?
Cooperatives aggregate small-producer output, provide shared certification infrastructure, and negotiate collective export contracts. They represent roughly 30% of certified production volume in Oaxaca [1].
How are tariff structures affecting Asia-Pacific expansion?
Japan applies 0% tariffs under CPTPP, while China assesses MFN duties (~10%). Because a bilateral Mexico–South Korea FTA remains pending, exporters navigate standard import duties across Korean channels while leveraging growing regional demand.
What quality risks emerge from rapid production scaling?
Accelerated agave harvesting before full maturation reduces sugar content, yielding lower-quality distillate. Producers balancing growth with quality typically maintain minimum 7-year harvest cycles [11].
How does the Mezcal Market compare to tequila in premiumization velocity?
Mezcal's premium-and-above share is growing roughly 2.5 times faster than tequila's equivalent tier. Its smaller base and stronger provenance narrative give it a steeper premiumization curve [5].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, trade publications, academic journals, and authoritative industry organizations. Key sources included the Alcohol and Tobacco Tax and Trade Bureau (TTB), Consejo Regulador del Mezcal (CRM) – Mexico's official Denomination of Origin regulatory body, Comisión Federal para la Protección contra Riesgos Sanitarios (COFEPRIS), European Union Spirits Regulation (EU) 2019/787, U.S. Food & Drug Administration (FDA) Code of Federal Regulations Title 27, International Wine and Spirit Research (IWSR), Distilled Spirits Council of the United States (DISCUS), Spirits Europe, Wine & Spirits Wholesalers of America (WSWA), Asia Pacific International Wines & Spirits Alliance, National Institute of Statistics and Geography (INEGI) – Mexico, U.S. Census Bureau Trade Data, Eurostat Alcoholic Beverages Database, FAOSTAT (agave cultivation data), World Health Organization (WHO) Global Status Report on Alcohol, National Center for Biotechnology Information (NCBI/PubMed) – agave sustainability and fermentation studies, Smithsonian Institution – ethnobotanical research, and Mexico's Secretariat of Economy export reports. These sources were utilized to collect production statistics (NOP certified organic vs. conventional), export/import volumes by Denomination of Origin status, agave price trends, regulatory compliance data, and market landscape analysis across artisanal, ancestral, and industrial mezcal categories.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Sources of supply-side information included CEOs, Master Mezcaleros, Directors of Production, regulatory compliance officers, and export managers from certified mezcal distilleries (palenques), negocios, and OEM bottlers. Master sommeliers, beverage directors, procurement managers from premium spirits distributors, specialty retailers, mixologists from craft cocktail establishments, and category managers from e-commerce alcohol platforms comprised demand-side sources. The primary research validated market segmentation across aging categories (Joven vs. Extra Añejo growth), confirmed the timelines for Oaxacan vs. Durango production expansion, and gathered insights on premium pricing strategies, sustainable agave sourcing dynamics, and the complexities of a three-tier distribution system.

Primary Respondent Breakdown:

By Designation: C-level Primaries (CEO/Founder/Master Distiller) – 30%, Director Level (Operations/Export/Brand) – 32%, Others (Sommeliers/Category Managers/Procurement) – 38%

By Region: North America (U.S. & Canada) – 32%, Europe (UK, Spain, Germany) – 30%, Asia-Pacific (Japan, Australia, Southeast Asia) – 28%, Rest of World (South America, MEA, Domestic Mexico) – 10%

[Note: Tier classifications based on total spirits portfolio revenue as of 2024; Mezcal-specific operations evaluated separately for artisanal segment]


Market Size Estimation

Global market valuation was derived through revenue mapping and volume analysis across the value chain. The methodology included:

Identification of 60+ key producers across Oaxaca, Guerrero, Durango, San Luis Potosí, Zacatecas, and Puebla (Denominations of Origin regions), plus international bottlers

Product mapping across Joven (unaged), Reposado (2–12 months), Añejo (1–3 years), and Extra Añejo (>3 years) categories by agave species (Angustifolia, Potatorum, Karwinskii, etc.)

Analysis of certified export volumes vs. domestic consumption, cross-referenced with CRT (Consejo Regulador del Mezcal) export permits and TTB import data

Coverage of producers representing 65–70% of global export market share and 45–50% of artisanal production volume in 2024

Extrapolation using bottom-up (case volume × Average Selling Price by country/aging category) and top-down (distillery capacity utilization × export revenue validation) approaches to derive segment-specific valuations, including separate modeling for on-trade (Bars/Restaurants) vs. off-trade (Retail/E-commerce) channel margins

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















