Medical Kiosk Market (2026 - 2035)

Medical Kiosk Market Research Report: Size, Share, Trend Analysis By Product Type (Self-Service Kiosks, Interactive Kiosks, Mobile Kiosks), By Screen Display Size (Less than 32 Inches, 32-42 Inches, 43-55 Inches, Larger than 55 Inches), By Functionality (Telemedicine, Patient Check-In and Registration, Information and Education, Appointment Scheduling, Payment Processing) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035

Forecast Period
2026-2035
CAGR
11.8%
2025 Market Size
USD 1.82 Billion
2035 Market Size
USD 5.57 Billion
Medical Device ● Updated August 24, 2026 Report ID: MRFR/MED/24851-HCR | Pages: 128 | Author: Satyendra Maurya, Rahul Gotadki

Medical Kiosk Market Summary

The medical kiosk market reached USD 1.82 billion in 2025 and is projected to grow from USD 2.04 billion in 2026 to USD 5.57 billion by 2035, registering a CAGR of 11.8% during the forecast period (2026–2035). Two structural forces are accelerating deployment. First, the 21st Century Cures Act and successive ONC interoperability mandates in the United States now require providers to give patients electronic access to health data at the point of care, and self-service kiosks offer a compliant, low-friction channel [1]. Second, global healthcare staffing shortfalls — the WHO projects a shortage of 10 million health workers by 2030 — are pushing hospital networks to automate registration, copay collection, and vitals capture through unattended terminals [2].

Technology shifts are also relevant to the trajectory of the medical kiosk business. Touchscreen kiosks with biometric identification, AI-powered symptom triage and integrated telemedicine cameras are replacing the legacy paper-based registration desks and manual payment windows. The U.S. Department of Health and Human Services awarded more than USD 80 billion in digital health infrastructure grants between 2021 and 2024, much of it to ambulatory and rural sites where kiosk-based care delivery fills both cost and access needs [3].


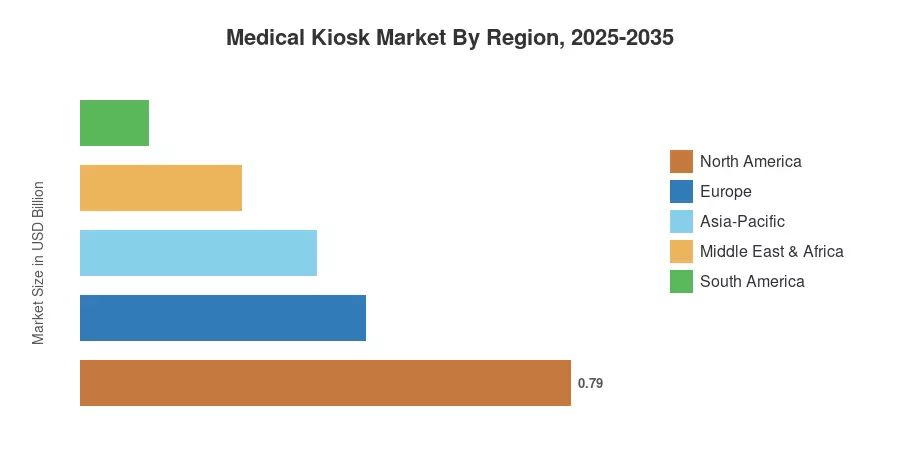
In 2025, North America held a share of around 43.2% in the medical kiosk market, backed by developed EHR ecosystems and insurance-driven self-check-in procedures. The Asia-Pacific region is the fastest-expanding region with a predicted CAGR of 20.9% through 2035, due to the Ayushman Bharat Digital Mission in India and the wave of smart hospital construction in China. Europe accounted for the second-largest proportion, at around 25.3 %, owing to the EU4Health programme and increasing deployment across National Health Service (NHS) trusts in the United Kingdom [4]. As 5G connection expands to more countries and AI-enabled diagnostic peripherals become routine add-ons, the medical kiosk industry is set to move from a convenience accessory to a fundamental node of omnichannel care delivery.


Key Report Takeaways

• By Type & Component

  • Check-in kiosks held 35.4% of the medical kiosk market in 2025, reflecting widespread hospital adoption of automated registration.
  • Telemedicine kiosks are forecast to expand at a 14.8% CAGR through 2035 as retail pharmacies and employers embed virtual-care capabilities.
  • The services component is projected to post a 16.3% CAGR through 2035, outpacing hardware and software growth as health systems demand managed integration contracts.

• By Deployment & End User

  • Indoor deployments accounted for 48.1% of the medical kiosk market share in 2025, concentrated in hospital lobbies and outpatient registration areas.
  • Pharmacies and drugstores are the fastest-growing end-user segment, registering a 19.8% CAGR through 2035 as chains convert foot traffic into care-access points.

• By Geography

  • North America led the medical kiosk market with a 43.2% share in 2025.
  • Asia-Pacific is set to surge at a 20.9% CAGR to 2035, driven by government-led digital health mandates in India, China, and Southeast Asia.


Market Size and Forecast (2021–2035)

Market Research Future (MRFR) estimates are based on a bottom-up revenue analysis of equipment suppliers, software licensors and managed-service providers, validated against a top-down spending analysis of hospital IT budgets and government procurement filings. Historical estimates (2021-2024) are based on real shipping and contract data; the prediction (2026-2035) is based on an 11.8% compound annual growth rate anchored to current pipeline visibility and policy roadmaps.
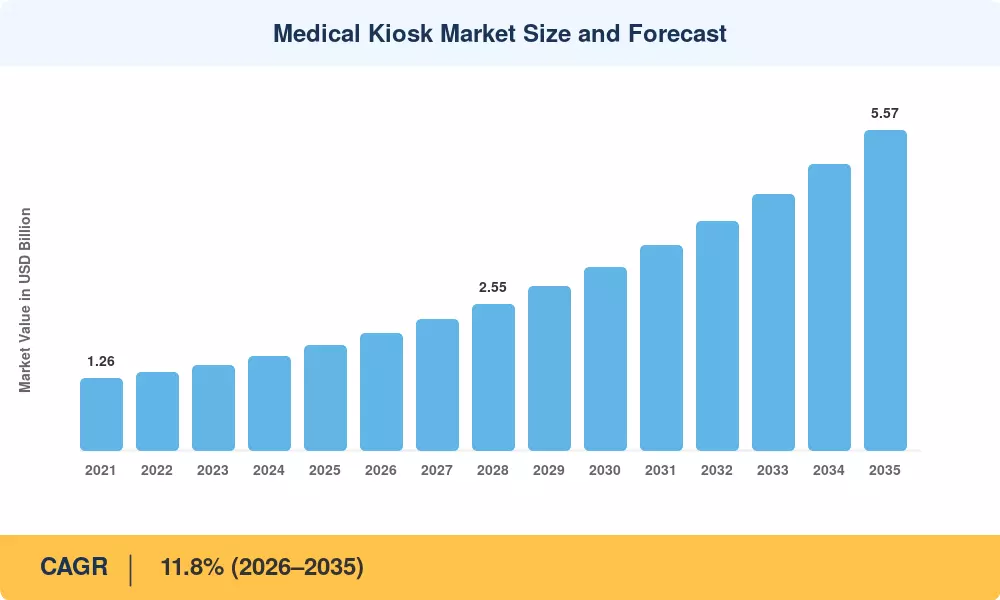
Medical Kiosk Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

What Are the Key Drivers Fueling the Medical Kiosk Market Growth?

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Healthcare workforce shortages ~18% Global Short-term (≤2 yr)
Government digital-health mandates ~17% North America, Asia-Pacific Medium-term (2–4 yr)
Telemedicine and virtual-care expansion ~16% North America, Europe Medium-term (2–4 yr)
5G and edge-computing deployment ~14% Asia-Pacific, North America Long-term (≥4 yr)
AI-driven diagnostic peripherals ~13% Global Long-term (≥4 yr)
Retail and non-traditional care venues ~12% North America, Europe Short-term (≤2 yr)
Patient experience and self-service expectations ~10% Global Short-term (≤2 yr)


Healthcare Workforce Shortages

The WHO estimates that the global healthcare sector will face a deficit of 10 million workers by 2030, with nursing and front-desk administrative roles among the hardest to fill [2]. In the United States, the Bureau of Labor Statistics projects robust employment growth across healthcare occupations through 2032, driven by an aging population and rising demand for care. Hospitals responding to these structural gaps are increasingly automating intake workflows and deploying self-service check-in kiosks to streamline front-desk operations and optimize staffing per shift [10]. This driver has an immediate short-term impact on the medical kiosk market because the labor constraint is structural and worsening.


Government Digital-Health Mandates

Regulatory pressure is a powerful accelerator. The ONC's HTI-1 final rule, effective January 2025, tightens interoperability requirements and pushes certified EHR vendors to expose patient data at the point of service — kiosks included [1]. In India, the Ayushman Bharat Digital Mission targets 500 million digital health IDs, creating a national identity layer that kiosk manufacturers can integrate for authentication and insurance verification [11]. These mandates create a compliance pull that converts optional kiosk investments into near-mandatory infrastructure for the medical kiosk market.

Telemedicine and Virtual-Care Expansion

Telehealth utilization has established a strong baseline in outpatient care, and CMS extended Medicare telehealth flexibilities through 2026 [6]. Retail pharmacy chains have responded by installing telemedicine-equipped kiosks in store locations, converting foot-traffic venues into walk-in virtual-consultation sites. Each unit allows health systems to expand physical footprint and patient access with a lower capital outlay compared to building traditional brick-and-mortar nurse practitioner stations, delivering strong payback periods and driving significant new demand in the medical kiosk market [9].


AI-Driven Diagnostic Peripherals

FDA clearances of AI-enabled screening devices (such as retinal scanners, spirometers, and otoscopes) designed for point-of-care integration continued to grow throughout 2024 [8]. These peripherals transform a basic check-in terminal into a clinical assessment station capable of capturing vitals, conducting preliminary screenings, and routing results to EHR systems. Vendors bundling AI diagnostics with kiosk hardware report higher average selling prices and longer contract terms, which lifts per-unit revenue across the medical kiosk market.


What Factors Are Restraining the Medical Kiosk Market?

The restraint impacts below are directional estimates of how each factor moderates the medical kiosk market growth rate. They are not directly subtracted from the headline CAGR.

Restraint ~% Negative Impact on CAGR Geographic Relevance Impact Timeline
Data privacy and cybersecurity concerns ~–20% Global Medium-term (2–4 yr)
High upfront capital and integration costs ~–18% Emerging markets Short-term (≤2 yr)
Digital literacy gaps among elderly patients ~–15% Global Long-term (≥4 yr)
Fragmented regulatory standards ~–12% Europe, MEA Medium-term (2–4 yr)
Reimbursement uncertainty for kiosk-delivered care ~–10% North America Short-term (≤2 yr)


Data Privacy and Cybersecurity Concerns

Medical kiosks collect PHI (protected health information) in semi-public spaces, raising HIPAA, GDPR, and local-law compliance challenges. The HHS Office for Civil Rights reported a 93% increase in large healthcare data breaches between 2018 and 2023, and kiosk endpoints — often running embedded Windows or Linux without real-time patching — are attractive targets [12]. Vendors must invest in encrypted storage, tamper-proof enclosures, and SOC-2 audited cloud backends, which adds 15–25% to total cost of ownership and slows procurement cycles within the medical kiosk market.

High Upfront Capital and Integration Costs

A fully integrated kiosk deployment — including hardware, EHR middleware, payment processing, and installation — typically costs USD 25,000–45,000 per unit. For a 200-bed hospital installing 12–15 kiosks, total project costs can exceed USD 500,000 before training and maintenance [13]. Community health centers and providers in lower-income countries often lack the capital budgets or IT staff to absorb these costs, limiting penetration in segments where access-expansion benefits would be greatest.

Digital Literacy Gaps

Patients aged 65 and older — who account for over 35% of hospital visits in the U.S. — show significantly lower comfort with self-service digital interfaces [14]. A 2024 Pew Research study found that 27% of Americans over 65 do not use the internet at all, and kiosk abandonment rates in this demographic run 3–4 times higher than among patients under 50. Until user interfaces incorporate voice navigation, multilingual support, and adaptive simplification, this restraint will moderate adoption velocity in the medical kiosk market.


Medical Kiosk Market Opportunities

Emerging-Market Expansion Through Government Health Digitization

Countries across Southeast Asia, Sub-Saharan Africa, and Latin America are channeling World Bank and ADB loans into primary-care digitization. Indonesia's Satu Sehat platform and Nigeria's eHealth Strategy 2020–2025 both call for digital registration at primary health centers, creating greenfield demand for ruggedized, low-cost medical kiosk market solutions.

Data Monetization and Population Health Analytics

Aggregated, de-identified data flowing through kiosk networks — vitals, symptom trends, insurance mix — offers population health analytics opportunities for payers and pharmaceutical companies. Kiosk operators that build HIPAA-compliant data lakes and sell anonymized insights can generate recurring SaaS revenue streams alongside hardware margins, reshaping unit economics across the medical kiosk market.

Employer-Sponsored Onsite Health Kiosks

Large employers spend an average of USD 15,000 per employee annually on healthcare benefits in the U.S. Deploying onsite kiosks for biometric screenings, chronic-disease check-ins, and virtual consultations reduces absenteeism and emergency-room utilization. Companies with 500-plus employees are an underpenetrated channel for the medical kiosk market.

Pharmacy-Retail Convergence

Major retail chains are pivoting toward healthcare services. CVS, Walgreens, and Walmart collectively operate over 20,000 pharmacy locations in the U.S. alone, and each represents a potential site for a patient self-service kiosk offering prescription pickup verification, insurance eligibility checks, and telehealth consultations.

AI-Enabled Chronic Disease Management

Remote patient monitoring for diabetes, hypertension, and COPD is projected to exceed USD 120 billion globally by 2030. Kiosks placed in community settings that capture HbA1c readings, blood pressure, and pulse oximetry between provider visits create a new longitudinal-care touchpoint for the medical kiosk market.


Medical Kiosk Market Future Outlook

AI-Augmented Clinical Kiosks

By 2030, kiosks will evolve from administrative terminals into clinical-grade assessment stations. FDA and CE clearances for kiosk-compatible AI diagnostics — retinal imaging, dermatology screening, and pulmonary function analysis — are accelerating, with the FDA clearing 171 AI-enabled medical devices in 2023 alone [8]. This expansion transforms the medical kiosk market from a front-desk automation play into an extension of clinical care pathways.

Platform Economics and Kiosk-as-a-Service

Capital-expenditure barriers are falling as vendors shift to subscription-based Kiosk-as-a-Service (KaaS) models that bundle hardware, software updates, and maintenance for a monthly per-unit fee. KaaS contracts reduce procurement friction for smaller providers and generate predictable recurring revenue for vendors, reshaping competitive dynamics within the medical kiosk market over the coming decade.

Decentralized Care and Community Health Hubs

Grocery chains, community banks, and transit authorities are embedding healthcare information terminals in high-traffic venues. Walmart Health operated over 50 clinic locations before restructuring, and similar models are being replicated globally. The medical kiosk market will benefit as decentralized care moves from pilot phase to systematic rollout across non-traditional venues [9].

Sustainability and Circular Hardware Design

ESG reporting requirements under the EU Corporate Sustainability Reporting Directive (CSRD) and investor pressure are pushing kiosk manufacturers toward modular, repairable designs with longer hardware lifecycles [21]. Vendors adopting circular-economy principles — leased components, recyclable enclosures, energy-efficient displays — will gain procurement advantages in public-sector tenders, influencing supply-chain strategy across the medical kiosk market.


Medical Kiosk Market Segmentation

By Type

Segment Key Metric Primary Demand Driver
Check-In Kiosks 35.4% share (2025) EHR-integrated patient registration automation
Payment Kiosks USD 0.38 Billion (2025) Insurance copay collection and billing self-service
Telemedicine Kiosks 14.8% CAGR (2026–2035) Retail-pharmacy virtual-care expansion
Other Kiosk Types USD 0.24 Billion (2025) Wayfinding, prescription pickup, patient education


Check-in kiosks remain the largest type segment in the medical kiosk market because virtually every hospital visit begins with registration — a high-volume, repetitive workflow ideally suited to automation. Systems that capture insurance cards, verify identity via biometrics, and push demographic data directly into Epic or Cerner reduce front-desk processing time from 8–12 minutes to under 90 seconds [10].

Telemedicine kiosks represent the fastest-growing type. Retail pharmacy chains are installing enclosed, soundproofed units with integrated vital-sign peripherals that connect patients to board-certified physicians on demand. Each deployment extends the addressable footprint of the medical kiosk market beyond traditional clinical settings.

By Component

Segment Key Metric Primary Demand Driver
Hardware 54.6% share (2025) Touchscreens, enclosures, biometric readers, printers
Software USD 0.42 Billion (2025) EHR middleware, payment gateways, UI/UX platforms
Services 16.3% CAGR (2026–2035) Managed integration, maintenance, analytics subscriptions


Hardware still captures the majority of the medical kiosk market by revenue, reflecting the capital-intensive nature of initial deployments. Yet services are growing fastest as health systems demand end-to-end managed contracts that cover installation, EHR integration, cybersecurity monitoring, and 24/7 technical support rather than purchasing standalone equipment.

By End User

Segment Key Metric Primary Demand Driver
Hospitals 64.5% share (2025) High patient volumes and administrative automation needs
Clinics & Ambulatory Care Centers USD 0.29 Billion (2025) Outpatient workflow optimization
Pharmacies & Drugstores 19.8% CAGR (2026–2035) Retail-care convergence and walk-in telemedicine
Other End Users USD 0.10 Billion (2025) Employer worksites, community centers, airports


Hospitals dominate end-user spending in the medical kiosk market because they handle the highest throughput of patient encounters. Large academic medical centers deploy 15–30 kiosks per campus, spanning emergency-department triage, outpatient check-in, and inpatient wayfinding.

Pharmacies and drugstores are the fastest-growing end-user channel. National chains view kiosks as a low-capex, high-utilization mechanism to transform pharmacy counters into primary-care access points, which is reshaping the competitive contours of the medical kiosk market.


Which Region Leads the Medical Kiosk Market?

Region Key Metric Primary Investment Themes
North America 43.2% share (2025) EHR integration mandates, retail-pharmacy telemedicine
Europe USD 0.46 Billion (2025) EU4Health digital infrastructure, NHS self-service rollouts
Asia-Pacific 20.9% CAGR (2026–2035) Government digital-ID programmes, smart-hospital construction
South America USD 0.11 Billion (2025) Primary-care digitization loans, public-hospital modernization
Middle East & Africa 14.2% CAGR (2026–2035) Vision 2030 health sector investment, universal-coverage pilots
Total USD 1.82 Billion (2025)

The medical kiosk market exhibits pronounced regional variation driven by healthcare infrastructure maturity, regulatory frameworks, and digital-health investment cycles.


North America

Country Key Metric Key Driver
United States 78.5% of regional share ONC interoperability mandates and retail-pharmacy kiosk expansion
Canada USD 0.09 Billion (2025) Provincial digital-health strategies and telehealth funding
Mexico 13.8% CAGR (2026–2035) IMSS digital registration modernization programme


The United States dominates North America's medical kiosk market because its fragmented payer system incentivizes automated eligibility verification, copay collection, and patient-identification workflows. Over 5,500 hospitals now operate self-check-in kiosks, and CMS pilot programmes linking kiosk-captured vitals to value-based reimbursement are expanding coverage for kiosk-delivered services [16].

Europe

Country Key Metric Key Driver
Germany 24.8% of regional share Digital Health Applications (DiGA) framework integration
United Kingdom USD 0.10 Billion (2025) NHS self-check-in expansion under Long Term Plan
France 12.1% CAGR (2026–2035) Mon Espace Santé patient portal kiosk interfaces
Italy USD 0.04 Billion (2025) PNRR-funded hospital digitization
Spain 11.5% CAGR (2026–2035) Regional health authority procurement cycles
Nordic Countries USD 0.04 Billion (2025) High digital readiness, integrated EHR ecosystems
Russia 10.2% CAGR (2026–2035) Federal e-health modernization programme
Rest of Europe USD 0.05 Billion (2025) EU structural-fund digital-health grants


Europe's medical kiosk market benefits from strong public-health system mandates. Germany's DiGA framework, which certifies digital health applications for prescription, creates a regulatory pathway for kiosk-integrated screening tools. The UK's NHS has deployed over 3,000 self-check-in terminals across trusts, targeting a 50% reduction in reception-desk wait times by 2027 [17].

Asia-Pacific

Country Key Metric Key Driver
China 34.6% of regional share Smart-hospital construction mandates under Healthy China 2030
India 22.4% CAGR (2026–2035) Ayushman Bharat Digital Mission and ABHA ID integration
Japan USD 0.06 Billion (2025) Super-aging population driving automation
South Korea 18.7% CAGR (2026–2035) Korea Health Information Service digital-access targets
ASEAN USD 0.04 Billion (2025) ADB-funded primary-care digitization
Rest of Asia-Pacific 16.5% CAGR (2026–2035) Greenfield healthcare infrastructure build-outs


Asia-Pacific represents the highest-growth frontier for the medical kiosk market. China's National Health Commission mandated smart-outpatient systems in all tertiary hospitals by 2025, triggering orders for tens of thousands of check-in and payment kiosks [18]. India's ABHA digital health ID — with over 600 million registrations — offers a national authentication layer that kiosk manufacturers can leverage for identity verification and claims processing [11].

South America

Country Key Metric Key Driver
Brazil 58.3% of regional share SUS public-health system digitization
Argentina 14.6% CAGR (2026–2035) Urban hospital modernization programmes
Rest of South America USD 0.02 Billion (2025) Inter-American Development Bank health-IT funding


Brazil's Unified Health System (SUS) serves over 150 million citizens and is digitizing registration through the ConecteSUS platform. Kiosk integration with ConecteSUS health cards is a priority in São Paulo and Rio de Janeiro state hospital networks, positioning Brazil as the gateway for the medical kiosk market in Latin America [19].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 36.2% of regional share Vision 2030 healthcare cluster investments
UAE 15.8% CAGR (2026–2035) Smart-city health infrastructure under Dubai 2040 Plan
South Africa USD 0.02 Billion (2025) NHI pilot-phase facility modernization
Egypt 13.5% CAGR (2026–2035) Universal Health Insurance Law rollout
Rest of MEA USD 0.03 Billion (2025) WHO-supported primary-care digitization


Saudi Arabia's Health Holding Company is deploying self-service kiosks across all new hospital builds under Vision 2030, and the UAE's DHA (Dubai Health Authority) mandated digital check-in at licensed facilities effective 2025 [20]. These policy-driven deployments anchor Middle East growth in the medical kiosk market.


Medical Kiosk Market By Region, 2025-2035

Competitive Benchmarking

The medical kiosk market is highly concentrated. The top five vendors have an estimated combined revenue share of 35-42%, and dozens of regional integrators and niche telemedicine kiosk experts serve local health systems. Competition is shifting increasingly from hardware differentiation to depth of software platform, EHR interoperability certifications and scope of managed-service contract.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Vecna Technologies ~8–11% Patient check-in kiosks, QueueView workflow platform Integrated queue-management and patient-flow analytics
Olea Kiosks ~7–10% Custom healthcare kiosk enclosures, ADA-compliant designs Design-forward hardware with strong retail-health channel
Clearwave Corporation ~6–9% Patient-access platform, eligibility verification kiosks Software-led approach emphasizing revenue-cycle integration
Frank Mayer and Associates ~5–8% Interactive kiosk design and manufacturing Full-service OEM with cross-industry kiosk expertise
Elo Touch Solutions ~4–7% Touchscreen hardware, open-frame displays for healthcare Component supplier and OEM partner to system integrators
Advantech Co., Ltd. ~4–6% Medical-grade panel PCs, intelligent kiosk platforms Industrial IoT backbone with global service network
Meridian Kiosks ~3–6% Indoor/outdoor healthcare kiosks, payment terminals Broad product line with quick-ship manufacturing
DynaTouch ~3–5% Patient queuing kiosks, wayfinding systems Government and VA health system specialist
Aila Technologies ~2–5% Tablet-based interactive kiosk platforms Modular, software-configurable patient-engagement devices
PatientPoint ~2–4% Point-of-care engagement screens, waiting-room kiosks Content-driven patient-education and ad-supported model


Recent News & Developments


  • Advantech Co., Ltd. (November 2023): Released the UTC-520 medical-grade kiosk platform with antimicrobial housing and UL 60601-1 certification for clinical environments [25].
  • CMS / U.S. Government (October 2023): Extended Medicare telehealth flexibilities through December 2024, sustaining demand for kiosk-based virtual-care infrastructure in rural and underserved areas [16].


Medical Kiosk Market Report Scope

Parameter Detail
Market Scope Global medical kiosk market covering hardware, software, and services across all deployment types.
Study Period 2021–2035
CAGR (Forecast Period) 11.8% (2026–2035)
Market Size (2025) USD 1.82 Billion
Market Size (2035) USD 5.57 Billion
Fastest Growing Segment Pharmacies & Drugstores (by end user); Asia-Pacific (by region)
Companies Profiled 10 (Vecna Technologies, Olea Kiosks, Clearwave Corporation, and others)
Valuation Currency USD Billion

FAQs

What cybersecurity certifications should buyers require when procuring medical kiosks?
Require SOC-2 Type II and HITRUST CSF certification at minimum. These validate that the vendor enforces encrypted data storage, access controls, and incident-response protocols compliant with HIPAA requirements [12].
How does the medical kiosk market address ADA and accessibility compliance?
Leading vendors offer ADA-compliant designs with wheelchair-height screens, tactile navigation, and screen-reader compatibility. Buyers should verify Section 508 compliance documentation before purchase [5].
What is the typical ROI timeline for a hospital deploying self-service kiosks?
Most deployments achieve payback within 14–20 months through reduced front-desk FTEs and faster patient throughput. High-volume emergency departments see the shortest ROI windows [10].
How do kiosk vendors handle EHR interoperability across different platforms in the medical kiosk market?
Vendors use HL7 FHIR APIs and pre-built connectors for Epic, Oracle Health, and MEDITECH. Buyers should confirm certified integration status with their specific EHR version [1].
What maintenance contract structures are common in the medical kiosk market?
Most vendors offer three-tier plans: basic warranty, preventive maintenance, and full managed service including 24/7 monitoring. Managed contracts typically cost 12–18% of hardware value annually [13].
How are outdoor medical kiosks weatherproofed for year-round operation?
Outdoor units use IP65-rated enclosures, thermostatically controlled heating and cooling, and anti-glare sunlight-readable displays. Coastal deployments add corrosion-resistant coatings [24].
What role do medical kiosks play in clinical trial patient recruitment?
Pharmaceutical sponsors place screening kiosks at high-traffic clinical sites to capture eligibility data and pre-consent volunteers. This accelerates enrollment timelines by 20–30% versus traditional methods [9].    
Author
Author
Author Profile
Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author
Co-Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, healthcare technology publications, government health IT reports, and authoritative healthcare organizations. Key sources included the US Department of Health and Human Services (HHS), Office of the National Coordinator for Health Information Technology (ONC), Centers for Medicare & Medicaid Services (CMS), Food and Drug Administration (FDA) for medical device regulations, HealthIT.gov, American Hospital Association (AHA), Healthcare Information and Management Systems Society (HIMSS), National Institutes of Health (NIH), Centers for Disease Control and Prevention (CDC), World Health Organization (WHO) Digital Health Repository, European Commission Health and Digital Executive Agency (HaDEA), Eurostat Healthcare Statistics, Organisation for Economic Co-operation and Development (OECD) Health Statistics, and national health ministry reports from key markets including NHS Digital (UK), Canada Health Infoway, Japan's Ministry of Health, Labour and Welfare, and Australia's Australian Digital Health Agency. These sources were used to collect healthcare IT adoption statistics, regulatory compliance data, telehealth integration studies, hospital infrastructure spending trends, and market landscape analysis for self-service kiosks, interactive kiosks, and mobile kiosk technologies across telemedicine, patient check-in, appointment scheduling, payment processing, and health information dissemination applications.


Primary Research

In order to get qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, Chief Technology Officers, heads of regulatory affairs, and commercial directors from OEMs, healthcare IT solution providers, and makers of medical kiosks were examples of supply-side sources. Chief information officers (CIOs), chief medical information officers (CMIOs), hospital administrators, directors of clinic operations, telehealth program managers, and procurement leads from hospitals, health systems, ambulatory surgical centers, retail health clinics, and pharmacy chains were among the demand-side sources. In addition to confirming product development timelines and validating market segmentation across product types (self-service, interactive, mobile), screen display sizes, and functionality modules, primary research also collected information on pricing strategies, reimbursement dynamics, technology adoption patterns, and integration challenges with electronic health record (EHR) systems for self-service healthcare technologies.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and deployment volume analysis. The methodology included:

Identification of 40+ key manufacturers and healthcare technology vendors across North America, Europe, Asia-Pacific, and Latin America

Product mapping across self-service kiosks, interactive kiosks, and mobile kiosk categories segmented by screen display size (less than 32 inches, 32-42 inches, 43-55 inches, larger than 55 inches)

Functionality analysis covering telemedicine, patient check-in and registration, information and education, appointment scheduling, and payment processing modules

Analysis of reported and modeled annual revenues specific to medical kiosk portfolios and healthcare IT hardware divisions

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (deployment volume × ASP by country/healthcare setting) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for hardware, software, and services components

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















