SEGMENTATION QUICK REFERENCE
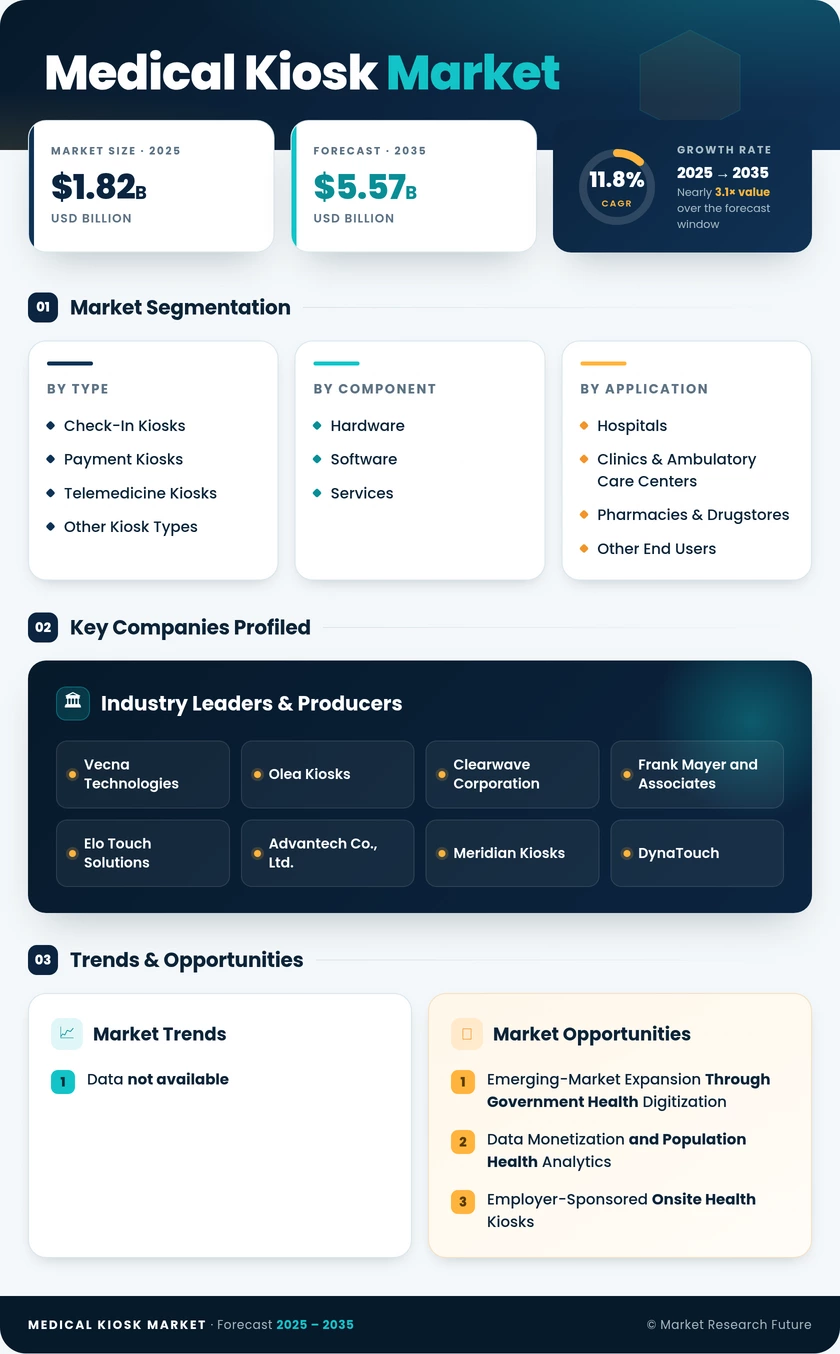
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | Check-In Kiosks, Payment Kiosks, Telemedicine Kiosks, Other Kiosk Types | Check-In Kiosks | Telemedicine Kiosks |
| By Component | Hardware, Software, Services | Hardware | Services |
| By Deployment Location | Indoor, Outdoor | Indoor | Outdoor |
| By Mobility | Freestanding, Wall-Mounted, Mobile/Cart | Freestanding | Mobile/Cart |
| By End User | Hospitals, Clinics & Ambulatory Care Centers, Pharmacies & Drugstores, Other End Users | Hospitals | Pharmacies & Drugstores |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America | Asia-Pacific |
MARKET SEGMENTATION OVERVIEW
By Type
| Sub-Segment | Key Trend |
| Check-In Kiosks | Biometric authentication and insurance-card scanning replace manual data entry. |
| Payment Kiosks | Contactless payment and real-time eligibility verification reduce billing errors. |
| Telemedicine Kiosks | Enclosed units with vital-sign peripherals enable walk-in virtual consultations. |
| Other Kiosk Types | Wayfinding, patient education, and prescription-pickup verification functions |
Check-in kiosks anchor current deployments across hospitals and large ambulatory networks, driven by the direct labor-cost offset they provide at high-throughput registration desks. Telemedicine kiosks are gaining ground rapidly as retail pharmacy and employer-worksite channels expand virtual-care access beyond traditional clinical walls.
By Component
| Sub-Segment | Key Trend |
| Hardware | Antimicrobial touchscreens, ADA-compliant enclosures, and integrated biometric readers |
| Software | EHR middleware, patient-engagement UIs, and analytics dashboards |
| Services | Managed integration, cybersecurity monitoring, and SLA-backed maintenance |
Hardware remains the largest component by revenue, but the services segment is growing fastest as health systems prefer vendor-managed contracts that cover the full deployment lifecycle from installation to ongoing support.
By Deployment Location
| Sub-Segment | Key Trend |
| Indoor | Hospital lobbies, outpatient clinics, and pharmacy counters |
| Outdoor | 24/7 access points in parking structures, campus perimeters, and transit hubs |
Indoor placements dominate today, but outdoor deployments are accelerating as IP65-rated hardware and 5G connectivity make round-the-clock access viable in locations that extend patient reach beyond facility interiors.
By Mobility
| Sub-Segment | Key Trend |
| Freestanding | Permanent floor-mounted units in fixed registration and payment areas |
| Wall-Mounted | Space-efficient installations in corridors and smaller clinics |
| Mobile/Cart | Wheeled units that move between departments or event-based screening sites |
Freestanding models dominate installed base, but mobile and cart-based solutions are growing fastest as hospitals and public-health agencies deploy portable screening kiosks for community outreach and surge-capacity scenarios.
By End User
| Sub-Segment | Key Trend |
| Hospitals | Multi-kiosk deployments spanning ED triage, outpatient, and inpatient services |
| Clinics & Ambulatory Care Centers | Compact check-in and payment units tailored for lower-volume sites |
| Pharmacies & Drugstores | Telemedicine-equipped units converting retail foot traffic into care encounters |
| Other End Users | Employer worksites, airports, community centers, and correctional facilities |
Hospitals account for the majority of installed units, but pharmacies and drugstores represent the fastest-growing channel as national retail chains pursue healthcare-services revenue. Employer-sponsored onsite kiosks are an emerging sub-segment with strong growth potential.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA