IoT Data Management Market Summary
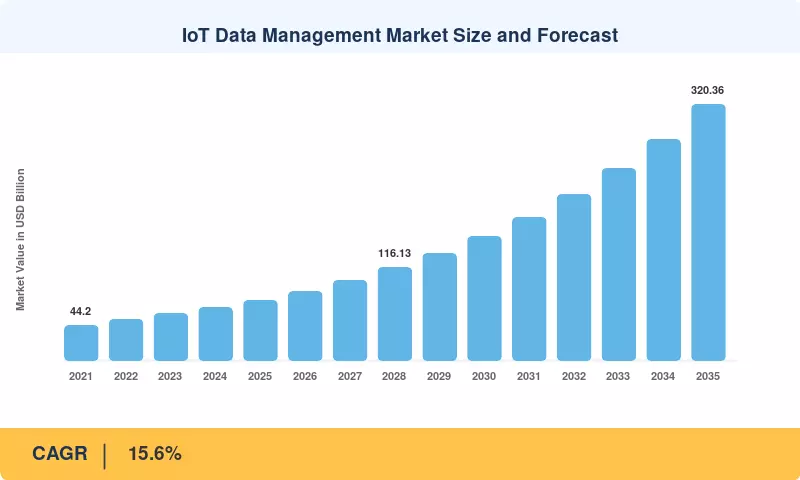
The IoT Data Management Market reached USD 75.20 billion in 2025 and opens the forecast window at USD 86.90 billion in 2026, advancing to USD 320.36 billion by 2035 at a 15.6% CAGR. Two catalysts anchor that trajectory. The European Union's Data Act, applicable from 12 September 2025, forces device makers to make sensor-generated telemetry accessible to users and third parties by design — a mandate that converts governed data pipelines from a nice-to-have into a compliance obligation [1]. In parallel, the U.S. Infrastructure Investment and Jobs Act allocated roughly USD 65 billion to grid modernization and broadband, seeding telemetry volumes that legacy historians were never built to hold [2].
Enterprises are retiring single-site SCADA historians, file-based data lakes, and batch ETL schedules in favour of time-series-native stores, streaming ingestion layers, and metadata catalogues that span factory floor to cloud region. The shift is capital-intensive: global spending on data infrastructure and analytics software passed USD 130 billion in 2024, with telemetry workloads among the fastest-expanding line items . Purpose-built architectures now absorb millions of writes per second while enforcing lineage, retention, and residency policy in the same control plane — something bolt-on integrations could not deliver.
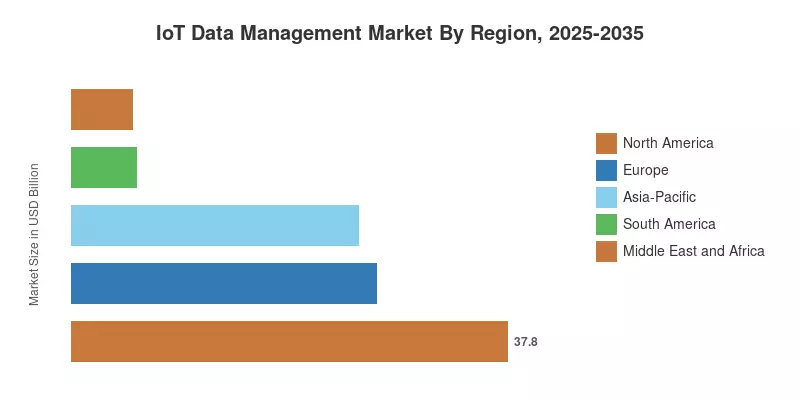
Regionally, North America commands 37.8% of 2025 revenue on the strength of hyperscaler proximity and industrial retrofit budgets. Asia-Pacific grows fastest at a 17.9% CAGR as China, India, and Japan scale manufacturing telemetry and utility metering. Europe ranks second at 26.4%, propelled less by volume than by regulation — GDPR, the Data Act, and NIS2 together make governed architecture a condition of market access. Through 2035, competitive advantage in the IoT Data Management Market will accrue to vendors that treat governance and analytics as one product rather than two.
Key Report Takeaways
• By Solution
- Analytics led the IoT Data Management Market with 33.9% of 2025 revenue as buyers shifted budget from raw capture to insight generation
- Stream processing is the fastest-expanding solution line at a 15.7% CAGR through 2035, reflecting the move to continuous decision loops
- Integration solutions generated USD 16.1 billion in 2025, sustained by brownfield protocol translation work
• By Deployment Model
- Cloud deployments held 65.4% of 2025 revenue, favoured for elastic compute against AI-intensive workloads
- Hybrid architectures posted the strongest growth at 15.9% CAGR as residency rules pin selected workloads on-premises
• By Data Type
- Time-series telemetry accounted for 44.8% of managed workloads in 2025, a legacy of SCADA and asset-health monitoring
- Unstructured inputs grow fastest at 15.7% CAGR as vision, acoustic, and language sensors proliferate
• By End-User Industry
- Manufacturing and Industrial captured 29.1% of 2025 revenue on quantifiable downtime savings
- Healthcare and Life Sciences record the steepest climb at 16.0% CAGR, driven by remote monitoring and trial digitization
• By Application
- Predictive maintenance remains the anchor use case at 26.1% of 2025 spend
- Asset tracking and fleet management expands at 15.8% CAGR as cold-chain integrity becomes a board-level metric
• By Region
- North America contributed 37.8% of 2025 IoT Data Management Market revenue
- Asia-Pacific is the fastest-growing region at 17.9% CAGR through 2035
- Europe held 26.4% of 2025 revenue, underpinned by mandatory data-access regimes
Market Size and Forecast (2021–2035)
Historical values for 2021–2024 were reconstructed from vendor revenue disclosures, cloud-provider segment reporting, systems-integrator backlog data, and a primary programme covering 62 enterprise buyers across eight industries. Forecast years apply a bottom-up build: installed endpoint base × managed-data volume per endpoint × blended realized price per managed terabyte, cross-checked against top-down IT budget allocations. The 2025 base year for the IoT Data Management Market was triangulated against public filings before the 15.6% forward CAGR was applied.





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


